Things Every Investor Should Know Before Investing

By
March 22, 2018
Share on:

Due to the nature of my profession, I am solicited for financial advice in all aspects of my life from all types of people. Similar to a doctor who gets asked about symptoms at birthday parties, people often ask for my opinion or input on financial matters, particularly investing. As most doctors will tell you, it’s hard to give advice when you don’t know the particulars.

However, if someone is really eager or serious for guidance on investing, I will suggest that they do their homework. The information they’re looking for isn’t found on the stock exchange or the Finance section of a newspaper.  Most times, the information you need to start with is found a lot closer than you would expect.

The first thing to take into account are your financial goals. As I’ve mentioned before, being aware of your financial “why” can highlight good habits, change inefficient patterns, refocus priorities and ultimately develop a plan to help you achieve your financial freedom. Therefore, you need to be specific. Do you want to retire in 30 years? Perhaps you want to buy a house in five years or start a business in two. In these scenarios, your goals act as targets, and with the help of a good financial planner, you can develop an action plan with measurable steps to incrementally achieve them.

Another thing to be aware of is your risk tolerance. This isn’t a measure of whether you like to bungee cord jump or skydive. Rather, this is an indication of how much volatility in your investments you are comfortable with. This is something that needs to be determined for the individual as well as the household. Risk tolerance is a very personal indicator, and there are times that couples don’t see eye to eye. When new clients come in, we have them complete a risk tolerance questionnaire to not only to see how individuals may or may not be working together but to also figure out the most effective plan to achieve their goals. The last thing we want you to do is tackle investments that won’t achieve your goals in a timely.

As you can tell, these items are all very personal. What you’re saving for, how long and hard you’re willing to work towards your goals, and what your income and lifestyle needs are, both current and future, will all be factors in planning how to invest. I bring this up because so many clients come in referring to the advice their friends, neighbors or coworker gave them. As I’ve mentioned before, I’m all for educating one’s self. Let’s discuss your options. But please don’t think that investing in what your child’s Little League coach is investing in is automatically the best option for you.

Let me put it another way. I’ve been athletic all of my life, playing high school and college baseball and an avid golfer. Knowing that, I’m not going to start a new exercise regime with a leisurely walk around the block or bench pressing 400 pounds. It’s not that I don’t believe these fitness goals are valid – they’re just not valid for me. The same idea can be applied to your finances. If any of the factors I’ve mentioned are not aligned, you may discover that the grass isn’t always greener on the other side, and that you need to be wary of the barb wire in between.

I know it sounds odd, that investing should be more complicated. But the truth is knowing your financial self is much important than knowing the stock market when you first start investing.
You may also like:

By Trilogy Financial
March 6, 2018

Recent market volatility and nervousness of investors seems to make this a good time to re-evaluate our current time frames and allocations for our investment accounts. One of the most important reasons is that our time frames and risk tolerance often clarify and determine the type of investment and allocation we should consider for our money.

Let’s agree that we might feel the market is efficient over a long period of time. With this kind of long-term perspective, should this recent volatility send us into a panic when evaluating our 401k and Roth IRA; investment accounts that possibly will be utilized 10, 15, or even 25 years from now? I anticipate you can come to my same conclusion…no. Let’s take this idea one step further. I would argue that panic should not be the response, but an excitement to save more, invest more, and watch our money possibly work more efficiently for us than if it was sitting in a safe, under the mattress, or at the bank. Market volatility and “correction” is healthy for long-term investors.

Now, I just alluded to two long-term retirement accounts. What if we have a 12-month goal to renovate the kitchen? That is a different time frame. That would result in a different level of risk. In fact, oftentimes, if the assets invested are to be purposed for a capital expense within the next twelve to twenty-four months, I then recommend holding on to cash and savings. The risks and costs of investing might be too high for our level of comfort for that short of a time-frame. Then, when we know the basement is set to be finished, the birth of a child is coming, or a rental property down payment are in sight, then we may want additional funds in the bank outside of our traditional three to six months of savings, especially if the time frame is tight.

And finally, what if we have additional cash that we don’t have a specific priority in mind for, and we have a comfortable amount in our bank savings, and we don’t want to wrap additional money into a retirement account and then not have access to it until after age 59 ½? This idea, this solution, is often unknown to investors. We are taught that we need to save into retirement accounts and make sure we have three to six months of emergency savings…but that’s not all we should consider. A non-retirement investment account helps us be more efficient with our excess cash or monthly cash flow, yet these invested assets are still accessible within 2-7 business days. In the 5, 10, or even 20 years until retirement, do we anticipate having a few non-retirement priorities? I’m confident the answer is “yes” for just about everyone. Or, maybe we run into a few unexpected things, too. Let me name a few examples…anniversary trip, home remodel, broken furnace, family vacation, new car, next down payment, adoption, or caring for our parents. Until we have a time frame, let’s believe in the market, invest our money in an efficient, cost-efficient, diversified portfolio, set to our level of risk and based on our anticipated time frame.

When a priority shows up, or even a BIG emergency, if we have been saving all along, it might make us better prepared. Just like a 401k, we can establish this type of investment account, determine a monthly contribution amount, and we can save and invest on a monthly basis. This could be incredibly impactful, because if we stick to the alternative of trying to over-save into our bank savings account, what might happen? Just prior to the end of the month, we might be too tempted to “slide to transfer” our “extra” funds right back into our bank checking. By establishing this additional, more efficient savings vehicle, funds that are earmarked for a future priority, outside of two years from now, will help us to be better prepared when that priority shows up, AND, hopefully having a stronger earning potential than what is available as interest at the bank.

This last example addresses an intermediate level of planning that tends to get lost in the emergency savings/retirement planning conversation. One consideration, please be aware that since these funds may not be in tax-deferred type of accounts, there may be various kinds of taxation on the growth and trading of holdings within these accounts. You would need to discuss taxation with your tax professional. Short- and long-term capital gains taxes are to be considered. But again, one of the biggest benefits of this type of account is that these funds tend to be more readily accessible. The flexibility of these types of non-retirement investment accounts are considered to be incredibly instrumental.

To summarize, if you are funding your 401k, and you have an adequate level of savings in the bank, and still have additional cash flow that could be used for future priorities, then I encourage you to establish an individual or joint non-retirement investment account for those exact goals. But first, please schedule time to meet with a Certified Financial Planner to help craft a strategy for your financial plan. He/she will help you better understand your time frames, your priorities, which will then determine your allocation, your level of risk, your investment, and the titling of the accounts.

So, despite the market volatility, the encouragement is the same: spend less, save more, start today.

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


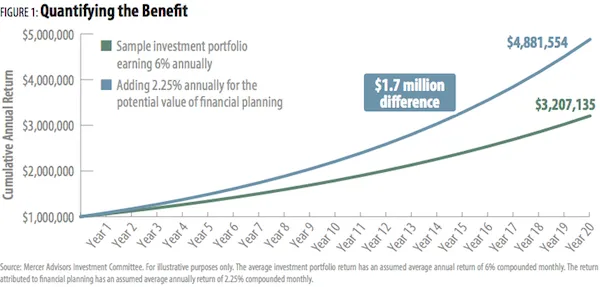
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


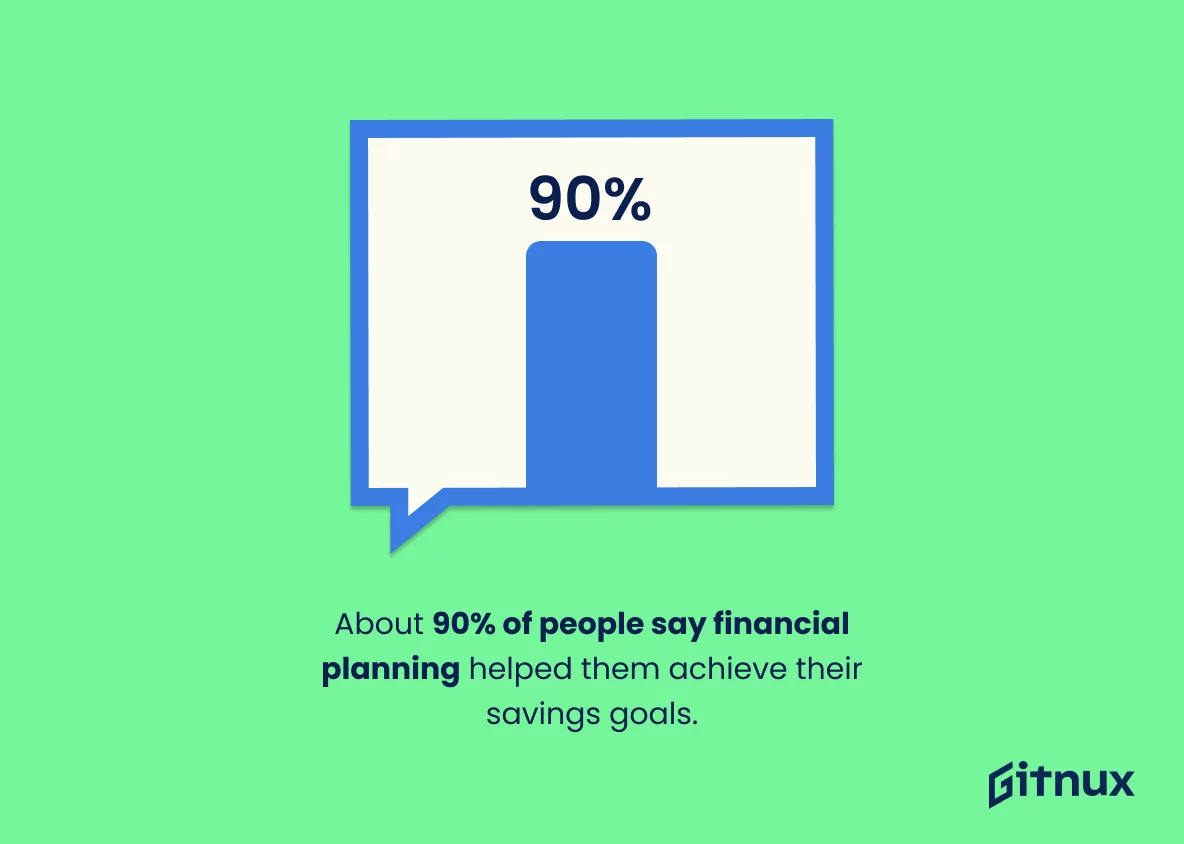
Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


Get Started on Your Financial Life Plan Today