Yes, Life Insurance Can Generate Tax Free Income For Retirement. Here Are Some Key Things You Should Know.

By
September 27, 2017
Share on:

Most of us know you can use assets in a retirement investment account or an annuity to generate income during retirement. But did you know you can use certain kinds of life insurance policies to do the same thing?

What kind of life insurance?

There are two primary types of life insurance: term and permanent. To use an analogy, think of a term policy as renting a home, and think of a permanent policy as buying a home. Similar to building equity in a home you are buying, permanent policies usually have a feature where they accumulate money inside them called Cash Value. In the same way that a mortgage payment is divided into principal (equity) and interest (the cost of the loan), the premium payment for a properly designed permanent life policy is divided into Cash Value (equity) and the cost of insurance (paying for the actual death benefit). In addition to your own money, the insurance company typically credits your policy with interest or dividends each year, so the Cash Value grows over time.

Note: There are different types of permanent policies (for example, Whole Life, Universal Life, Variable Universal Life, etc.) and they each have their plusses and minuses. Describing the differences would be lengthy and outside the scope of this article. For simplicity’s sake, I’m going to base the rest of this article on Universal Life.

So far, it sounds like an expensive savings account. What am I missing?

Using a life insurance policy to accumulate savings has some key differences from a savings account at your bank. First, the life policy offers tax deferred growth. In a bank savings account, you must report the interest you earn every year and pay income tax on it. The Cash Value in a life policy gets to grow tax deferred, just like in a qualified retirement account. Without having to pay taxes along the way, your money grows faster.

Second, the interest rate that an insurance company pays is typically much higher than the interest rate that a bank will pay on a savings account. For example, at the time of this article, the national average interest rate on a bank savings account is 0.06%1, whereas universal life policies typically average around 3%-5%.2

The biggest difference between Cash Value and a bank savings account has to do with taking the money out. With a bank account, you can only take out the dollars that are there, but there is a way to take money out of a life policy that is leveraged3.

OK, how do I get the money out?

Although the insurance company would allow you to simply withdraw the cash value, that option has a big drawback. The amount of gain in the policy (the current cash value minus the dollars you contributed along the way) would be taxed at ordinary income tax rates. There is a better option.

Insurance companies offer a way to borrow against the cash value in your policy. The proceeds from the loan are tax-free. It is important to note that you are borrowing against the cash value, not from the cash value. That means your entire cash value balance continues to earn interest. Contrast that with any other type of account, where when you withdraw money, the only portion of your money that continues to earn is the money remaining in the account.

Just as with most loans, you must pay interest on the amount you borrow. The life insurance company will typically charge 4%-5% interest. However, the cash value continues to earn 3%-5% interest, so your net cost for the loan might only be 0%-1%. No other vehicle I know of allows you to do this!

But when I’m retired, isn’t taking out a loan a bad idea?

Typically, we want to reduce our fixed expenses during retirement. And typically, adding a fixed loan payment to our retirement budget would indeed be a bad idea. However, taking a loan from your life policy doesn’t add any payments to your budgets. None. In fact, the insurance company doesn’t even expect you to repay this loan during your lifetime. At your death, the loan will be paid off from a portion of the death benefit, while the remainder will go to your beneficiaries. In a well-designed policy, your death benefit will grow over time. This should allow you to borrow tax-free income every year during retirement, pay off the loan when you die, and still have a sizeable death benefit remaining for your beneficiaries.

One small but important caution

What makes this entire strategy possible is the way life insurance proceeds are taxed. Loans taken against the policy are not taxed, nor is the death benefit taxed when received by your beneficiaries. If you take out too much money from the policy and don’t leave enough inside to pay the continuing cost of the policy, the policy will lapse (meaning the insurance company will cancel the policy). If that happens while you are still alive, then the IRS wipes out all of the tax benefits, and all that money you took out becomes taxable. That is a tax bill you want to avoid at all costs.

How do I add this strategy to my retirement plan?

Designing a policy correctly requires experience and advanced training. Many agents who only sell policies and don’t do financial planning may not be properly trained in the intricacies of this strategy. Make sure you get your policy from a reputable advisor who fully understands this strategy, and who can show you how it fits into the rest of your financial plan. This is not the kind of policy you want to buy over the internet or from an 800 number!

https://www.valuepenguin.com/banking/average-bank-interest-rates

Kelly, Patrick. (2007). Tax-Free Retirement

Dictionary.com defines leverage as “the use of a small initial investment, credit, or borrowed funds to gain a very high return in relation to one's investment, to control a much larger investment, or to reduce one's own liability for any loss.” http://www.dictionary.com/browse/leverage
You may also like:

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


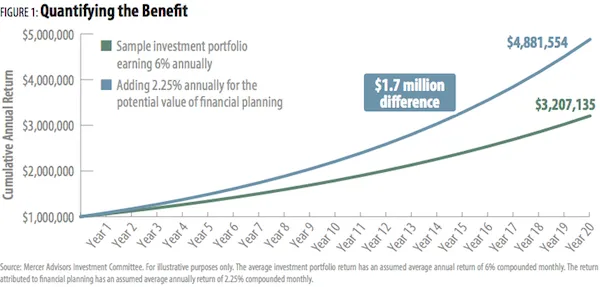
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


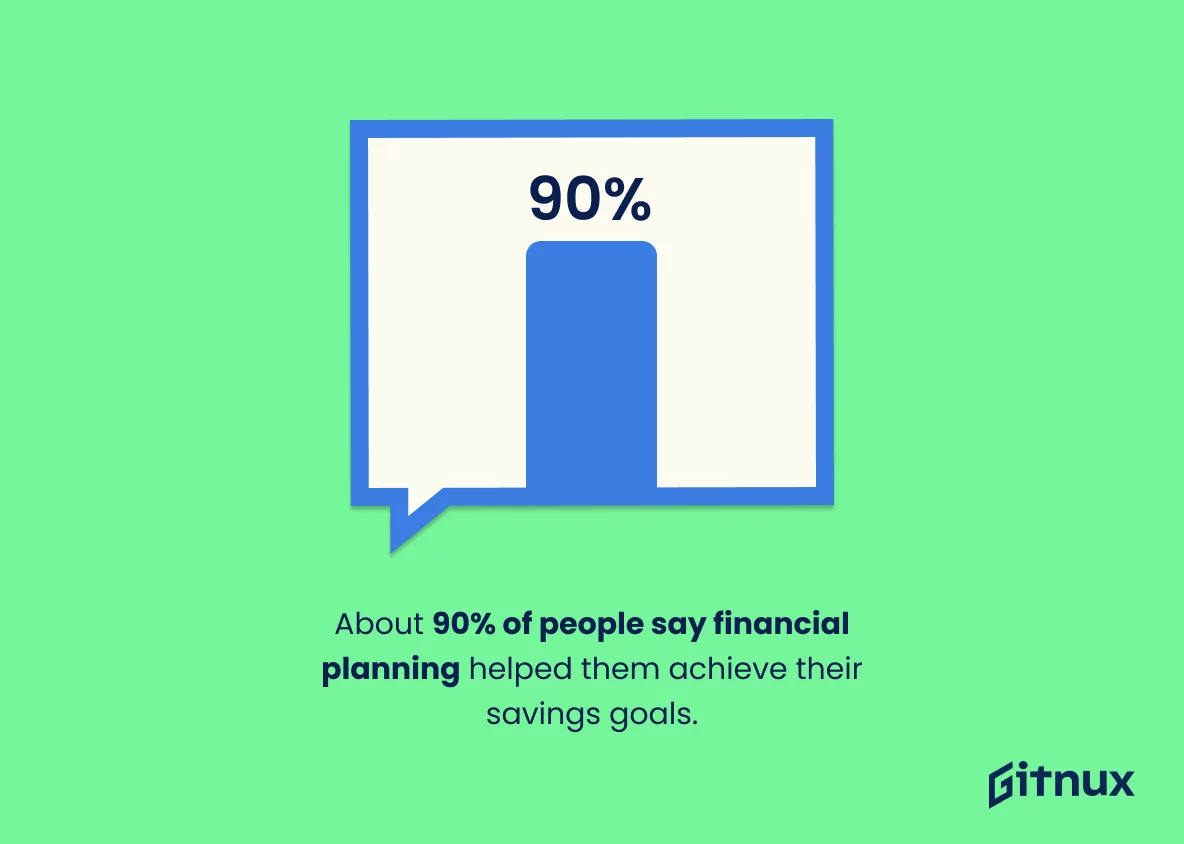
Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


By Trilogy Financial
November 2, 2017

The day you become a parent is a day of overwhelming emotions. You may experience joy at the sight of your precious child, relief that he or she made it out of the womb, and for many of you, fear and anxiety because you somehow have to turn that seven-pound baby into an independent, responsible, and successful adult.

As parents, there are so many things we have to teach our children, beginning with the basics of how to eat and share toys to more complicated lessons such as making decisions and getting along with others. As a society, we are excelling in some areas of parenting, but falling behind in others. In a recent National Financial Capabilities Study, only 24 percent of Millennials (age 23-35) were able to answer the first three financial literacy questions correctly, and a mere 8 percent answered them all correctly.[1]

Most parents agree that we need to do a better job teaching our kids about money. Last year, T Rowe Price reported that 80 percent of parents didn’t think schools were doing enough to teach kids about financial matters.[2]However, parents cannot abdicate all responsibility to the schools. Raising children and teaching them to navigate the world is first and foremost a parent’s responsibility.

Set A Good Financial Example

The first step in teaching your kids about finances is modeling what you want them to learn. Few parents would disagree with this concept. The same T Rowe Price study mentioned above found that 69 percent of parents are very/extremely concerned about setting a good financial example for their kids. The vast majority, eight out of ten, feel that they are setting a good financial example, but two-thirds also admit to doing things that wouldn’t qualify as setting a good example.

An enormous 40 percent admitted that when it comes to talking to their kids about finances, it’s “Do as I say, not as I do.” Anyone who has raised kids knows that isn’t enough. My clients tell me they are very concerned about setting a good example for their children. The first step in teaching your kids about money is simple: Show them.

Talk About Finances

Sometimes a silent model isn’t quite enough, and some areas of personal finance aren’t very visible. That is why it is imperative to talk to your kids about finances. But talking about money may be a long-standing cultural taboo. Often this reluctance to discuss financial matters spills over into the home as well.

Forty-nine percent of the parents in the T Rowe Price study said they rarely or never discuss family finances with their children. Eighteen percent admitted to being very/extremely reluctant to discuss financial matters with their kids and 72 percent of parents experience at least some reluctance to having such a discussion. But how are kids going to learn about money if you avoid talking to them about it?  Some topics require more in-depth discussion and openness and finances are one of them.

Get Your Kids Involved

If you want financial understanding to actually sink in, you need to get your kids involved. Learning theory and research have consistently shown that the more active a learning experience is, the greater the learning gains and retention.[3] Most people have to do something to truly learn it.

How does this work with kids? Here are some ways I’ve put this into practice with my daughter: Even though she is young, I have taught her the difference between a penny, nickel, dime and quarter. Beyond just teaching the values of the coins, I then show her how to earn money by completing basic, age-appropriate chores such as making her bed and folding her clothes. As her coins start adding up, she has the opportunity to buy a toy or to save her money and earn interest (a penny for every dollar). Just as any adult, she loves the idea of making money for no extra work, so she often chooses the savings option!

At this point, I take a step back and let my daughter make her own financial decisions (and sometimes mistakes) so that she can learn from them. She and I have different values and I’ve learned that I need to let her be independent and respect her choices. On one occasion, she decided to impulsively purchase a My Little Pony beanie baby that I thought would be a waste of money. Rather than refusing to buy the toy for her, I took a step back and allowed her to buy it with her own money. Sometimes I am surprised in the process, as she still plays with this toy three months later!

Imparting financial wisdom to your kids is a challenging process that takes years. So, if you don’t feel like you’re doing an adequate job of teaching your kids about money, you’re not alone. Even if you are doing a good job, you probably agree with the 77 percent of the T Rowe Price survey parents who said that they wished there were more resources available to help them teach their kids about financial matters.

I believe that every child can learn critical financial lessons at a young age that will set them up for future success. I want to provide you with the tools to help you on this journey. To set up a meeting, call my office at (949) 221-8105 x 2128, or email me at mike.loo@trilogyfs.com.

[1] http://gflec.org/wp-content/uploads/2015/01/a738b9_b453bb8368e248f1bc546bb257ad0d2e.pdf

[2] https://corporate.troweprice.com/Money-Confident-Kids/images/emk/2015-PKM-Report-2015-FINAL.pdf

[3] http://www.joe.org/joe/1994august/a6.php

Get Started on Your Financial Life Plan Today