

Woburn Financial Advisors Reveal Strategies for Maximizing Your Investments

By Trilogy Financial
June 26, 2024
Share on:

Introducing Financial Advisor Woburn


In Woburn, Massachusetts, financial advisors at Trilogy Financial Services, such as Tom Elkins, Dale Sarpard, and Mohammed Siddiqui, are guiding clients towards financial success with personalized investment strategies. Leveraging their collective expertise and local market understanding, these advisors offer unique insights into maximizing investments.


Understanding the Woburn Investment Landscape


The economic landscape of Woburn offers diverse investment opportunities. Advisors like Tom Elkins, an Accredited Investment Fiduciary, emphasize the importance of understanding local market trends and how they can impact investment choices. With their finger on the pulse of Woburn's economy, these advisors tailor their strategies to leverage local strengths. Some of these Key Strategies and Insights from Trilogy Financial Advisors include:

  • Collaborative Strategy: Emphasizing a team-based approach, Trilogy Financial ensures clients benefit from diverse expertise and financial planning woburn.
  • Comprehensive Solutions: By pooling the knowledge of various advisors, the firm can offer more holistic financial plans.
  • Enhanced Understanding: This approach leads to a deeper comprehension of each client’s unique financial situation.
  • Complex Situation Management: The collaborative effort of the team allows for effective management of intricate financial scenarios.


Tailored Investment Strategies


Each investor's journey is distinct, and advisors at Trilogy Financial Services recognize this. Dale Sarpard, with his extensive experience, illustrates the importance of creating investment plans that align with individual goals and life stages. From retirement planning to wealth management, their strategies are as unique as their clients.
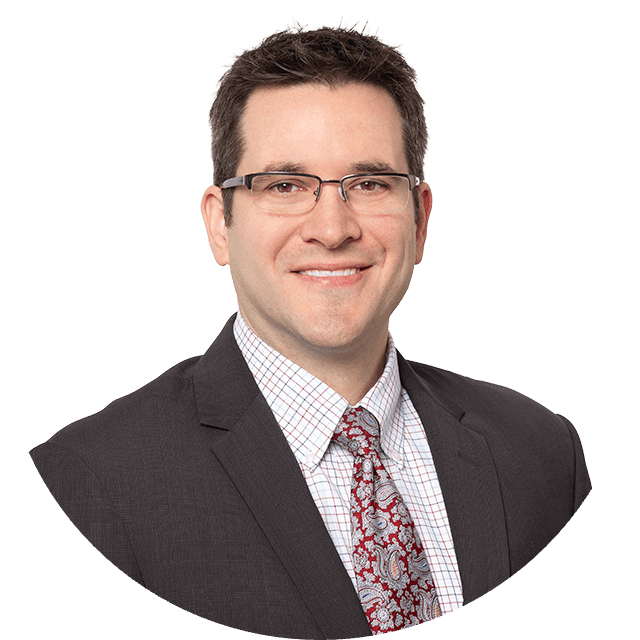
 

Tom Elkins' Approach:

  • Emphasis on understanding local market trends for informed investment decisions.
  • Advocacy for personalized financial planning tailored to individual goals.
  • Specialization in retirement planning and wealth management strategies.


Risk Management Techniques


Effective risk management is a cornerstone of successful investing. Mohammed Siddiqui, known for his client-focused approach, underscores the significance of a well-diversified portfolio. By balancing risk and return, these advisors help clients navigate market volatility with confidence.
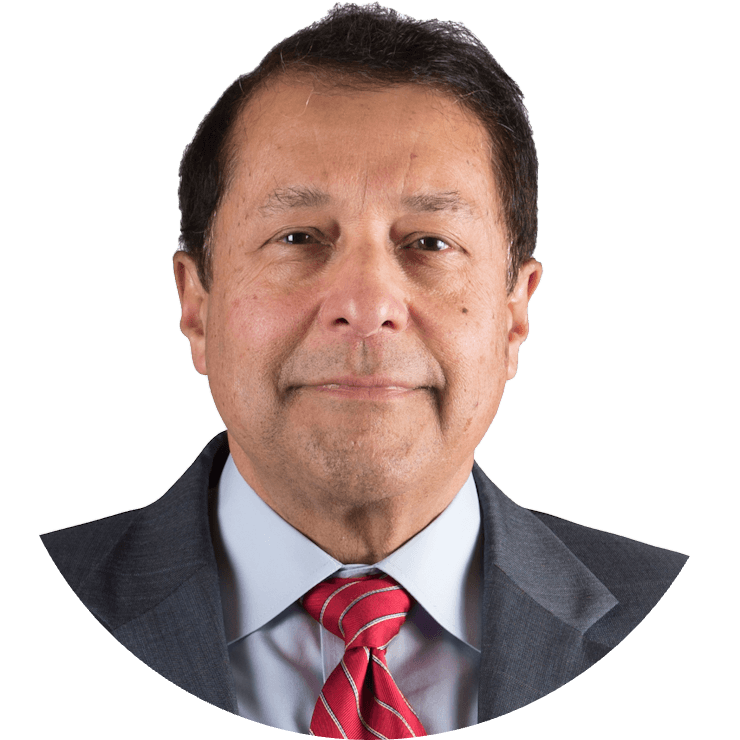
 

Mohammed Siddiqui's Methodology:

  • Prioritizing client-focused risk management and portfolio diversification.
  • Adapting investment plans to changing market conditions and personal life changes.
  • Utilizing technology for real-time investment insights and efficient planning.


Future-Proofing Your Investments


Woburn's financial advisors are adept at adapting investment strategies to evolving market conditions and personal circumstances. They prioritize long-term sustainability, ensuring that clients' investments can withstand economic shifts and personal life changes.
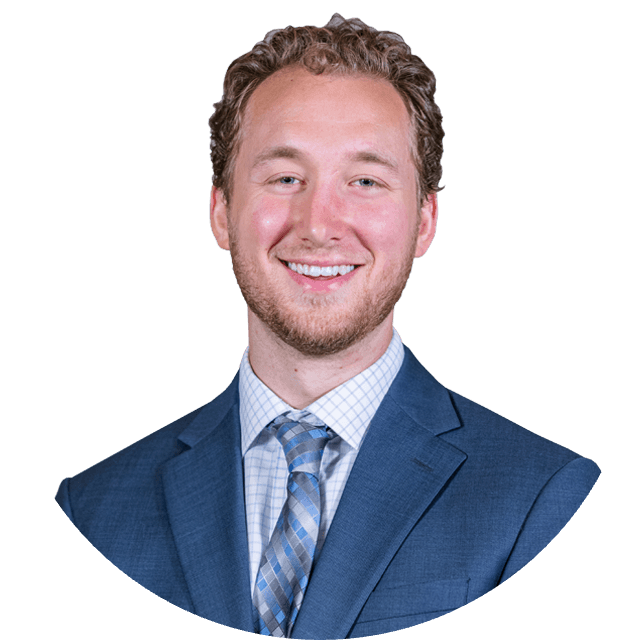
 

Dale Sarpard's Expertise:

  • Extensive experience in developing comprehensive financial plans.
  • Focus on aligning investment strategies with life stage and financial objectives.
  • Expertise in navigating complex financial scenarios for diverse client profiles.


Leveraging Technology for Investment Success


In today's digital age, technology plays a crucial role in investment management. Trilogy Financial Services utilizes advanced tools and platforms to provide clients with real-time insights and streamlined financial planning processes.


Conclusion

The advisors at Trilogy Financial Services in Woburn are committed to guiding clients through the complexities of investing. With personalized strategies, expert risk management, and sophisticated technology, they are equipped to help you achieve your financial goals. For those seeking to maximize their investments, consulting with these local experts is an invaluable step towards financial prosperity.


Ready to Amplify Your Wealth today?


If you're ready to elevate your financial planning with our professional team, we invite you to schedule a meeting with us. At Trilogy Financial Services, our advisors in Woburn are dedicated to crafting personalized financial strategies that align with your unique goals. Don't wait to start your journey towards financial success:

Schedule a Meeting: Reach out to us to arrange a one-on-one consultation with our financial professionals.

Give Us a Call: Prefer a quick conversation? Feel free to give us a call to discuss your financial needs and how we can assist. Call Us To Get Started. (844) 356-4934

Schedule a No-Strings-Attached Portfolio Review today and embark on a path to financial success guided by professional advisors. For more information and to schedule your consultation, visit www.trilogyfs.com/yourmoneyamplified. With the right knowledge and professional guidance, the journey of investing becomes an exciting venture towards achieving financial security and growth. This way, you're not just dreaming of an ideal retirement but actively working towards making it a reality.


*There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.


You may also like:

By
Jeff Motske, CFP®
March 19, 2018

Do you remember Veruca Salt, the spoiled rich girl from the movie Willy Wonka and the Chocolate Factory? You know, the girl who yells at her father, “I want it now!” And her clueless, abiding father would get her whatever she wanted, which consequently did more harm than good.

Well, we all have one of those fathers. Not the one that we buy a Father’s Day card for every year, but one that we carry in our wallet. One that typically says yes to whatever we want to buy, regardless of how that may spoil our budget, or worse, our credit score. It’s called a credit card.

Please understand, I am not calling you spoiled or demanding. However, in this instantaneous age, it’s very easy to spend impulsively or unconsciously. How many of us have gone to Target to purchase one or two items and ended up walking out with a full cart? How many of us have passed some idle time perusing one of our favorite online vendors, one who may even have our credit card information stored in their system? We may have had no intention to buy when we got on the site, but when we spot a good “deal,” it only takes a few quick clicks to make it ours.

You see, it happens a lot more often than you think. Study after study has shown that people will spend more money when they use credit cards than when they use cash, sometimes as much as twice the average cost for the same item1. Not only does the method of payment affect the quantity, it can also affect quality, with consumers willing to purchase unhealthy or unnecessary items when paying with a credit card as opposed to cash2.

The convenience of clicking or swiping to purchase, rather than handing over tangible cash, has spurred on overspending and racked up national credit card debt to $905 billion3. The truth of the matter is that we have lost sight of the fact that credit cards are essentially a thirty-day loan, which is becoming more and more apparent with the younger generations. Based on Experian’s Millennial Credit and Finance Survey Report Part II, 58 percent of millennial credit card holders polled in 2015 had maxed out a credit card, been charged a late fee, had an increase in the interest rate on a credit card, had a credit card declined or had defaulted on a credit card payment4. Financial behaviors like these can wreak a lot of havoc on a young person’s credit score and financial future. Such a small, seemingly innocent looking piece of plastic can do a lot of damage.

Now I am in no way advocating a credit-free lifestyle. Not only are credit cards a convenient way to build up your credit score, but many cards offer rewards programs where users can earn discounts, airline mileage and cash back. Most importantly, though, there are an increasing amount of vendors that no longer accept cash. This is not simply limited to online purchases. Have you ever tried leaving an airport parking lot or paying to access a toll road with cash? In most places, it is nearly impossible.

What I am saying is we need to start being a bit more mindful with our money, a bit more critical of how we spend. I mentioned the perks of credit cards rewards programs earlier. How many of us, though, have actually stopped to determine how much those perks really cost once you start adding up interest and impulse purchases? If switching over to cash purchases helps us become a bit more mindful with our money, then so be it.

Before you end up with a pile of debt and regret.

1. https://www.nerdwallet.com/blog/credit-cards/credit-cards-make-you-spend-more/

2. https://www.psychologytoday.com/blog/the-science-behind-behavior/201607/does-it-matter-whether-you-pay-cash-or-credit-card

3. https://www.nerdwallet.com/blog/average-credit-card-debt-household/

4. https://www.slideshare.net/Experian_US/experian-millennial-credit-finance-survey-report-part-ii

By
Mike Loo, MBA
March 1, 2018

Over the course of working with so many individuals and families, I’ve found that many people think financial planning, investing, and retirement planning are a sprint to the finish line. While on paper, maxing out your 401(k) each year and building an all-stock portfolio for maximum growth potential seems like a good plan, fast and big investing can actually slow down your progress to your goals. Let’s look at why.

The Dangers of Little Liquidity I always enjoy working with enthusiastic young couples who want to do everything in their power to reach their desired retirement. However, in the process of focusing on their long-term retirement goals, they neglect their short-term needs.

For many of my clients in their 20s and 30s, I may recommend contributing enough to their 401(k) to get the employer match, if one is offered, and contribute some of their paycheck to build an emergency fund and savings. This can help them avoid focusing so much on their long-term retirement goals that they neglect their short-term goals, from buying a house to paying off student loan debt. I generally recommend that my clients build a reserve fund that can cover three to six months’ worth of living expenses.

Dipping Your Toes In Versus Diving Head First

I said it earlier but I’ll say it again; investing and financial planning is a marathon, not a sprint. I’d much rather be the tortoise—slow yet steady and consistent—than the hare—fast yet unpredictable—when it comes to my investing strategy.

One of the more underrated strategies for financial security is making consistent and periodic contributions to your portfolio over a long period of time. As I mentioned earlier, younger individuals and families may not have the income yet to max out their 401(k), but they can make consistent contributions and increase them over time as their income increases. Like the tortoise, saving for retirement and other long-term goals is all about perseverance and consistency, even if it is at a slower pace.

It’s easy to let emotions get in the way, and many investors fall prey to the newest investment strategy that claims a higher return on investment. But the fact of the matter is, there is no controlling or predicting the market. I tell my clients that instead of focusing on what they can’t control, it’s helpful to focus on what they can control: the capital they invest.

Whether the markets are high or low, consistent contributions can have a powerful long-term effect. Additionally, maintaining a well-diversified portfolio and rebalancing if needed each year can help ensure your portfolio matches the appropriate level of risk you’re willing to take. Adhering to this motto and disciplined strategy can help you avoid the common trap investors fall into: buying high and selling low, and chasing high returns.

The Risks of Aggressive Investing

Too often, financial advisors tell young individuals in their 20s and 30s to keep close to 100% of their portfolio in stocks. The theory is that young investors have decades to ride out volatility and make up for any lost returns. While this may work for some individuals, I’ve had a number of younger clients who don’t feel comfortable taking such risks, even if they have decades to try to make up for losses.

Investing entirely in stocks isn’t necessarily the way to go, even if it makes sense on paper. It’s nearly impossible to entirely remove emotions from investing. Too often, I’ve seen investors give up when their portfolio takes a big hit. They lose motivation to keep investing, and they struggle to keep their eyes on the finish line of their long-term goals.

Incorporating investments, like bonds, that offer lower returns and lower risk, may help you feel more confident in your portfolio and avoid the rollercoaster of emotions if your portfolio takes a hit during a downturn.

Next Steps

Like the tortoise and the hare, fast investments don’t mean you’ll reach the finish line first. While it can be difficult, it’s important to tune out the noise of the media and focus instead on what strategies make sense for your unique situation, risk tolerance, and short and long-term goals. While not as exciting, I believe slow and steady can win the race, and without as many speed bumps along the way.

As an independent financial advisor, my mission is to make a meaningful impact on the lives of my clients and the people they love. I help families make informed decisions with their money and pursue a strong financial future. If you’re interested in learning more about balancing your short and long-term goals, I encourage you to reach out to me. Call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com.

Get Started on Your Financial Life Plan Today