

TSA PreCheck Scams

By
December 20, 2021
Share on:

TSA PreCheck Scams


TSA PreCheck is garnering a lot of interest, from both travelers and scammers alike. In addition to pocketing your renewal/application fee, these scammers take your personal information to sell on the dark web or create false identities that can be used illegally. TSA PreCheck scam emails are quite sophisticated, lacking many of the typical red flags such as misspellings, grammatical errors, and slightly-off-looking versions of TSA logos. We recommend that you continue to check the email address and web address of the sender, as well as how they’re asking for payment.

Always verify that the TSA PreCheck web and email address ends in ‘.gov’ – not ‘.com’, ‘.org’ or anything else. If they don’t, these are not official TSA PreCheck communications and you should not provide personal information or payment information. Additionally, don’t purchase or renew a TSA PreCheck membership by clicking on a link you were sent via an email. Instead, go directly to the TSA or Homeland Security website.

The other major red flag comes when it’s time to pay for your renewal or application fees. While there are multiple ways to make a payment for government services, scammers typically only give you the option of using PayPal. If you get an email and suspect it’s a scam, or end up clicking on a bad link yourself, TSA says to do the following:

  1. Report the fraud to your local Police Department.
  2. File a report with the Federal Trade Commission website.
  3. Contact your credit card company or bank and let them know about any fraudulent charges.

In the event that your credit card information ended up in the wrong hands, you will need to work through your bank or credit card company. TSA specifically states on its website that it “will not issue a reimbursement to applicants who attempt to enroll in TSA pre-check through a fraudulent website.”
You may also like:

By
June Adams
May 10, 2022

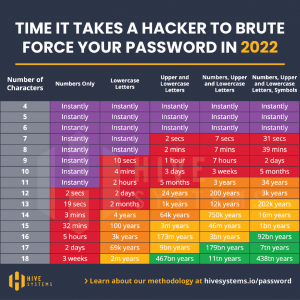
How long do you think it would take a hacker to crack your current passwords?

On average, it takes a hacker about 2 seconds to crack an 11-character password that only uses numbers. See the attached chart that illustrates the time it takes for a hacker to brute force attack your password. A brute force attack is when cybercriminals use trial and error to guess your details. Cybercriminals currently use sophisticated software that can run thousands of password combinations in a minute, but their technology and resources are only getting stronger.

A general rule is that your password should be at least 11 characters, utilizing both numbers as well as upper and lowercase letters. That combination will take hackers 41 years to crack. Regardless of the possible variations, the shorter your password, the easier it is to crack. Check out how long it will take a hacker to crack your password at https://www.security.org/how-secure-is-my-password/.

Lastly, simplify and secure your accounts by using a password manager that creates and stores all your passwords for you.

Strengthen your password security with the following tips:

  • Prioritize the length and complexity of your passwords.
  • Don't use personal information. This can be publicly available and easily accessible by hackers.
  • Avoid using dictionary words as passwords. Cracking tools can easily process every word in the dictionary.
  • Don't reuse passwords. If one account is breached, your other accounts would be vulnerable as well. Rather, use password managers, which are a convenient and secure way to manage complex passwords on multiple platforms.
  • Use multifactor authentication (MFA or 2FA) for especially sensitive accounts.
  • Avoid typing passwords while using public Wi-Fi. Instead, use a VPN or avoid websites that require your login information.


By
David McDonough
September 23, 2019

People are living longer – that’s a fact. Unfortunately, all those additional years aren’t always spent in optimum health. With longevity comes the complicated question of how to pay for the necessary health care for those additional years. Costs for unexpected and long-term chronic care are rarely covered by Medicare. People are having to face these costs on their own. Thankfully, the right type of planning can make this task less daunting.

Long-term care can be an overwhelming topic. The statistics are sobering. 52% of people turning age 65 will need some type of long-term care services in their lifetimes, and 14% will need long-term care for longer than five years. With the median annual cost of adult day care averaging $18,200 and assisted living facilities at $45,000, the financial implications can be staggering. It can sound like a complicated topic, but the way to protect you really boils down to three options.

  • Self-insure: This is the option that many select by default because they don’t want to think about the possibility of illness creeping into their future. It’s a scary option, which they hope won’t happen to them. However, this option typically leaves them unprepared for the medical costs that eventually do occur.
  • Long-term Care Policy: This is a good form of financial protection as it covers your risk but won’t wreck your financial plan. However, the down side with such a policy is that if you don’t use it, you lose it.
  • Accelerated Benefit Riders (ABR’s): Lastly, you can invest in life insurance you don’t have to die to use. These riders in your insurance plan will allow you to receive your benefits prior to death due to terminal, chronic or critical illness. The ABR’s will cover your risk, and you’ll still receive the benefit if you don’t need to use it for long-term care purposes.

Now, there is no one-size-fits-all solution. It’s always best to meet with your trusted financial advisor to find the right option for you. Just know that when you do take the time to plan ahead and find the right option for your particular situation, you’re not only providing for your future but also your peace of mind as well.

[i] https://www.morningstar.com/articles/879494/75-must-know-statistics-about-long-term-care-2018-edition

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Get Started on Your Financial Life Plan Today
