Navigating the Golden Years: Smart Retirement Options

By Trilogy Financial
February 26, 2024
Share on:

In the era of self-directed retirement planning, the need for individualized strategies and informed decisions has never been more pronounced. As you tread into the realm of retirement, engaging with experienced retirement planners becomes crucial to ensure a secure and joyful post-career life. However, the realm of investing can be complex, and making informed decisions is vital for financial success.

If you are looking to make well-informed investment decisions, consider speaking with a financial advisor at Trilogy Financial Services. With the help of qualified professionals, you can navigate the financial complexities that may be hindering your wealth amplifying journey.

Through this expedition, we recommend reaching out to the Financial Planners at Trilogy Financial Services to help guide you through the fog of financial decision. They can help you navigate resources such as the “dont worry retire happy pdf” documents or the more simplified “Retirement for Dummies” documents you might find on the internet when looking for solutions.


Understanding Taxes and Retirement

Let's take a moment to talk about retirement.. It's not merely a phase of life; it's a significant transition that requires meticulous planning and foresight. One of the critical aspects to consider is how might taxes have an impact on your financial plan. A comprehensive understanding of tax implications is essential for effective wealth management, especially when it comes to safeguarding your nest egg from potential tax liabilities.


Wealth Management Strategies

Engaging in astute tax and wealth management strategies is paramount in preserving and growing your retirement corpus. By exploring various tax-advantaged retirement accounts and consulting with professional tax advisors, you can better prepare for the tax implications that come with retirement. This proactive approach not only keeps your financial plan on track but also paves the way for a more secure retirement.


Smart Retirement Options

As you delve deeper into the retirement planning process, exploring smart retirement options becomes a priority. These options could range from choosing the right retirement accounts, investing in tax-efficient funds, to exploring annuity products that provide a steady income stream. The aim is to build a robust financial portfolio that aligns with your retirement goals while minimizing tax liabilities, thereby ensuring your savings not only last but grow throughout your retirement.


Real-world Case Studies

  • Transitioning into Retirement: Curt from De Pere, WI, started strategizing for his retirement alongside his wife after lengthy careers in public service, with the assistance of a Financial Planner.
  • Early Retirement Evaluation: Stephen and Nicole evaluated an early retirement package to manage taxes efficiently during their transition into retirement.
  • Career Change and Retirement Planning: Susan and Chris transitioned from high-profile music industry jobs to retirement, achieving their goals with the aid of First Wealth.
  • Long-term Savings Strategy: Jim and Cathy’s story illustrates the importance of long-term savings and debt management, having saved $750,000 in a 401(k) and $300,000 in savings over their working years.


The Bright Side of Retirement

Planning for retirement isn't solely about numbers and finances; it's also about envisioning a happy, fulfilling life post-retirement. Infusing humor and a positive outlook towards this life-altering phase can make the journey enjoyable. A funny, happy retirement is indeed a product of sound financial planning paired with an optimistic outlook.


Key Retirement Statistics

  • Gender Disparity: Only 17% of women feel on track to meet their financial goals compared to 26% of men.
  • Retirement Account Investments: Americans had invested $6.8 trillion in 401(k)s and $12.5 trillion in IRAs as of the first quarter of 2023.


Professional Insights

Professional insights add another layer of credibility to the smart retirement planning narrative. Jim Barnash, a Certified Financial Planner with over four decades of experience, emphasizes the importance of meticulous retirement planning. Understanding complex financial concepts such as the ‘Sequence of Returns Risk' is also crucial as per experts' advice. Moreover, strategic moves endorsed by financial experts can significantly enhance the possibility of retiring as a millionaire, as discussed in a recent piece on Nasdaq.


Planning for the Unexpected

To further aid in your retirement planning, establishing an emergency fund is advisable. An emergency fund serves as a financial buffer, ensuring you have the resources to cover unexpected costs. Having three to six months' worth of living expenses in your emergency fund, which can be adjusted based on your unique financial situation and risk tolerance, is a common goal provided by financial planners.


Leveraging Modern Technology

Lastly, as the digital age continues to evolve, leveraging modern technologies can also play a significant role in your retirement planning process. With the aid of new tools, you can access personalized financial advice, explore various retirement scenarios, and receive insights that empower you to make informed decisions towards a secure and happy retirement. These tools can aid in personalizing your retirement planning process, offering insights and scenarios for better financial decision-making. We recommend speaking to a Financial Planner for a full rundown.


Conclusion

Smart retirement planning is a multi-faceted endeavor that demands a blend of financial acumen, forward-thinking, and a zest for life. By embracing a holistic approach towards retirement planning, you not only pursue your financial future but also set the stage for a joyful and fulfilling retirement. The journey towards a secure retirement begins with the right financial planning, educating oneself on the financial landscape, and making informed decisions that align with your values and retirement goals.

Instead of spending years mastering finances on your own, partnering with those who have already traversed the financial landscape can fast-track your financial success. A dedicated financial advisor from Trilogy Financial Services can work with you to make your money work smarter and harder, simplifying the financial intricacies that have been keeping you up at night.

You can schedule a no-strings-attached portfolio review today and embark on a path to financial success guided by professional advisors. For more information and to schedule your consultation, visit www.trilogyfs.com/yourmoneyamplified. With the right knowledge and professional guidance, the journey of investing becomes an exciting venture towards achieving financial security and growth. This way, you're not just dreaming of an ideal retirement but actively working towards making it a reality.


*There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.
You may also like:

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
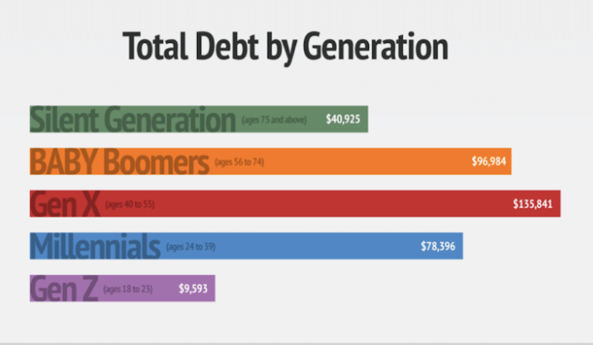
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


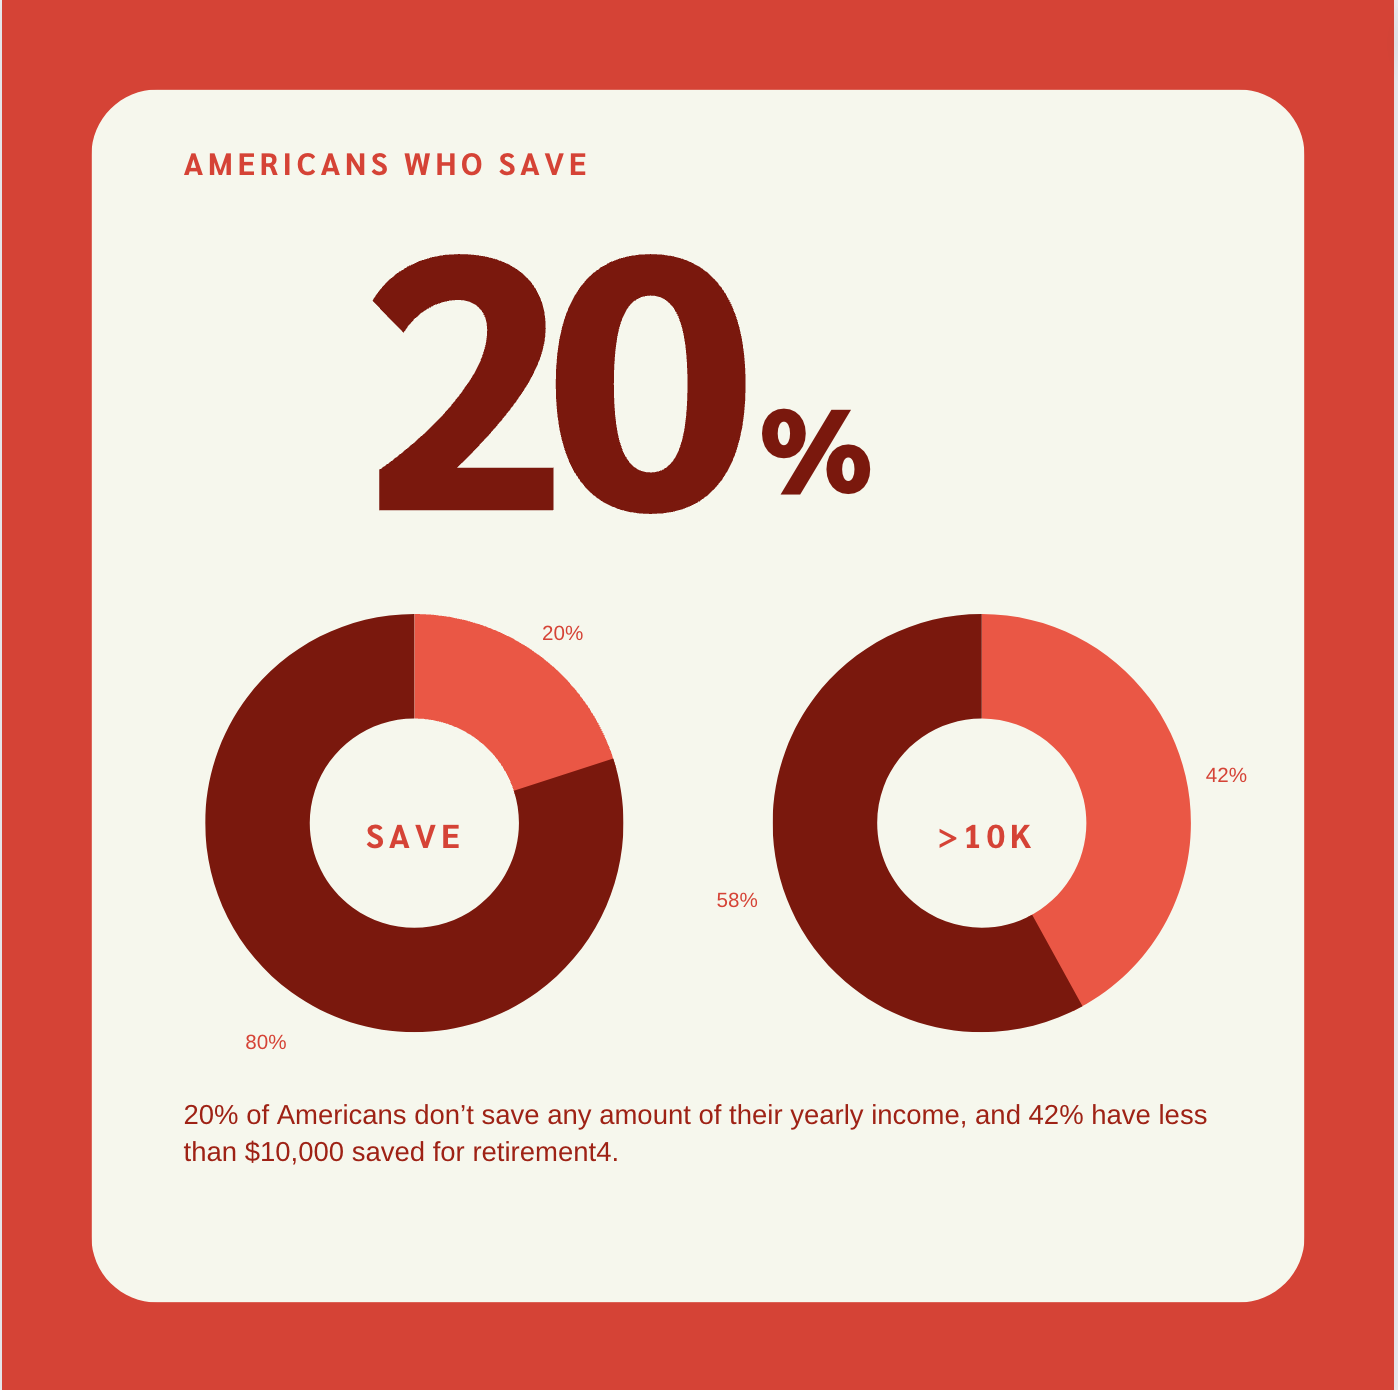
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


By
Mike Loo, MBA
July 20, 2018

Over the course of hundreds of conversations with clients, I’ve found that quite a few them have wrestled with the idea of whether they should go back to school for an advanced degree. As their advisor, I am commonly asked if returning to school would be financially beneficial. The risk/return analysis is not always cut-and-dried in this situation. Investing X amount of dollars in a degree program does not always result in an equal or higher return in the future.

The True Value Of Education

Education is about more than just the money. After a recent conversation with a client, I had the realization that while I don’t need an MBA for my job as a financial advisor, the MBA experience itself shaped and molded me to become the advisor I am today. While I did take numerous finance classes to enhance my knowledge and quantitative skills, the greatest value I gained from earning an MBA came from improving qualitative skills, such as working with people, networking, effective communication, and time management. These are skills that I use daily in my current role.

Every experience we go through, especially those that push us out of our comfort zone and require plenty of work and time, leads to personal growth. Had I not gone through the MBA program at USC’s Marshall School of Business, I might not have developed the work ethic required to succeed as a financial advisor, and I could have ended up on a completely different career path altogether.

My Pre-MBA Self

Before entering the MBA program, I had a passion for the financial services industry, but like most college grads, I wasn’t sure how that would translate into a career. I didn’t have a clear direction for my future. I was interested in becoming an advisor but knew that it would be fairly tough to advise people on what to do with their finances when I hadn’t gone through many life experiences myself.

I had always loved the idea of making money and becoming more efficient with what I had, but I was young and dumb (and willing to admit that)! I fell into the cultural mindset of wanting to work typical business hours, earn a large salary, and enjoy life. In essence, I wanted the rewards but didn’t want to do the work involved to achieve those rewards. In my naive way of thinking, an MBA seemed to be the simplest path to achieve this end result. I can tell you that I was so wrong in this assumption!

What I Gained from My MBA

Networking Skills: USC is known for networking. Everything I heard about business school prior to attending was that the most important takeaway from the experience is to network, network, network. Unfortunately, my pre-MBA self was uncomfortable talking with people I didn’t know. I didn’t like to take the initiative to introduce myself and sometimes avoided conversing with people unless I was introduced first. As time went on and I experienced the pressure of competing against my peers and other highly qualified candidates for the same jobs, I was forced to rise to the challenge and become comfortable with being uncomfortable.

This skill alone has helped me immensely in my career when it comes to collaborating with a client’s other professionals, such as an estate attorney or CPA. In order to do a thorough job for a client, it’s often necessary to work with their other professionals to make sure we’re on the same page. In many cases, I’ve reached out to a client’s CPA to make sure they had my contact information so that if questions arise about the client’s investments, they call me rather than my client.

This skill has also helped me in reaching out to client referrals or prospective clients because I’ve found that people often want help with their financial planning, but they might not tell others or take the first step.

Effective Time And Task Management: During my time at USC, multitasking became the norm. If I wanted to effectively balance school, attend recruiting events, revise my resume, participate in mock job interviews, network for potential jobs, and somehow find time for a personal life, I had to become better with time management.

My job today is multi-faceted and includes juggling many tasks, such as answering client questions, servicing and monitoring their accounts, staying on top of changes in the industry, and dealing with changes life throws my clients’ way. Knowing that I was able to handle my heavy load in the past gives me confidence that I can prioritize my work today. Most importantly, I’ve come to realize that with all of these moving parts, it’s impossible to be rigid in only working business hours (again, something I aspired to when I was young and dumb), because not everyone is available from 8 am to 5 pm. Instead, I’ve become flexible with my schedule and instituted taking a day off during the week so that I can occasionally meet with clients on the weekend or do a phone call later in the evenings.

Is An Advanced Degree Right For You?

In my case, obtaining an advanced degree was one of my best decisions. It’s difficult to imagine doing anything else with my life and I am fortunate that I went down this path. If you or someone you know is trying to make this decision, I would love to give you some insight and help you look at the situation from an objective perspective. Or, if you would like to network and see if we could work together, call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com. I’d love to see you thriving in your life!

Get Started on Your Financial Life Plan Today