Key Questions to Discuss with Your Estate Planner

By Trilogy Financial
March 8, 2023
Share on:

Estate planning is an essential step to help protect the wealth that you've spent your life building. Meeting with an estate planner will help to create a comprehensive plan that will allow your assets to effectively pass to your assigned beneficiaries. Creating this initial plan can feel overwhelming, and we are here to help you prepare.

Here are five important questions you can expect to discuss with your estate advisor as you start to plan for your future.

How Would You Like Your Wealth to Pass to Your Heirs or Elsewhere?

The basis of your estate plan is where you want to direct your wealth and how you'd like that to happen. No matter how large or small your estate is, you'll need to decide how it should be distributed among children, grandchildren, other family members or favorite charity organizations. For example, this could mean leaving different parties a percentage of your total assets, or leaving one child your business and another child your vacation home.

It’s important to also think about whether you want your beneficiaries to receive their inheritance all at once or not. If you have a disabled child requiring lifelong care on your list, or someone who needs a little extra help managing their money, you may want a trust or annuity structure in place to pay out the inheritance in increments.

What Can Be Done to Prevent Costs and Conflicts for Your Heirs?

Costs for your beneficiaries are most likely to come up if your estate needs to go through probate, which is the process by which a court distributes your assets. In addition to financial costs, there are other reasons to avoid probate. Probate can be a long and exhausting process – meaning, your heirs will not be able to access your estate right away. If you have dependents who will rely on the money in your estate, this can be an especially serious concern. In addition, probate adds your estate information to the public record, which you may want to avoid. There are several strategies your financial advisor might recommend to avoid probate. These include placing assets in a trust and moving funds into joint accounts with your beneficiaries.

Conflict among heirs is another common concern, especially in families where conflict already exists. While the legal documents included in your estate should help minimize disagreements and make it more difficult for someone to contest your wishes, communication during your lifetime is important as well. Disagreements often surround specific items like jewelry or sentimental pieces rather than your financial assets. Labeling these items, writing a letter of instruction and starting to pass on these things during your lifetime can all help make your intentions clear.

How Can You Reduce Your Tax Burden?

After a lifetime of working to earn your money, you likely want to direct your wealth to your loved ones rather than the government. In 2023, only estates valued at $12.92 million (or $25.84 million for some married couples) or more may be subject to the federal estate tax. If, upon your death, the total value of your estate is less than the applicable exclusion amount, no federal estate taxes will be due.

Depending on the state you live in, your heirs or your estate might also be subject to state estate or inheritance taxes. If taxes are a concern for your estate, there are several ways to reduce your tax burden.

One simple option is to start passing money along during your lifetime. Based on the 2022 gift tax exemption limit, individuals can give up to $16,000 per recipient per year. This lets you give money directly to your children or grandchildren while reducing the value of your estate, which will reduce your tax bill. Other options include a marital trust, which allows one spouse to place assets in trust for the other spouse, and an irrevocable life insurance trust, which can pay for life insurance premiums with tax-deductible funds and then avoid estate taxes later on.

Are You Already Working with Financial Professionals?

If you're already working with an estate attorney, a financial planner or a tax professional, it's important for your estate planner to understand the strategies your existing financial team has recommended. You'll want to make sure that all of these members of your team are working together so you aren't paying for duplicated efforts or conflicting suggestions.

If you aren't already working with a financial team, your estate planner may recommend that you do so depending on the details of your estate plan. If you have complex tax concerns, you might need to talk to a tax expert. Depending on the type of trust that you wish to establish, you may need an estate attorney to set it up.

How Will Changes in Your Life Change Your Estate Plan?

Your estate plan should have the flexibility to adapt to changes in your lifestyle, family structure or life expectancy. Your initial plan will be based on your current circumstances, but you should consider potential future concerns and possible solutions.

Divorce and Remarriage

Divorce and remarriage are common life changes that can affect your estate plan. If you remarry, you may not want your new spouse to manage the inheritance of your children from the first marriage. This can create the need for a new trust to be established. In addition, if you have more children in later marriages, you will again need to update your estate plan.

Life Expectancy and Medical Issues

There are other lifestyle considerations that might change as well. For example, if based on your family history you expect to live into your 90s, you might not want to start giving away assets to avoid estate taxes. And if medical issues arise and your life expectancy changes, you will likely need to adjust your plan.

While you won't need to make any decisions based on hypotheticals, it's a good idea to discuss the possibilities.

How to Get Started?

Your estate plan is a key component of your Life Plan. To create an estate plan that addresses the above questions and any other concerns you may have, you'll need to start by finding the right estate advisor. Talk to the Trilogy Financial team to take control of your finances today while maximizing your future opportunities.

Download your free Estate Strategies eBook to learn how to protect your estate.
 

family happy after meeting with estate planner
family happy with estate planning and secure future


You may also like:

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


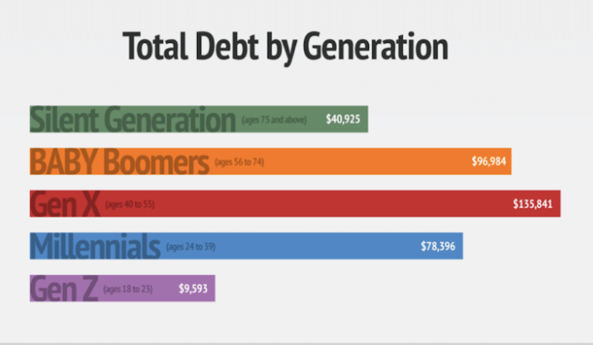
  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


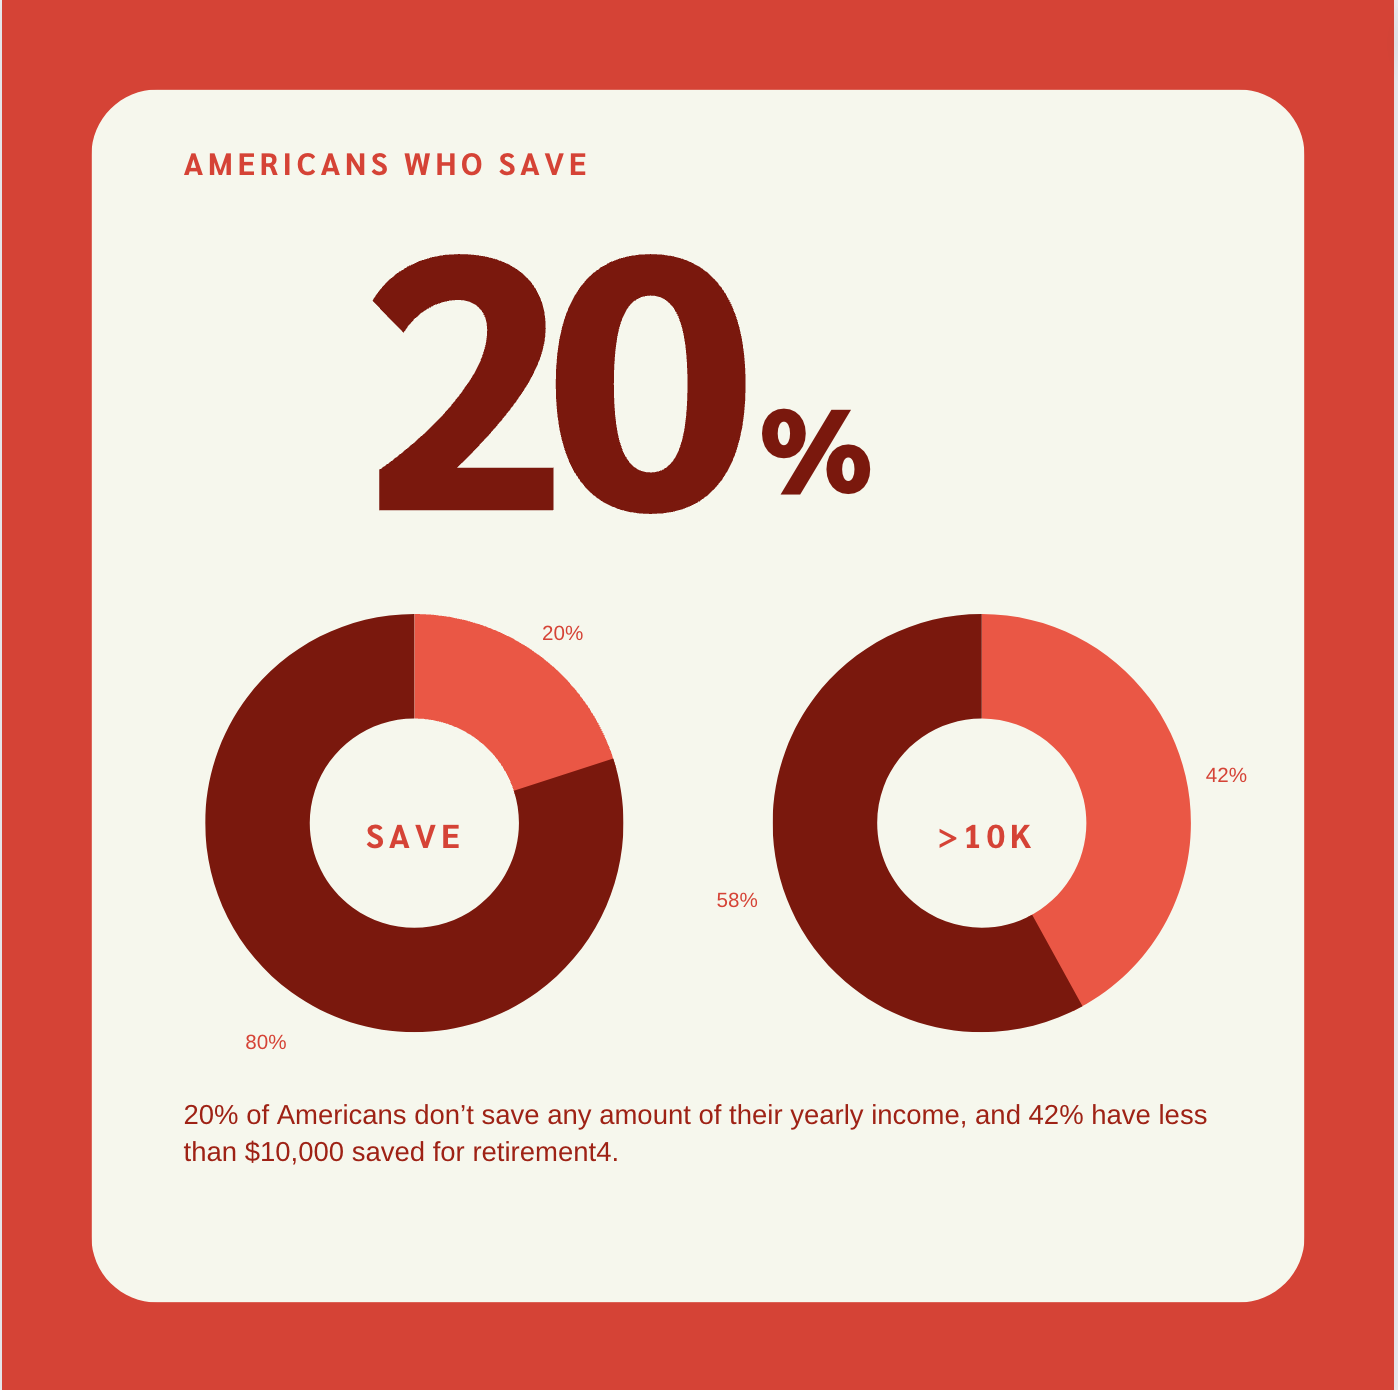
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


By
Jeff Motske, CFP®
October 15, 2018

Often, my clients ask me, “How will I know if I’m ready to retire?” It sounds like a simple question, but the answer is anything but. There are so many factors to consider, questions to answer, scenarios to prepare for, that it can all seem very overwhelming. To make things manageable, though, let’s start off with a dream.

We know that retirement can be expensive. In fact, according to a survey conducted by the Wall Street Journal, participants would need 130% of their salary in retirement to live their ideal retirement life.1 You see, most of us spend money during our free time, and as one of my advisors says, retirement is basically six Saturday’s and a Sunday. If your retirement is filled with lazy days reading in your backyard, your expenses will probably be limited. However, if you plan on traveling, tackling home improvement projects or long-ignored hobbies, all of these come with additional expenses. Additionally, things you may have been able to earn in relation to your job, such as airfare and hotel points for frequent travelers, are no longer as easily accessible once you turn off your wage-earner card.

Therefore, the first step on your checklist is to visualize your retirement. If you’re not sure where to start, simply look at what you do in your current free time and determine if that’s something you would like to do more of when you retire. Not only does this help in your financial planning, but it helps you determine what you want the next chapter of your life to be. It is unfortunately common for retirees to experience depression related to a lack of purpose or identity when they enter retirement with an undeveloped vision of their next chapter. Therefore, the more details you can determine, the better the planning process will go.

For people who are married, things become a bit more multi-faceted to plan. You’re not only figuring out how to occupy your free time, but your spouse is also doing the same, and the two of you need to figure out how you plan to spend your shared time together. Without this planned out, you end up with a lot of togetherness, which can be quite an adjustment to most couples. Not only can differences in your retirement vision impact your relationship, but it can also impact your finances. Take advantage of monthly financial date nights well before retirement begins and solidify your retirement vision.

Perhaps you’ve finalized that retirement vision and discovered you won’t have a lot of expenses. You will most likely have those expenses for a long time though. People live much longer now, on average into their mid-eighties.2 It would be great to assume that those years will be spent in good health, but the likelihood is that your medical expenses will go up. According to the Fidelity Retiree Health Care Cost Estimate, the average couple will need about $280,000 for medical expenses in retirement.3 Even if you stay away from long-term care needs or expensive treatments, annual premiums and out of pocket costs like doctor visits and medications typically cost about $5,000 annually.4 There may be certain elements you may not be able to foresee, but you should still try to plan for as much as possible.

Once you’ve determined what your vision for retirement is, you need to determine how much you’ll need to live that lifestyle. You need to be sure that the income you’ll be receiving will fund that vision. Just to be sure, once that number is determined, try living on that budget for about six months. If you find out that you’re struggling, some adjustments will need to be made, whether that’s working longer or altering the retirement vision. Practicing your retirement lifestyle isn’t merely relegated to your budget. If you typically work 50 to 60 hours a week, start cutting back. Maybe take on fewer projects. Prepare as much as you can for this life adjustment. You’ve worked really hard to get to retirement. Be sure to put in the extra work to make it the retirement of your dreams. Retirement is a massive decision. I urge you not to take it lightly. There is a reason that the five years before and after retirement are considered dangerous. Certain things like pensions, pay-outs and in some cases, social security can’t be undone. The best way to make an informed decision on what’s best for you is to meet with an Advisor who can run the scenarios for you. If you choose to push retirement off, your investments can continue to grow. In the end, you will be putting the proper steps in place to make your retirement dream a reality.

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

  1. https://www.wsj.com/articles/how-much-money-will-you-really-spend-in-retirement-probably-a-lot-more-than-you-think-1536026820
  2. https://www.fidelity.com/viewpoints/personal-finance/plan-for-rising-health-care-costs

Get Started on Your Financial Life Plan Today