

Investing 101: Best Investment Blogs for Beginners

By Trilogy Financial
February 20, 2024
Share on:

Discover how working with a financial planner can make a big difference in your investing journey. Learn about investing through our beginner's guide to top investment blogs.


For many, investing seems like a daunting venture. Navigating through the intricacies of the financial world can be overwhelming, especially when you're just starting out. But beyond the stock market fluctuations and intricate charts, it's essential to grasp your financial aspirations.


Warren Buffett wisely said, “Don't save what is left after spending, but spend what is left after saving.” This highlights the importance of financial planning and goal setting when it comes to investing.


As emphasized by Jeff Motske, CFP® at Trilogy Financial Services,  understanding your financial “why” is just as pivotal. Are you eyeing retirement? Or maybe that dream home or a new startup? These goals should shape your long term investment journey.

To help beginners transition into the investment realm, here's a two-fold strategy:


1. Consult a Financial Planner or Advisor


Engaging with a financial planner or advisor is akin to having a personalized coach for your financial journey. Just as you wouldn't start an intense workout regimen without gauging your physical limits, investing without a clear vision of your financial goals and investment decisions is risky.


A financial planner will assist in evaluating your risk tolerance—an essential element in devising an investment strategy. As Peter Lynch, a renowned investor, once remarked, “Know what you own, and know why you own it.” This stresses how important it is to be informed and understand one's investments.


Financial Advisor Meeting with Client


2. Discover the Top Investment Blog Posts for Beginners


In Personal Finance, staying on top of your investment portfolio starts with understanding continuous learning is a key ally in the world of investments. Here are some top investment blogs for beginner investors that can offer invaluable insights:


  • Investopedia: A comprehensive platform offering a plethora of articles, tutorials, and educational content on finance and investment.
  • The Motley Fool: A trusted source renowned for its stock recommendations and investment advice, catering to both novices and seasoned investors.
  • Seeking Alpha: A blend of free and premium content, providing in-depth research, articles, and analyses on various stocks and investment strategies.
  • BiggerPockets: The go-to resource for real estate investment enthusiasts, packed with guides, resources, and community discussions.
  • NerdWallet's Investing Section: Simplifies complex investment topics, making them digestible for beginners.
  • Nasdaq News + Insights: Get insights from a big stock exchange. Covers market trends, stock market news & analysis, and investment strategies.
  • Morningstar: This blog is a trusted source for investment research. It provides analysis, ratings, and information on stocks, mutual funds, and ETFs. This makes it important for both new and experienced investors.
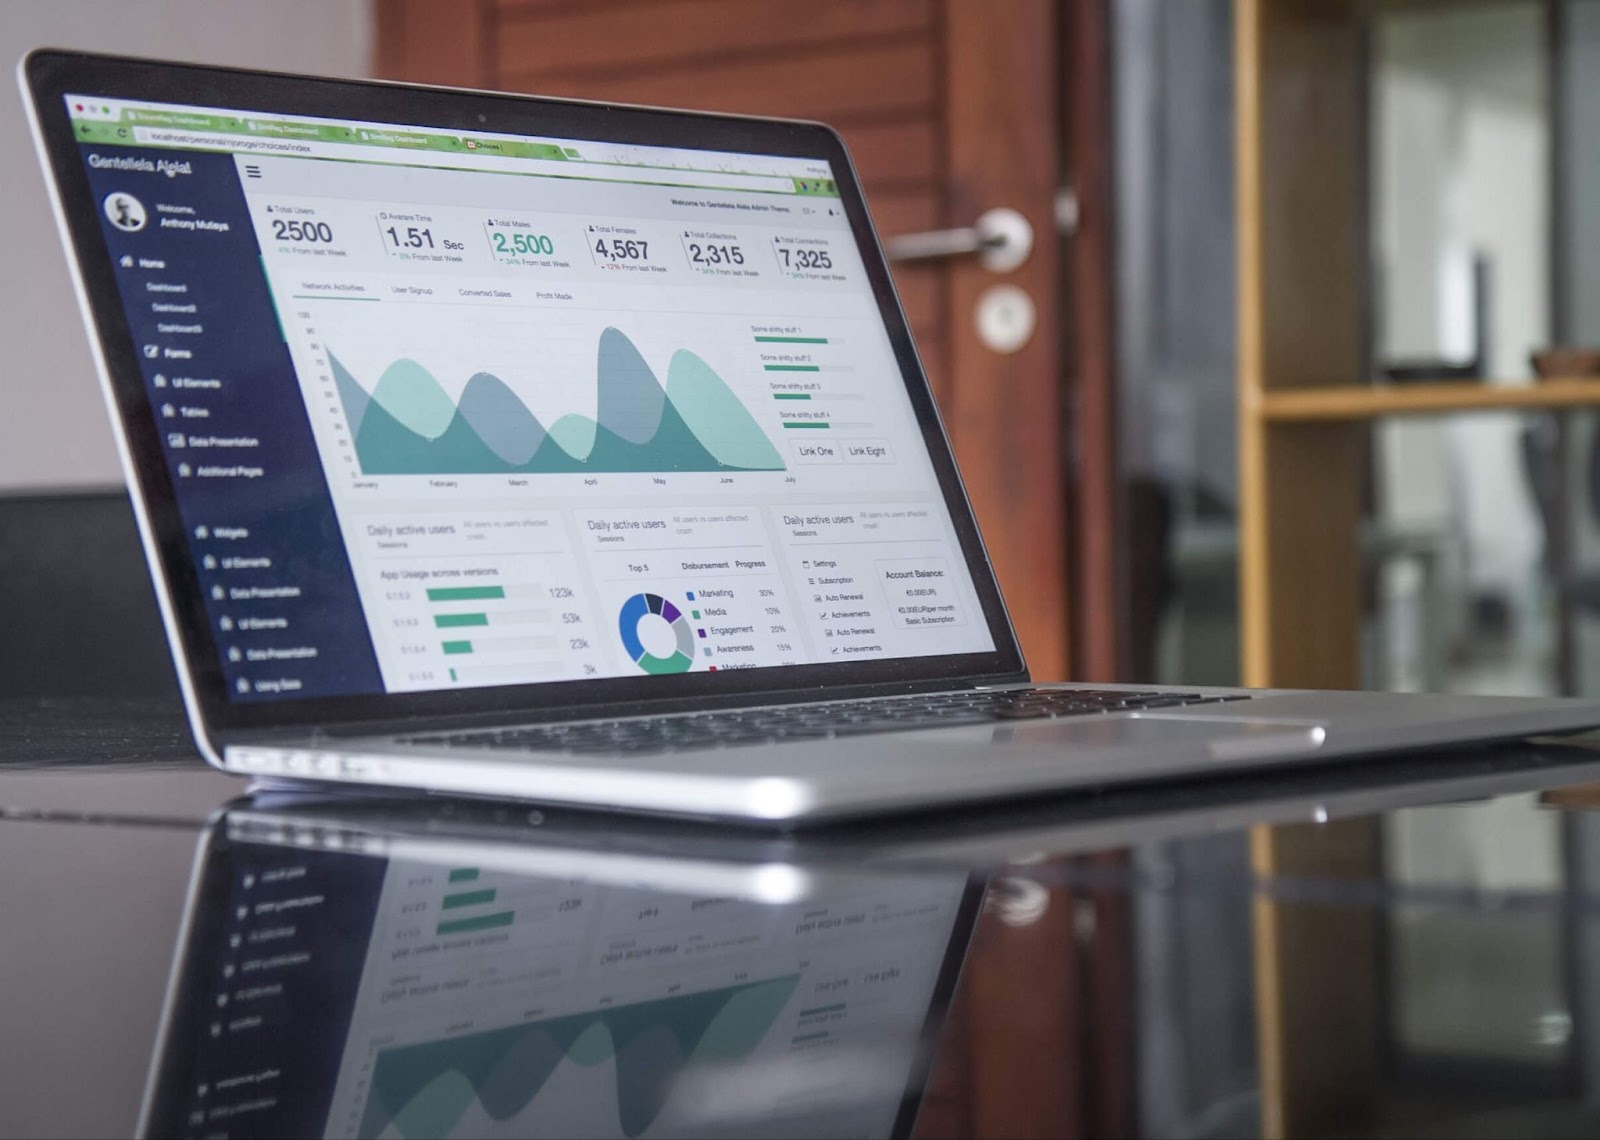


A picture of a beginner investment blog.


Conclusion


Stepping into the investment arena can evoke a mix of emotions. But as you start investing with a clear understanding of your financial goals, expert advice, and regular insights from top investment blogs for beginners, you're on a solid path.


As Benjamin Graham, known as the “father of value investing,” once said, “The individual investor should act consistently as an investor and not as a speculator.”


At the end of the day it's important to ensure you make informed, strategic investing over impulsive decisions. Check out how to avoid Mistakes When Choosing a Financial Planner in our other blog post.


Keen on diving deeper into investing? Connect with our top financial planners or explore more articles on our investment blogs for investment strategies.


You may also like:

By
David McDonough
May 31, 2019

It’s graduation season, and there’s an excitement in the air about starting a new chapter. Mixed in with this excitement is an element of stress to make the right decisions: decisions on how things should be done, when they should be done and where they should be done. All these decisions are common, but they often distract from the purpose of what comes after high school.

We need to remember that higher education has a purpose. It’s more than an experience. The purpose of a college degree is employment. It is an investment, and as with any other investment, you should be calculating the return on that investment.  Spending $100,000 for a degree that secures a job with an annual salary of $40,000 is not the best rate of return.

There are plenty of creative ways to get a great college education without breaking the bank. Parents can start a 529 plan, the earlier the better, to help cover costs. Students can begin their higher education at a community college or secure college credit via Advance Placement (AP) exams. Additionally, students need to be sure that the field they are spending their time and energy on is going to reciprocate by providing solid career opportunities.

Making the wrong decision is not simply an unwise financial move. It can have lasting implications. Recent figures show that outstanding student loan debt has reached $1.5 trillion[i]. Our younger generation is not only struggling under this debt, they are also pushing off other personal and financial milestones, such as purchasing a house[ii], getting married or starting a family[iii]. These decisions can have long-lasting and far-reaching consequences.

Lastly, let’s not forget the countless parents who put their path to financial independence on hold to financially assist their struggling children. While wanting to financially help your loved ones is admirable, it helps no one to offer assistance at the expense of your own security. Just like when traveling by airplane, you need to put your own oxygen mask on and secure your safety first before aiding others. There are no scholarships for retirement, and you won’t have a financial safety net for the future if you don’t work towards creating it now.

College is truly an exciting time. Our young adults are learning who they are, where they want to go and how they intend to get there. At the same time, we cannot forget that college is a fleeting moment, one that is meant to arm the student with the tools needed to create a brighter and more successful future. Be sure to chat with your students to ensure that this experience does just that, rather than straddle these students with debt and stress.

[i] https://www.marketwatch.com/story/student-debt-just-hit-15-trillion-2018-05-08

[ii] https://www.businessinsider.com/student-debt-preventing-the-us-from-having-normal-housing-market-2019-5

[iii] https://www.bankrate.com/loans/student-loans/student-loans-survey-february-2019/

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Prior to investing in a 529 Plan investors should consider whether the investor's or designated beneficiary's home state offers any state tax or other state benefits such as financial aid, scholarship funds, and protection from creditors that are only available for investments in such state's qualified tuition program. Withdrawals used for qualified expenses are federally tax free. Tax treatment at the state level may vary. Please consult with your tax advisor before investing.

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Prior to investing in a 529 Plan investors should consider whether the investor's or designated beneficiary's home state offers any state tax or other state benefits such as financial aid, scholarship funds, and protection from creditors that are only available for investments in such state's qualified tuition program. Withdrawals used for qualified expenses are federally tax free. Tax treatment at the state level may vary. Please consult with your tax advisor before investing.

Disclaimer:

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Stock investing involves risk including loss of principal.

Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and bonds are subject to availability and change in price.

There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.

Investing in mutual funds involves risk, including possible loss of principal.

The principal value of a target fund is not guaranteed at any time, including at the target date. The target date is the approximate date when investors plan to start withdrawing their money.

No strategy assures success or protects against loss.

By
Jeff Motske, CFP®
March 10, 2020

It’s no surprise that I often talk about the need to have a strong, supportive financial team to pursue financial independence. These financial teams can consist of a CPA, an estate planning attorney or a real estate agent, with your trusted financial advisor acting as the general manager of your team. While each one provides a specialized level of expertise, for individuals who are married, there is another person that can make or break your route to financial independence: your spouse. Often, we underestimate the value your spouse brings to your financial house, which is why it is so important to make them the MVP of your financial team.

In order to pursue financial independence, couples must be on the same page and work together towards common goals. For many, though, that is just not the case. Nearly half of U.S. couples argue over finances.[i] These disagreements can be based on resentment over spending rather than saving. Sometimes arguments arise over differing risk tolerance. The heart of these issues lies in goal mismatch, a situation that arises when your combined goals are not aligned. When you and your spouse are not working together towards your combined financial independence, chances of reaching it are slim.

While some couples argue, others simply don’t communicate. Both people in a marriage need to be involved in their finances, agreeing on their financial goals and the steps they’re taking to get there. Being unaware of your financial household, whether it’s because only one person in the relationship is in charge of the household finances or because both parties have decided to keep separate financial lives, simply causes problems. When you don’t know what the other is doing with their money, you can’t be sure that you’re both working towards the same goals in the most effective way. Additionally, you may be setting yourself up for unfortunate complications if your partner unexpectedly passes or becomes incapacitated. Honestly, I’d rather have my clients argue than avoid discussing finances. At least they’re talking about it.

So how do you and your spouse get on the same page? You can start by taking my financial compatibility quiz. Not only will the quiz show you what areas the two of you are like-minded and what areas you need to work on, but it’ll also give you the conversation starters to mine those areas you may not see eye-to-eye on. If you need a little more guidance on what to talk about, you can check out my book, The Couple’s Guide to Financial Compatibility. Also, make sure to get some time for yourself for date night – particularly a Financial Date Night. Make the investment for a babysitter to ensure some consistent quality time where you can have open, honest discussions on big-picture issues and long-term goals. For those really tough topics, you can use a trusted Financial Advisor to help you navigate the conversation.

I am a firm believer in investing in your future. Whether you invest in a book, a babysitter or your time, these investments go a long way to ensure your marital financial health. It’s when you make sure that you’re working together with your spouse that you build a strong and sure route to your financial independence.


[i] https://nypost.com/2017/08/03/the-reasons-most-couples-argue-about-money/

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual. To determine what is appropriate for you, consult a qualified professional.

Get Started on Your Financial Life Plan Today
