How A Fiduciary Can Help You Through Financial Planning

By Trilogy Financial
November 11, 2023
Share on:

Many Americans spend more hours than they’d like managing necessary financial components of life while balancing caring for a family, performing at work and enjoying time with loved ones. Despite working hard to try to strike a perfect balance, financial planning, saving and investing can be tedious and time consuming, and maybe even daunting.

This is where a fiduciary comes in.

________

What Is a Fiduciary?

The term fiduciary is thrown around in the financial services world, but few people truly understand it.

A fiduciary is a person or organization that acts on behalf of another person or persons, and puts their clients' interests ahead of their own. A fiduciary has a duty to act in good faith and serve clients by earning trust and confidence. Being a fiduciary thus requires being bound both legally and ethically to act in the client’s best interests.

To the Financial Advisors at Trilogy Financial, it’s more than that. Yes, we believe “fiduciary” means putting clients best interest before our own. However, we take it steps further to demonstrate with evidence that our proposals are in the client’s best interest. The evidence, be it in a financial planning concept or investment strategy, is the key to being a fiduciary.

Why Is It Essential To Work With a Fiduciary?

When a fiduciary presents evidence that their proposals are in the clients best interest, it leads to confidence. That confidence leads to good financial decisions over time. As Life Planners, that is what Trilogy’s Financial Advisors are working towards.

A fiduciary's main goal is to help set clients on an upright financial track through financial behavioral coaching, accountability and to help clients develop a Life Plan. A financial advisor and fiduciary will also help you prepare for retirement by maximizing the profitability of resources directed towards saving plans, develop estate plan strategies and more.

As Advisors, we anticipate individual’s or family’s needs over time, which allows us to be a better fiduciary. We believe a true fiduciary guides clients through life’s roughest patches and toughest situations.

Let a Fiduciary Be By Your Side When Life Planning

Let’s face it…a fiduciary can help ensure your financial goals are aligned in the same direction as your ambitions. Right? Proper financial planning requires objectification of your goals through the hands of an excellent financial partner who can help you with the following.

Help you save for retirement

For many, having $1 million worth of liquid cash and a list of profitable assets by the time they retire is a dream come true. However it’s a difficult dream to work towards for many Americans. That’s where a fiduciary comes in.

The secret to getting the retirement and lifestyle you dream is preparedness and time. The earlier you begin to save, the better. Beginning early allows you to make small contributions that will accumulate to a lump sum amount over a long period. For instance, if you start saving $5,000 every year from your mid-20s, by the time you are 40 years old, you will mostly likely have crossed a quarter a million mark. Remember, you will still be young, energetic, and even determined to save more. Because compounding is so powerful, if you continue saving the same amount by the time you are 65, you could be almost at $1.5 million, more than what you had intended to save.

In contrast, if you start saving at 35, even if you double that amount to $10,000, you may stagnate at $840,000 by the time you hit retirement age. So, the earlier you begin to save, the more you will receive at retirement. But do not be deterred if you are starting later in life. With the right planning, it’s never too late to achieve your goals. A Trilogy Financial Advisor can develop strategies to compound savings through investments and other growth opportunities.

Save for education stress-free

According to Market Watch, an average American will spend over $58,464 on their child's education from primary school to the undergraduate level, doubling the UK's average spend and tripling France's. Now imagine you are the head of a typical American family with more than 3 dependents; you will need almost $200,000 for education alone.  This is a huge dent in a family's finances. Fortunately, a fiduciary can help you save for education and college. Saving about a third of your earnings for a decade with the purpose of spending it on education will take the pressure of school fees off your shoulders.

Grow your wealth

The potential of growing your total net worth is an exciting process. Our Financial Advisors help you to navigate investment opportunities and mitigate risk, serving as guides as you work to grow your investments. At Trilogy Financial, we believe investing is about more than positive returns. Growing your wealth is a tool that can help you achieve financial freedom and live the life you’ve dreamed of. A fiduciary can coach you through building out the investment portfolio that aligns with your unique goals, and empower you to make the meaningful decisions to pursue your life dreams.

Plan your estate strategy

Due to the complex nature of estate planning, estate strategies should be tailored to your unique needs. And each strategy should aim to protect and preserve your assets for future generations.

Regardless of the value of the estate, a fiduciary will help you plan for the estate by:

  • Ensuring your beneficiaries receive what you’ve planned for them after you pass
  • Planning for lifetime gifts through trust and minimization of diminishing estate taxes
  • Helping you to pass assets or a business to your younger generations
  • Identifying powers of attorney to ensure your wishes come true


Trilogy Takes a Bold Financial Approach

For us, care is at the center of everything we do as fiduciaries.. We care about each client like they’re an extension of the family. Every day, with every piece of advice, we empower our clients to live wealthy. Ready to explore the benefits of working with a fiduciary? Review Trilogy's Financial Life Planning Tool to see some of the areas of focus we’d suggest on the path to financial freedom.

Bottom Line

A fiduciary helps you make critical financial decisions that are in your best interest, for your Life Plan. Our Financial Advisors work with clients nationwide. Regardless of your location, we have an office nearby or a virtual way to connect from the comfort of your home.

Start Life Planning today.

Fiduciary investment advisory services are only offered through Trilogy Capital (TC), a Registered Investment Advisor. TC markets advisory services under the name of Trilogy Financial (TF), an affiliated but separate legal entity. TC and TF are separate entities from LPL.
You may also like:

By
June Adams
May 10, 2021

Weak passwords can compromise the best security tools and controls. With a never-ending list of applications and services that users and consumers access, people may have dozens of passwords to maintain at any given time. Often, the temptation to use familiar terms such as pet names, favorite teams or the names of children or friends can cause risk since much of those details can be discovered by a simple examination of social media.

Creating strong passwords offers greater security for minimal effort. Weak passwords can compromise the best security tools and controls. With a never-ending list of applications and services that users and consumers access, people may have dozens of passwords to maintain at any given time. Often, the temptation to use familiar terms such as pet names, favorite teams or the names of children or friends can
cause risk since much of those details can be discovered by a simple examination of social media.

Under Lock and Key
You can buy a small padlock for less than a dollar—but you should not count on it to protect anything of value. A thief could probably pick a cheap lock without much effort, or simply break it. And yet, many people use similarly flimsy passwords to “lock up” their most valuable assets, including money and confidential information. Fortunately, everyone can learn how to make and manage stronger passwords. It is an easy way to strengthen security both at work and at home.

What Makes a Password ‘Strong’?
Let’s say you need to create a new password that’s at least 12 characters long, and includes numerals, symbols, and upper- and lowercase letters. You think of a word you can remember, capitalize the first
letter, add a digit, and end with an exclamation point. The result: Strawberry1!

Unfortunately, hackers have sophisticated password-breaking tools that can easily defeat passwords based on dictionary words (like “strawberry”) and common patterns, such as capitalizing the first letter.
Increasing a password’s complexity, randomness, and length can make it more resistant to hackers’ tools. For example, an eight-character password could be guessed by an attacker in less than a day, but a 12-character password would take two weeks. A 20-character password would take 21 centuries. You can learn more about creating strong passwords in your organization’s security awareness training. Your organization may also have guidelines or a password policy in place.

Why Uniqueness Matters
Many people reuse passwords across multiple accounts, and attackers take advantage of this risky behavior. If an attacker obtains one password—even a strong one—they can often use it to access other valuable accounts.

Here is a real-life example: Ten years ago, Alice joined an online gardening forum. She also created an online payment account and used the same password. She soon forgot about the gardening forum, but someone accessed her payments account years later and stole a large sum of money.

Alice did not realize the gardening forum had been hacked, and that users’ login credentials had been
leaked online. An attacker probably tried reusing Alice’s leaked password on popular sites—and
eventually got lucky.

Guarding Your Passwords & PINS. Passwords and PINS protect sensitive data and it's critical to keep them safe. Try these best practices to stay protected.

1. Do not write them down – Many make the mistake of writing passwords on post-it notes and
leaving them in plain sight. Even if you hide your password, someone could still find it. Similarly, do
not store your login information in a file on your computer, even if you encrypt that file.
2. Do not share passwords – You cannot be sure someone else will keep your credentials safe. At
work, you could be held responsible for anything that happens when someone is logged in as you.
3. Do not save login details in your browser – Some browsers store this information in unsafe
ways, and another person could access your accounts if they get your device.
4. Use a password manager – These tools can securely store and manage your passwords and
generate strong new passwords. Some can also alert you if a password may have been
compromised.
5. Never reuse passwords – Create a unique, strong password for each account or device. This
way, a single hacked account does not endanger other accounts.
6. Create complex, long passwords – Passwords based on dictionary words, pets’ names, or other
personal information can be guessed by attackers.


By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
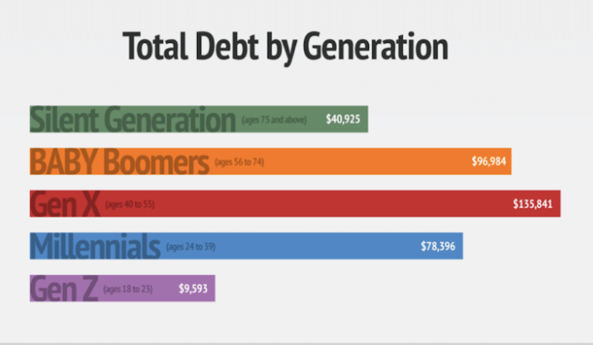
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


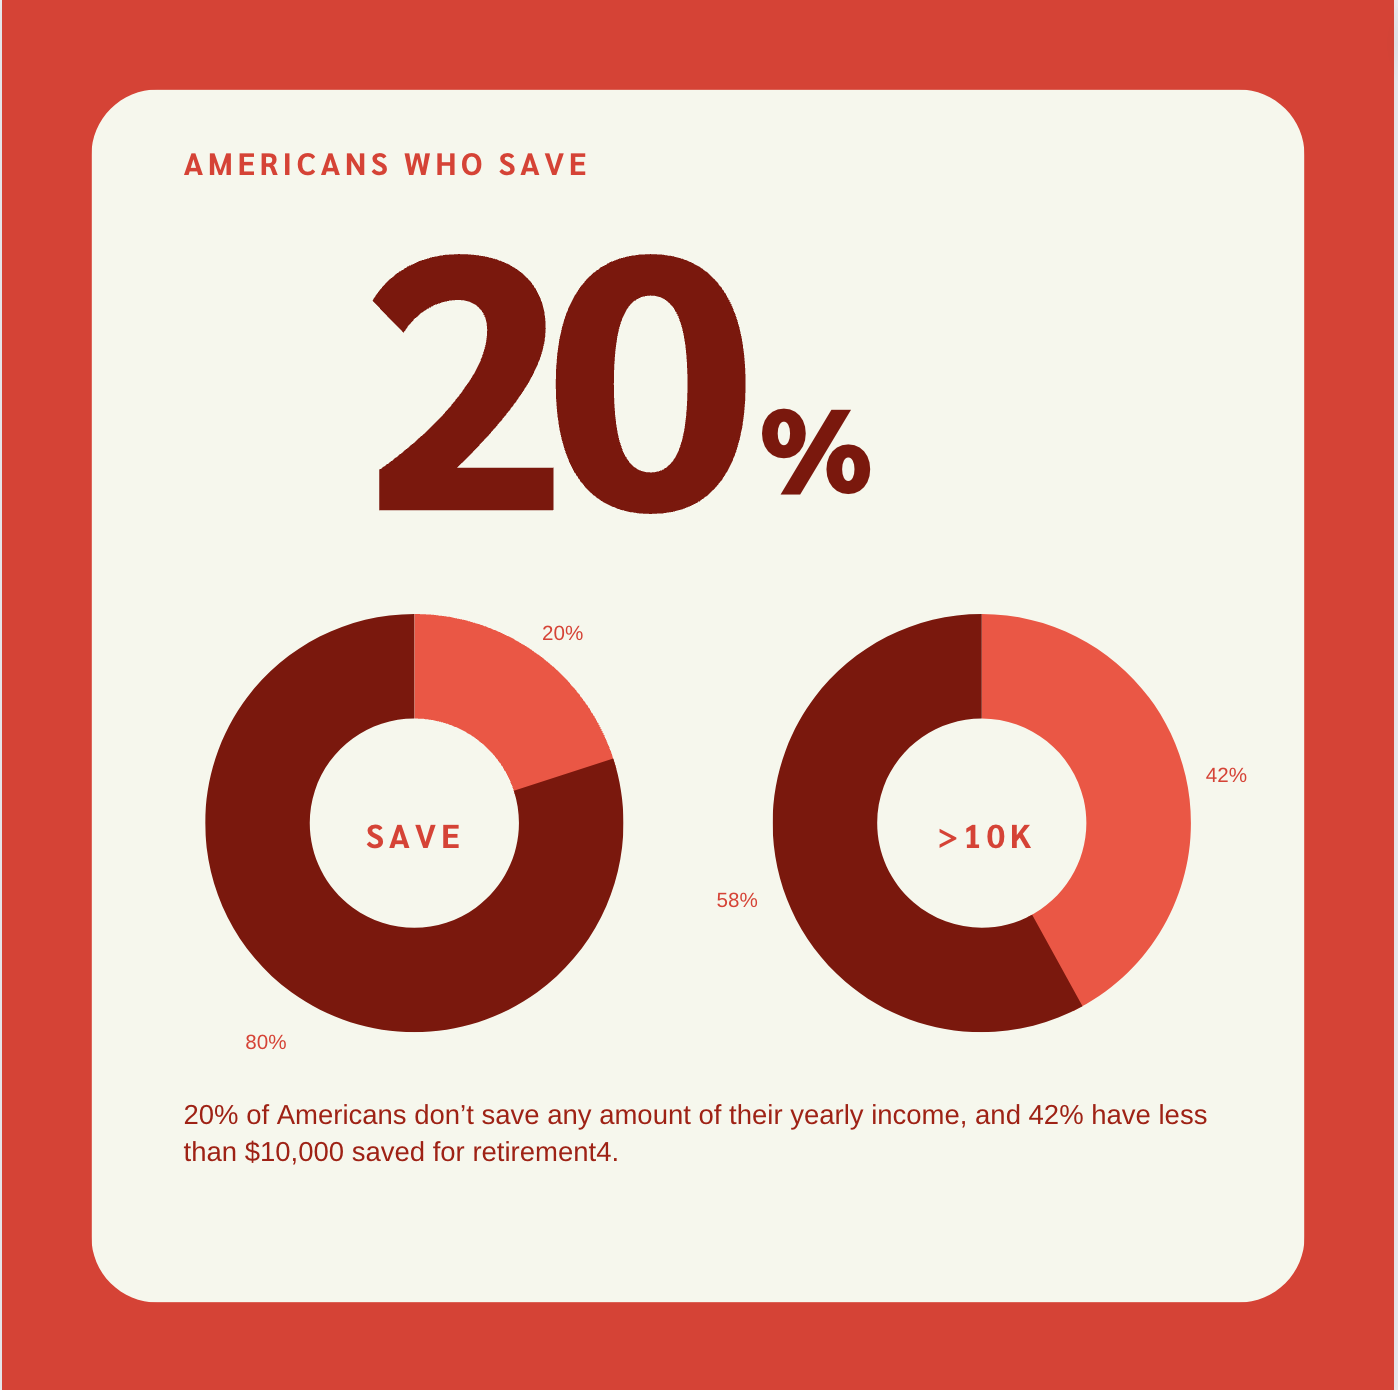
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


Get Started on Your Financial Life Plan Today