

Frugal Money Saver: The Pathway to Early Retirement Through Financial Planning

By Trilogy Financial
February 20, 2024
Share on:

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
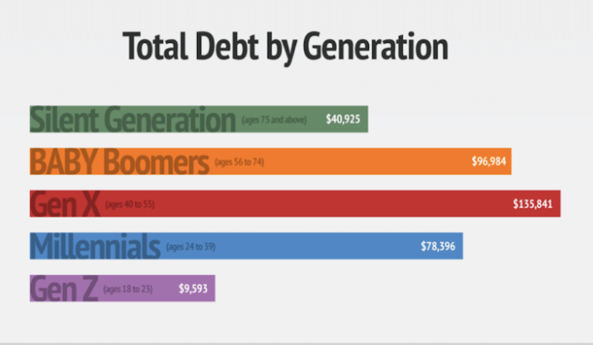
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.
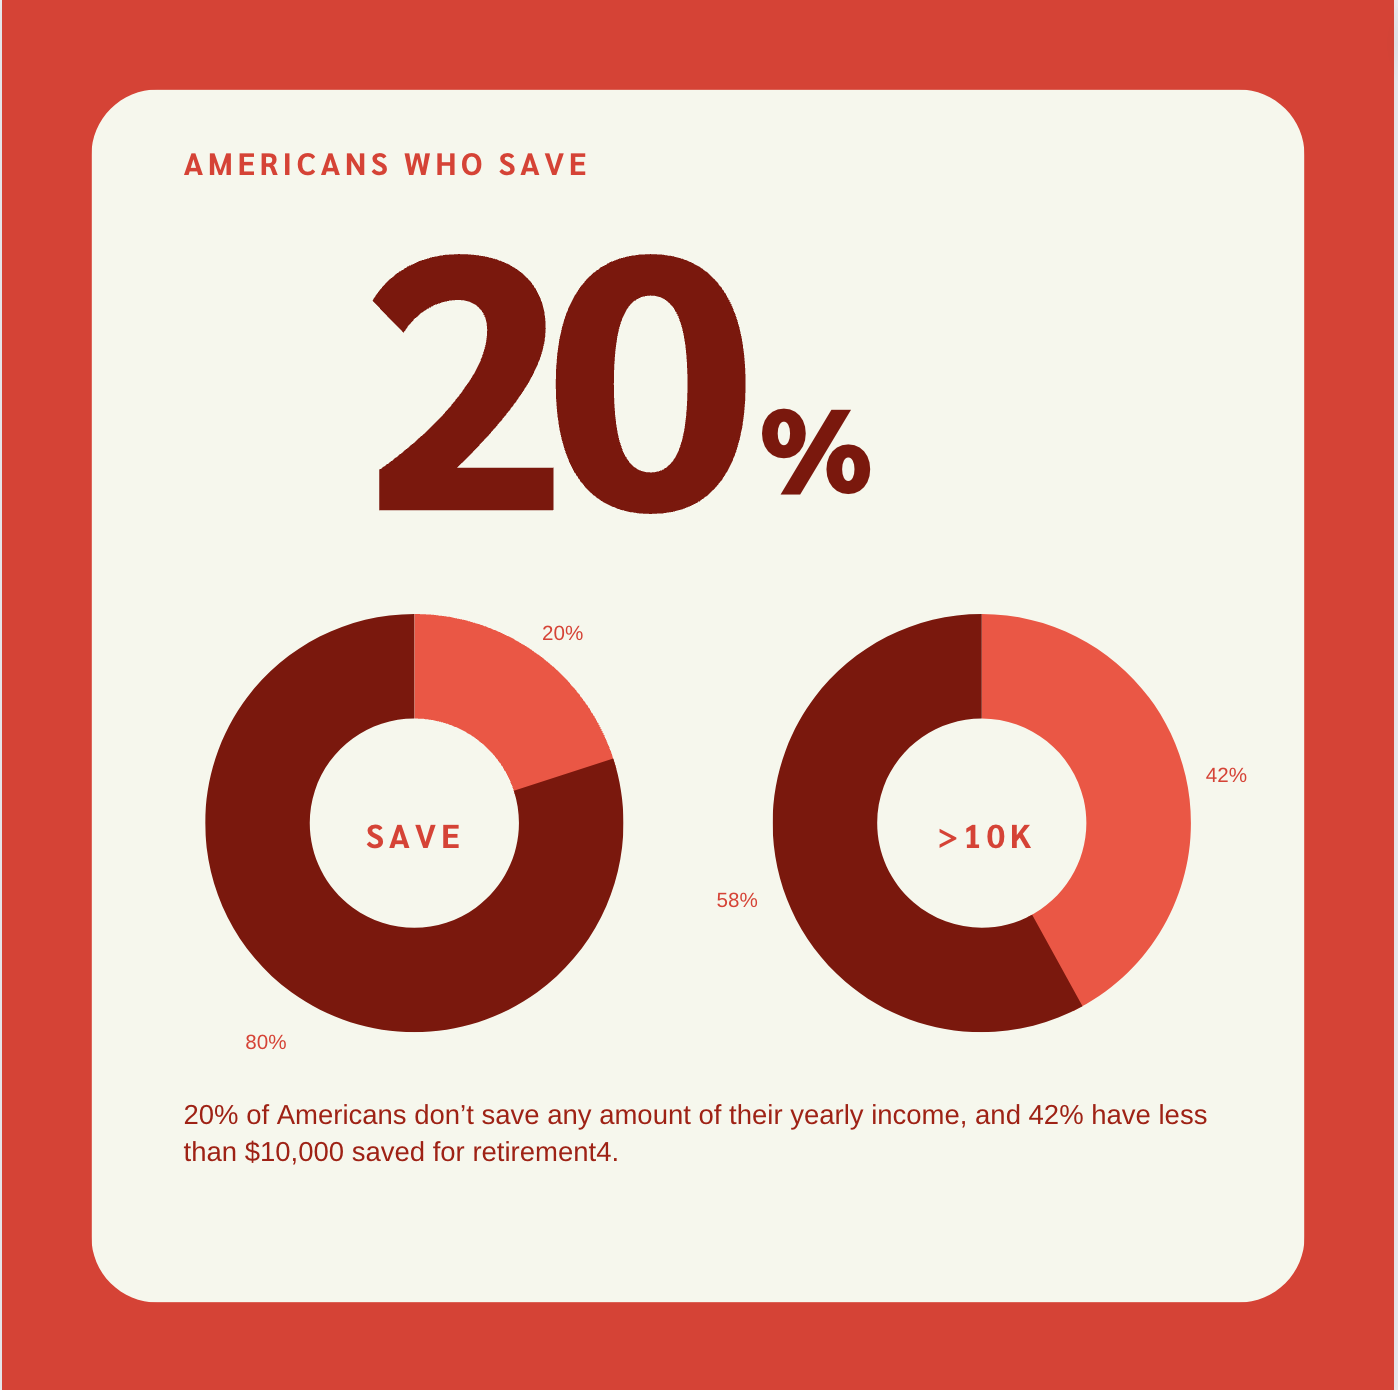


Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.




You may also like:

By
Steve Hartel, MBA, AIF®
September 27, 2017

Most of us know you can use assets in a retirement investment account or an annuity to generate income during retirement. But did you know you can use certain kinds of life insurance policies to do the same thing?

What kind of life insurance?

There are two primary types of life insurance: term and permanent. To use an analogy, think of a term policy as renting a home, and think of a permanent policy as buying a home. Similar to building equity in a home you are buying, permanent policies usually have a feature where they accumulate money inside them called Cash Value. In the same way that a mortgage payment is divided into principal (equity) and interest (the cost of the loan), the premium payment for a properly designed permanent life policy is divided into Cash Value (equity) and the cost of insurance (paying for the actual death benefit). In addition to your own money, the insurance company typically credits your policy with interest or dividends each year, so the Cash Value grows over time.

Note: There are different types of permanent policies (for example, Whole Life, Universal Life, Variable Universal Life, etc.) and they each have their plusses and minuses. Describing the differences would be lengthy and outside the scope of this article. For simplicity’s sake, I’m going to base the rest of this article on Universal Life.

So far, it sounds like an expensive savings account. What am I missing?

Using a life insurance policy to accumulate savings has some key differences from a savings account at your bank. First, the life policy offers tax deferred growth. In a bank savings account, you must report the interest you earn every year and pay income tax on it. The Cash Value in a life policy gets to grow tax deferred, just like in a qualified retirement account. Without having to pay taxes along the way, your money grows faster.

Second, the interest rate that an insurance company pays is typically much higher than the interest rate that a bank will pay on a savings account. For example, at the time of this article, the national average interest rate on a bank savings account is 0.06%1, whereas universal life policies typically average around 3%-5%.2

The biggest difference between Cash Value and a bank savings account has to do with taking the money out. With a bank account, you can only take out the dollars that are there, but there is a way to take money out of a life policy that is leveraged3.

OK, how do I get the money out?

Although the insurance company would allow you to simply withdraw the cash value, that option has a big drawback. The amount of gain in the policy (the current cash value minus the dollars you contributed along the way) would be taxed at ordinary income tax rates. There is a better option.

Insurance companies offer a way to borrow against the cash value in your policy. The proceeds from the loan are tax-free. It is important to note that you are borrowing against the cash value, not from the cash value. That means your entire cash value balance continues to earn interest. Contrast that with any other type of account, where when you withdraw money, the only portion of your money that continues to earn is the money remaining in the account.

Just as with most loans, you must pay interest on the amount you borrow. The life insurance company will typically charge 4%-5% interest. However, the cash value continues to earn 3%-5% interest, so your net cost for the loan might only be 0%-1%. No other vehicle I know of allows you to do this!

But when I’m retired, isn’t taking out a loan a bad idea?

Typically, we want to reduce our fixed expenses during retirement. And typically, adding a fixed loan payment to our retirement budget would indeed be a bad idea. However, taking a loan from your life policy doesn’t add any payments to your budgets. None. In fact, the insurance company doesn’t even expect you to repay this loan during your lifetime. At your death, the loan will be paid off from a portion of the death benefit, while the remainder will go to your beneficiaries. In a well-designed policy, your death benefit will grow over time. This should allow you to borrow tax-free income every year during retirement, pay off the loan when you die, and still have a sizeable death benefit remaining for your beneficiaries.

One small but important caution

What makes this entire strategy possible is the way life insurance proceeds are taxed. Loans taken against the policy are not taxed, nor is the death benefit taxed when received by your beneficiaries. If you take out too much money from the policy and don’t leave enough inside to pay the continuing cost of the policy, the policy will lapse (meaning the insurance company will cancel the policy). If that happens while you are still alive, then the IRS wipes out all of the tax benefits, and all that money you took out becomes taxable. That is a tax bill you want to avoid at all costs.

How do I add this strategy to my retirement plan?

Designing a policy correctly requires experience and advanced training. Many agents who only sell policies and don’t do financial planning may not be properly trained in the intricacies of this strategy. Make sure you get your policy from a reputable advisor who fully understands this strategy, and who can show you how it fits into the rest of your financial plan. This is not the kind of policy you want to buy over the internet or from an 800 number!

https://www.valuepenguin.com/banking/average-bank-interest-rates

Kelly, Patrick. (2007). Tax-Free Retirement

Dictionary.com defines leverage as “the use of a small initial investment, credit, or borrowed funds to gain a very high return in relation to one's investment, to control a much larger investment, or to reduce one's own liability for any loss.” http://www.dictionary.com/browse/leverage

By
Mike Loo, MBA
July 20, 2018

Over the course of hundreds of conversations with clients, I’ve found that quite a few them have wrestled with the idea of whether they should go back to school for an advanced degree. As their advisor, I am commonly asked if returning to school would be financially beneficial. The risk/return analysis is not always cut-and-dried in this situation. Investing X amount of dollars in a degree program does not always result in an equal or higher return in the future.

The True Value Of Education

Education is about more than just the money. After a recent conversation with a client, I had the realization that while I don’t need an MBA for my job as a financial advisor, the MBA experience itself shaped and molded me to become the advisor I am today. While I did take numerous finance classes to enhance my knowledge and quantitative skills, the greatest value I gained from earning an MBA came from improving qualitative skills, such as working with people, networking, effective communication, and time management. These are skills that I use daily in my current role.

Every experience we go through, especially those that push us out of our comfort zone and require plenty of work and time, leads to personal growth. Had I not gone through the MBA program at USC’s Marshall School of Business, I might not have developed the work ethic required to succeed as a financial advisor, and I could have ended up on a completely different career path altogether.

My Pre-MBA Self

Before entering the MBA program, I had a passion for the financial services industry, but like most college grads, I wasn’t sure how that would translate into a career. I didn’t have a clear direction for my future. I was interested in becoming an advisor but knew that it would be fairly tough to advise people on what to do with their finances when I hadn’t gone through many life experiences myself.

I had always loved the idea of making money and becoming more efficient with what I had, but I was young and dumb (and willing to admit that)! I fell into the cultural mindset of wanting to work typical business hours, earn a large salary, and enjoy life. In essence, I wanted the rewards but didn’t want to do the work involved to achieve those rewards. In my naive way of thinking, an MBA seemed to be the simplest path to achieve this end result. I can tell you that I was so wrong in this assumption!

What I Gained from My MBA

Networking Skills: USC is known for networking. Everything I heard about business school prior to attending was that the most important takeaway from the experience is to network, network, network. Unfortunately, my pre-MBA self was uncomfortable talking with people I didn’t know. I didn’t like to take the initiative to introduce myself and sometimes avoided conversing with people unless I was introduced first. As time went on and I experienced the pressure of competing against my peers and other highly qualified candidates for the same jobs, I was forced to rise to the challenge and become comfortable with being uncomfortable.

This skill alone has helped me immensely in my career when it comes to collaborating with a client’s other professionals, such as an estate attorney or CPA. In order to do a thorough job for a client, it’s often necessary to work with their other professionals to make sure we’re on the same page. In many cases, I’ve reached out to a client’s CPA to make sure they had my contact information so that if questions arise about the client’s investments, they call me rather than my client.

This skill has also helped me in reaching out to client referrals or prospective clients because I’ve found that people often want help with their financial planning, but they might not tell others or take the first step.

Effective Time And Task Management: During my time at USC, multitasking became the norm. If I wanted to effectively balance school, attend recruiting events, revise my resume, participate in mock job interviews, network for potential jobs, and somehow find time for a personal life, I had to become better with time management.

My job today is multi-faceted and includes juggling many tasks, such as answering client questions, servicing and monitoring their accounts, staying on top of changes in the industry, and dealing with changes life throws my clients’ way. Knowing that I was able to handle my heavy load in the past gives me confidence that I can prioritize my work today. Most importantly, I’ve come to realize that with all of these moving parts, it’s impossible to be rigid in only working business hours (again, something I aspired to when I was young and dumb), because not everyone is available from 8 am to 5 pm. Instead, I’ve become flexible with my schedule and instituted taking a day off during the week so that I can occasionally meet with clients on the weekend or do a phone call later in the evenings.

Is An Advanced Degree Right For You?

In my case, obtaining an advanced degree was one of my best decisions. It’s difficult to imagine doing anything else with my life and I am fortunate that I went down this path. If you or someone you know is trying to make this decision, I would love to give you some insight and help you look at the situation from an objective perspective. Or, if you would like to network and see if we could work together, call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com. I’d love to see you thriving in your life!

Get Started on Your Financial Life Plan Today