College – The Next Chapter: The Selection Process

By Trilogy Financial
May 31, 2019
Share on:

It’s graduation season, and there’s an excitement in the air about starting a new chapter. Mixed in with this excitement is an element of stress to make the right decisions: decisions on how things should be done, when they should be done and where they should be done. All these decisions are common, but they often distract from the purpose of what comes after high school.

We need to remember that higher education has a purpose. It’s more than an experience. The purpose of a college degree is employment. It is an investment, and as with any other investment, you should be calculating the return on that investment.  Spending $100,000 for a degree that secures a job with an annual salary of $40,000 is not the best rate of return.

There are plenty of creative ways to get a great college education without breaking the bank. Parents can start a 529 plan, the earlier the better, to help cover costs. Students can begin their higher education at a community college or secure college credit via Advance Placement (AP) exams. Additionally, students need to be sure that the field they are spending their time and energy on is going to reciprocate by providing solid career opportunities.

Making the wrong decision is not simply an unwise financial move. It can have lasting implications. Recent figures show that outstanding student loan debt has reached $1.5 trillion[i]. Our younger generation is not only struggling under this debt, they are also pushing off other personal and financial milestones, such as purchasing a house[ii], getting married or starting a family[iii]. These decisions can have long-lasting and far-reaching consequences.

Lastly, let’s not forget the countless parents who put their path to financial independence on hold to financially assist their struggling children. While wanting to financially help your loved ones is admirable, it helps no one to offer assistance at the expense of your own security. Just like when traveling by airplane, you need to put your own oxygen mask on and secure your safety first before aiding others. There are no scholarships for retirement, and you won’t have a financial safety net for the future if you don’t work towards creating it now.

College is truly an exciting time. Our young adults are learning who they are, where they want to go and how they intend to get there. At the same time, we cannot forget that college is a fleeting moment, one that is meant to arm the student with the tools needed to create a brighter and more successful future. Be sure to chat with your students to ensure that this experience does just that, rather than straddle these students with debt and stress.

[i] https://www.marketwatch.com/story/student-debt-just-hit-15-trillion-2018-05-08

[ii] https://www.businessinsider.com/student-debt-preventing-the-us-from-having-normal-housing-market-2019-5

[iii] https://www.bankrate.com/loans/student-loans/student-loans-survey-february-2019/

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Prior to investing in a 529 Plan investors should consider whether the investor's or designated beneficiary's home state offers any state tax or other state benefits such as financial aid, scholarship funds, and protection from creditors that are only available for investments in such state's qualified tuition program. Withdrawals used for qualified expenses are federally tax free. Tax treatment at the state level may vary. Please consult with your tax advisor before investing.

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Prior to investing in a 529 Plan investors should consider whether the investor's or designated beneficiary's home state offers any state tax or other state benefits such as financial aid, scholarship funds, and protection from creditors that are only available for investments in such state's qualified tuition program. Withdrawals used for qualified expenses are federally tax free. Tax treatment at the state level may vary. Please consult with your tax advisor before investing.

Disclaimer:

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Stock investing involves risk including loss of principal.

Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and bonds are subject to availability and change in price.

There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.

Investing in mutual funds involves risk, including possible loss of principal.

The principal value of a target fund is not guaranteed at any time, including at the target date. The target date is the approximate date when investors plan to start withdrawing their money.

No strategy assures success or protects against loss.
You may also like:

By Trilogy Financial
November 2, 2017

The day you become a parent is a day of overwhelming emotions. You may experience joy at the sight of your precious child, relief that he or she made it out of the womb, and for many of you, fear and anxiety because you somehow have to turn that seven-pound baby into an independent, responsible, and successful adult.

As parents, there are so many things we have to teach our children, beginning with the basics of how to eat and share toys to more complicated lessons such as making decisions and getting along with others. As a society, we are excelling in some areas of parenting, but falling behind in others. In a recent National Financial Capabilities Study, only 24 percent of Millennials (age 23-35) were able to answer the first three financial literacy questions correctly, and a mere 8 percent answered them all correctly.[1]

Most parents agree that we need to do a better job teaching our kids about money. Last year, T Rowe Price reported that 80 percent of parents didn’t think schools were doing enough to teach kids about financial matters.[2]However, parents cannot abdicate all responsibility to the schools. Raising children and teaching them to navigate the world is first and foremost a parent’s responsibility.

Set A Good Financial Example

The first step in teaching your kids about finances is modeling what you want them to learn. Few parents would disagree with this concept. The same T Rowe Price study mentioned above found that 69 percent of parents are very/extremely concerned about setting a good financial example for their kids. The vast majority, eight out of ten, feel that they are setting a good financial example, but two-thirds also admit to doing things that wouldn’t qualify as setting a good example.

An enormous 40 percent admitted that when it comes to talking to their kids about finances, it’s “Do as I say, not as I do.” Anyone who has raised kids knows that isn’t enough. My clients tell me they are very concerned about setting a good example for their children. The first step in teaching your kids about money is simple: Show them.

Talk About Finances

Sometimes a silent model isn’t quite enough, and some areas of personal finance aren’t very visible. That is why it is imperative to talk to your kids about finances. But talking about money may be a long-standing cultural taboo. Often this reluctance to discuss financial matters spills over into the home as well.

Forty-nine percent of the parents in the T Rowe Price study said they rarely or never discuss family finances with their children. Eighteen percent admitted to being very/extremely reluctant to discuss financial matters with their kids and 72 percent of parents experience at least some reluctance to having such a discussion. But how are kids going to learn about money if you avoid talking to them about it?  Some topics require more in-depth discussion and openness and finances are one of them.

Get Your Kids Involved

If you want financial understanding to actually sink in, you need to get your kids involved. Learning theory and research have consistently shown that the more active a learning experience is, the greater the learning gains and retention.[3] Most people have to do something to truly learn it.

How does this work with kids? Here are some ways I’ve put this into practice with my daughter: Even though she is young, I have taught her the difference between a penny, nickel, dime and quarter. Beyond just teaching the values of the coins, I then show her how to earn money by completing basic, age-appropriate chores such as making her bed and folding her clothes. As her coins start adding up, she has the opportunity to buy a toy or to save her money and earn interest (a penny for every dollar). Just as any adult, she loves the idea of making money for no extra work, so she often chooses the savings option!

At this point, I take a step back and let my daughter make her own financial decisions (and sometimes mistakes) so that she can learn from them. She and I have different values and I’ve learned that I need to let her be independent and respect her choices. On one occasion, she decided to impulsively purchase a My Little Pony beanie baby that I thought would be a waste of money. Rather than refusing to buy the toy for her, I took a step back and allowed her to buy it with her own money. Sometimes I am surprised in the process, as she still plays with this toy three months later!

Imparting financial wisdom to your kids is a challenging process that takes years. So, if you don’t feel like you’re doing an adequate job of teaching your kids about money, you’re not alone. Even if you are doing a good job, you probably agree with the 77 percent of the T Rowe Price survey parents who said that they wished there were more resources available to help them teach their kids about financial matters.

I believe that every child can learn critical financial lessons at a young age that will set them up for future success. I want to provide you with the tools to help you on this journey. To set up a meeting, call my office at (949) 221-8105 x 2128, or email me at mike.loo@trilogyfs.com.

[1] http://gflec.org/wp-content/uploads/2015/01/a738b9_b453bb8368e248f1bc546bb257ad0d2e.pdf

[2] https://corporate.troweprice.com/Money-Confident-Kids/images/emk/2015-PKM-Report-2015-FINAL.pdf

[3] http://www.joe.org/joe/1994august/a6.php

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
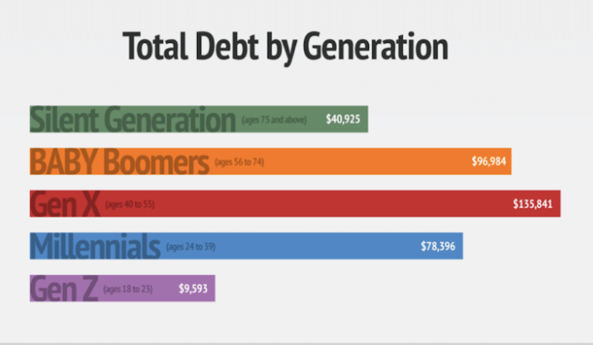
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


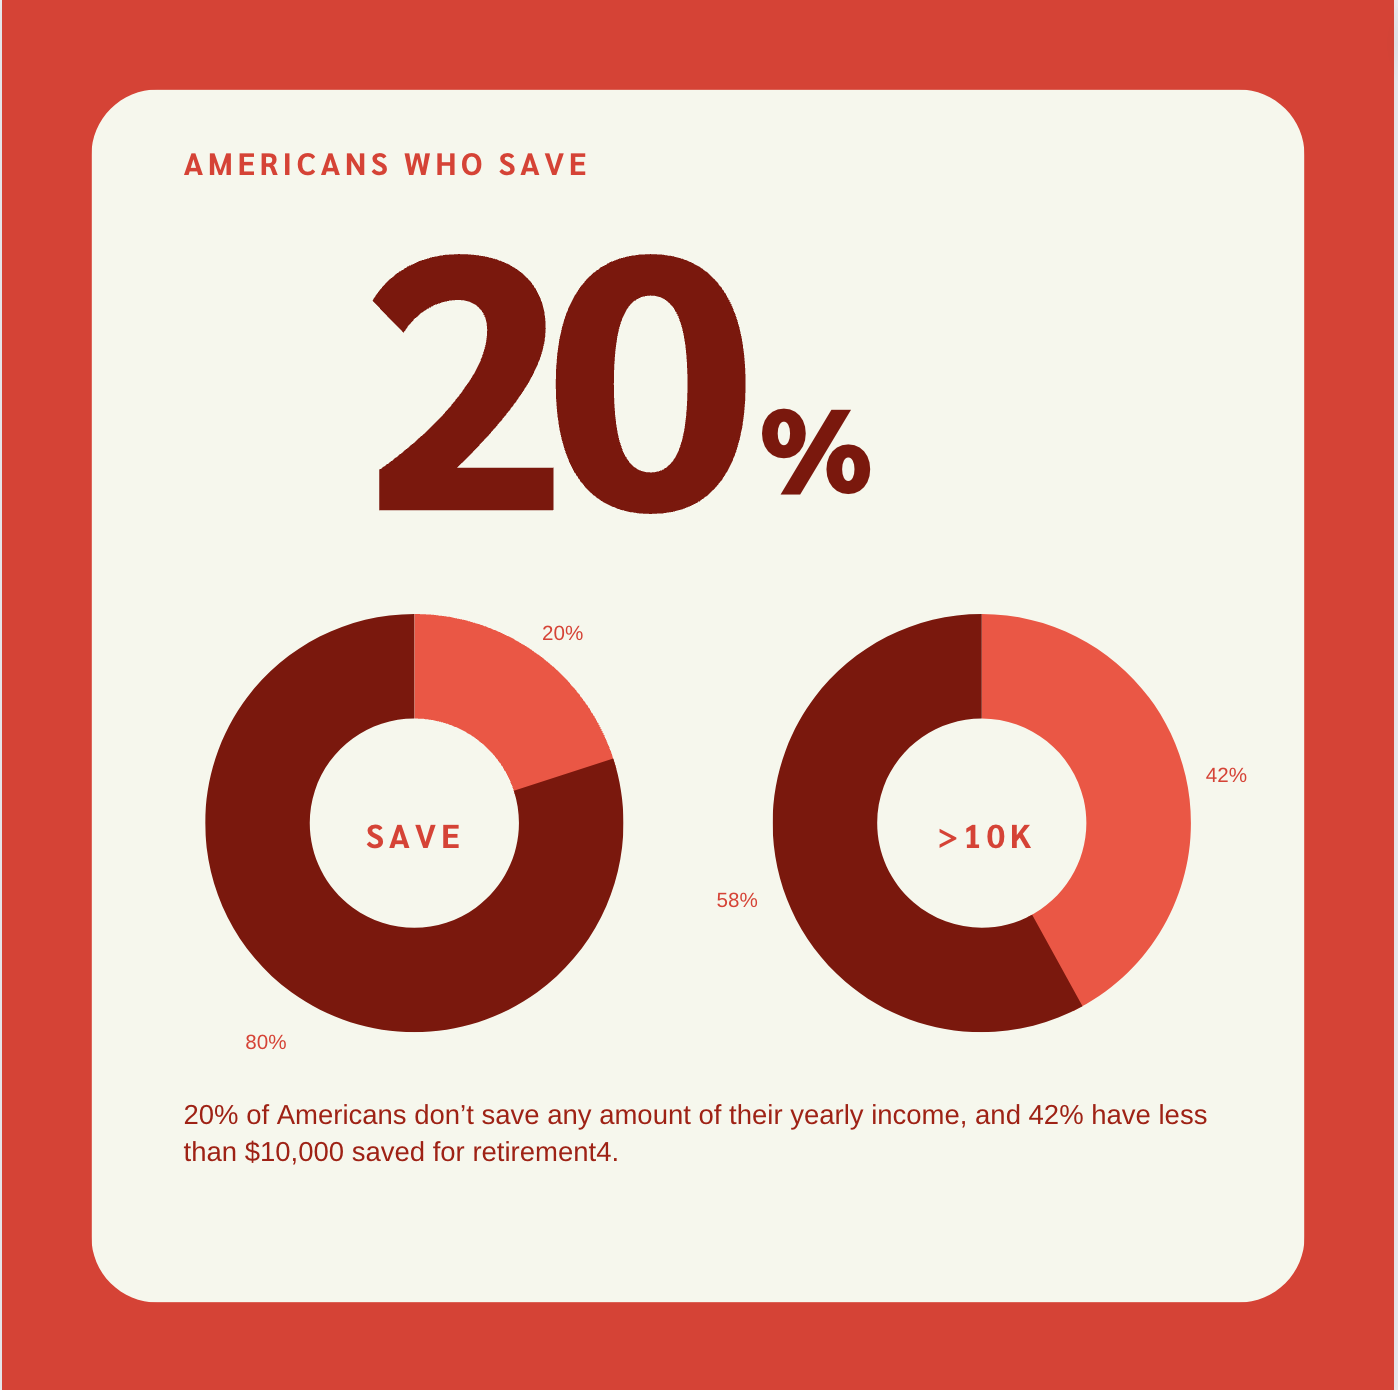
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


Get Started on Your Financial Life Plan Today