

Capitalizing on Your Employer Sponsored Retirement Plan

By
February 19, 2019
Share on:

Let’s talk about employer loyalty. For much of the 20th century, Americans (by and large) followed a standard script: enter the workforce and work for a single company for decades, then throw a retirement party at 65 and cash in a pension – a reward for years of company loyalty. This pension provided retirement income; usually, a percentage of the yearly salary the employee earned while working. American Express established the first corporate pension plan in the US in 1875. By 1960, about half of the private sector employees had a pension. Of course, in 1960 the average life expectancy was 67, meaning that if you retired at 65 (standard at the time), the average pension only had to provide income for two years.

Since 1960 there have been many advances in modern medicine raising average life expectancy to 79. Suddenly, plans designed to cover a few years of post-retirement income were expected to cover retirees well into their 80s and 90s. Companies offering pensions began to realize that their retirement plans were becoming increasingly – sometimes prohibitively – expensive to fund. As pension expenses continued to rise towards the end of the 20th century, many companies were forced to design new systems to ensure their employees were financially secure come retirement.

The 401(k) plan hit the streets in 1980. The employer-sponsored retirement plan was rolled out as a replacement to traditional pensions and has since become the most common retirement savings mechanism in America. In essence, the 401(k) provides a tax-deferred way for employees to set aside wages for retirement. Employees elect to divert a certain percentage of their income each year to a 401(k) account. The diverted funds grow tax-free in that account until the employee retires.

In addition to providing the account, most companies offer a savings-match system. For instance, in a 3% match system, the company would match up to 3% of an employee’s elective contributions to their 401(k) account. The employer match provides a strong incentive for employees to start planning for retirement. If an employee doesn’t divert AT LEAST the match threshold into a 401(k) they miss out on the employer match – in other words, they lose out on free money from their employer.

Let’s talk about the benefits. Funds in a 401(k) account are able to grow tax-free. Because growth is not disturbed by capital gains taxes, accounts are able to grow faster than a standard individual account. Of course, there’s always a catch: money in employer-sponsored plans – like a 401(k) – cannot be withdrawn prior to age 59 ½ without paying penalties. Most plans offer options for the participants to increase their contribution rate on an annual basis, and small increases in contribution rate (even as small as 1%) year over year can make a huge difference by the time you retire.

Contributing to employer-sponsored retirement plans such as a 401(k) or 403(b) – the non-profit version of a 401(k) – is a vital part of preparing for retirement. The money is automatically deducted before your paycheck is cut, making it easy to budget and painlessly save for retirement at the same time.

Contributing to employer-sponsored retirement plans is an essential step towards retirement planning – but it is only the first step.

Please contact me at zach.swaffer@trilogyfs.com if you are interested in discussing the next steps you can take to ensure retirement security.
You may also like:

By
David McDonough
September 12, 2023

No one really wants to think about life insurance. But if someone depends on you financially, it’s a topic you shouldn’t avoid. Are any of these reasons stopping you from getting the life insurance coverage you need? If so, read on!

1. My family can rely on loans or other family members.

We know we can rely on our families for support as we navigate life. However, if you were to die, your family’s world would shift on its axis—emotionally and financially. A time of grief is not the time to crowdsource funeral funds or make phone calls for money every month when bills come due. Life insurance means there can be an affordable solution in place so that doesn’t need to happen.

2. Money is tight. I just can’t afford life insurance.

Bills, rent or mortgage, car payments, childcare, food, gas … and the list grows as your family does. So what would happen to them financially if you died? If you’re gone, so is your income, but their bills and expenses will stay the same. If money is tight, you can’t afford not to have life insurance. It picks up the financial burden for your family when you are no longer there to do it.

3. Life insurance will be a free ride for my kids.

Your parents taught you hard work, and it’s what you’re teaching your children. But life insurance isn’t about leaving your kids a financial windfall. It’s about practicing—and teaching—the principles of personal financial responsibility. Preparing for the future with life insurance is a lesson in goal-setting, budgeting and discipline that ensures your loved ones will be OK financially, which is a valuable lesson to pass on.

Don’t let these myths stand in the way of getting life insurance—or more of it.

Download this comprehensive blog as a concise one-page here: 3 Myths About Life Insurance

By
June Adams
May 10, 2022

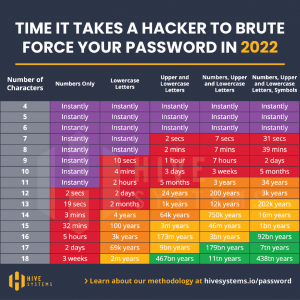
How long do you think it would take a hacker to crack your current passwords?

On average, it takes a hacker about 2 seconds to crack an 11-character password that only uses numbers. See the attached chart that illustrates the time it takes for a hacker to brute force attack your password. A brute force attack is when cybercriminals use trial and error to guess your details. Cybercriminals currently use sophisticated software that can run thousands of password combinations in a minute, but their technology and resources are only getting stronger.

A general rule is that your password should be at least 11 characters, utilizing both numbers as well as upper and lowercase letters. That combination will take hackers 41 years to crack. Regardless of the possible variations, the shorter your password, the easier it is to crack. Check out how long it will take a hacker to crack your password at https://www.security.org/how-secure-is-my-password/.

Lastly, simplify and secure your accounts by using a password manager that creates and stores all your passwords for you.

Strengthen your password security with the following tips:

  • Prioritize the length and complexity of your passwords.
  • Don't use personal information. This can be publicly available and easily accessible by hackers.
  • Avoid using dictionary words as passwords. Cracking tools can easily process every word in the dictionary.
  • Don't reuse passwords. If one account is breached, your other accounts would be vulnerable as well. Rather, use password managers, which are a convenient and secure way to manage complex passwords on multiple platforms.
  • Use multifactor authentication (MFA or 2FA) for especially sensitive accounts.
  • Avoid typing passwords while using public Wi-Fi. Instead, use a VPN or avoid websites that require your login information.


Get Started on Your Financial Life Plan Today
