Yes, Life Insurance Can Generate Tax Free Income For Retirement. Here Are Some Key Things You Should Know.

By
September 27, 2017
Share on:

Most of us know you can use assets in a retirement investment account or an annuity to generate income during retirement. But did you know you can use certain kinds of life insurance policies to do the same thing?

What kind of life insurance?

There are two primary types of life insurance: term and permanent. To use an analogy, think of a term policy as renting a home, and think of a permanent policy as buying a home. Similar to building equity in a home you are buying, permanent policies usually have a feature where they accumulate money inside them called Cash Value. In the same way that a mortgage payment is divided into principal (equity) and interest (the cost of the loan), the premium payment for a properly designed permanent life policy is divided into Cash Value (equity) and the cost of insurance (paying for the actual death benefit). In addition to your own money, the insurance company typically credits your policy with interest or dividends each year, so the Cash Value grows over time.

Note: There are different types of permanent policies (for example, Whole Life, Universal Life, Variable Universal Life, etc.) and they each have their plusses and minuses. Describing the differences would be lengthy and outside the scope of this article. For simplicity’s sake, I’m going to base the rest of this article on Universal Life.

So far, it sounds like an expensive savings account. What am I missing?

Using a life insurance policy to accumulate savings has some key differences from a savings account at your bank. First, the life policy offers tax deferred growth. In a bank savings account, you must report the interest you earn every year and pay income tax on it. The Cash Value in a life policy gets to grow tax deferred, just like in a qualified retirement account. Without having to pay taxes along the way, your money grows faster.

Second, the interest rate that an insurance company pays is typically much higher than the interest rate that a bank will pay on a savings account. For example, at the time of this article, the national average interest rate on a bank savings account is 0.06%1, whereas universal life policies typically average around 3%-5%.2

The biggest difference between Cash Value and a bank savings account has to do with taking the money out. With a bank account, you can only take out the dollars that are there, but there is a way to take money out of a life policy that is leveraged3.

OK, how do I get the money out?

Although the insurance company would allow you to simply withdraw the cash value, that option has a big drawback. The amount of gain in the policy (the current cash value minus the dollars you contributed along the way) would be taxed at ordinary income tax rates. There is a better option.

Insurance companies offer a way to borrow against the cash value in your policy. The proceeds from the loan are tax-free. It is important to note that you are borrowing against the cash value, not from the cash value. That means your entire cash value balance continues to earn interest. Contrast that with any other type of account, where when you withdraw money, the only portion of your money that continues to earn is the money remaining in the account.

Just as with most loans, you must pay interest on the amount you borrow. The life insurance company will typically charge 4%-5% interest. However, the cash value continues to earn 3%-5% interest, so your net cost for the loan might only be 0%-1%. No other vehicle I know of allows you to do this!

But when I’m retired, isn’t taking out a loan a bad idea?

Typically, we want to reduce our fixed expenses during retirement. And typically, adding a fixed loan payment to our retirement budget would indeed be a bad idea. However, taking a loan from your life policy doesn’t add any payments to your budgets. None. In fact, the insurance company doesn’t even expect you to repay this loan during your lifetime. At your death, the loan will be paid off from a portion of the death benefit, while the remainder will go to your beneficiaries. In a well-designed policy, your death benefit will grow over time. This should allow you to borrow tax-free income every year during retirement, pay off the loan when you die, and still have a sizeable death benefit remaining for your beneficiaries.

One small but important caution

What makes this entire strategy possible is the way life insurance proceeds are taxed. Loans taken against the policy are not taxed, nor is the death benefit taxed when received by your beneficiaries. If you take out too much money from the policy and don’t leave enough inside to pay the continuing cost of the policy, the policy will lapse (meaning the insurance company will cancel the policy). If that happens while you are still alive, then the IRS wipes out all of the tax benefits, and all that money you took out becomes taxable. That is a tax bill you want to avoid at all costs.

How do I add this strategy to my retirement plan?

Designing a policy correctly requires experience and advanced training. Many agents who only sell policies and don’t do financial planning may not be properly trained in the intricacies of this strategy. Make sure you get your policy from a reputable advisor who fully understands this strategy, and who can show you how it fits into the rest of your financial plan. This is not the kind of policy you want to buy over the internet or from an 800 number!

https://www.valuepenguin.com/banking/average-bank-interest-rates

Kelly, Patrick. (2007). Tax-Free Retirement

Dictionary.com defines leverage as “the use of a small initial investment, credit, or borrowed funds to gain a very high return in relation to one's investment, to control a much larger investment, or to reduce one's own liability for any loss.” http://www.dictionary.com/browse/leverage
You may also like:

By
Jeff Motske, CFP®
March 19, 2018

Do you remember Veruca Salt, the spoiled rich girl from the movie Willy Wonka and the Chocolate Factory? You know, the girl who yells at her father, “I want it now!” And her clueless, abiding father would get her whatever she wanted, which consequently did more harm than good.

Well, we all have one of those fathers. Not the one that we buy a Father’s Day card for every year, but one that we carry in our wallet. One that typically says yes to whatever we want to buy, regardless of how that may spoil our budget, or worse, our credit score. It’s called a credit card.

Please understand, I am not calling you spoiled or demanding. However, in this instantaneous age, it’s very easy to spend impulsively or unconsciously. How many of us have gone to Target to purchase one or two items and ended up walking out with a full cart? How many of us have passed some idle time perusing one of our favorite online vendors, one who may even have our credit card information stored in their system? We may have had no intention to buy when we got on the site, but when we spot a good “deal,” it only takes a few quick clicks to make it ours.

You see, it happens a lot more often than you think. Study after study has shown that people will spend more money when they use credit cards than when they use cash, sometimes as much as twice the average cost for the same item1. Not only does the method of payment affect the quantity, it can also affect quality, with consumers willing to purchase unhealthy or unnecessary items when paying with a credit card as opposed to cash2.

The convenience of clicking or swiping to purchase, rather than handing over tangible cash, has spurred on overspending and racked up national credit card debt to $905 billion3. The truth of the matter is that we have lost sight of the fact that credit cards are essentially a thirty-day loan, which is becoming more and more apparent with the younger generations. Based on Experian’s Millennial Credit and Finance Survey Report Part II, 58 percent of millennial credit card holders polled in 2015 had maxed out a credit card, been charged a late fee, had an increase in the interest rate on a credit card, had a credit card declined or had defaulted on a credit card payment4. Financial behaviors like these can wreak a lot of havoc on a young person’s credit score and financial future. Such a small, seemingly innocent looking piece of plastic can do a lot of damage.

Now I am in no way advocating a credit-free lifestyle. Not only are credit cards a convenient way to build up your credit score, but many cards offer rewards programs where users can earn discounts, airline mileage and cash back. Most importantly, though, there are an increasing amount of vendors that no longer accept cash. This is not simply limited to online purchases. Have you ever tried leaving an airport parking lot or paying to access a toll road with cash? In most places, it is nearly impossible.

What I am saying is we need to start being a bit more mindful with our money, a bit more critical of how we spend. I mentioned the perks of credit cards rewards programs earlier. How many of us, though, have actually stopped to determine how much those perks really cost once you start adding up interest and impulse purchases? If switching over to cash purchases helps us become a bit more mindful with our money, then so be it.

Before you end up with a pile of debt and regret.

1. https://www.nerdwallet.com/blog/credit-cards/credit-cards-make-you-spend-more/

2. https://www.psychologytoday.com/blog/the-science-behind-behavior/201607/does-it-matter-whether-you-pay-cash-or-credit-card

3. https://www.nerdwallet.com/blog/average-credit-card-debt-household/

4. https://www.slideshare.net/Experian_US/experian-millennial-credit-finance-survey-report-part-ii

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


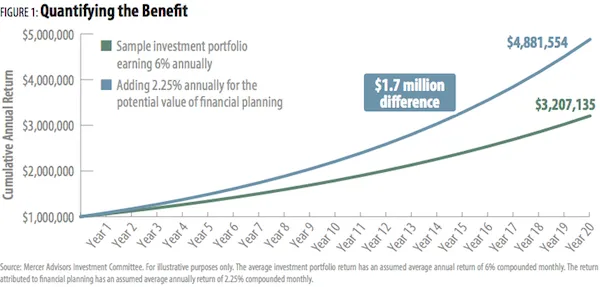
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


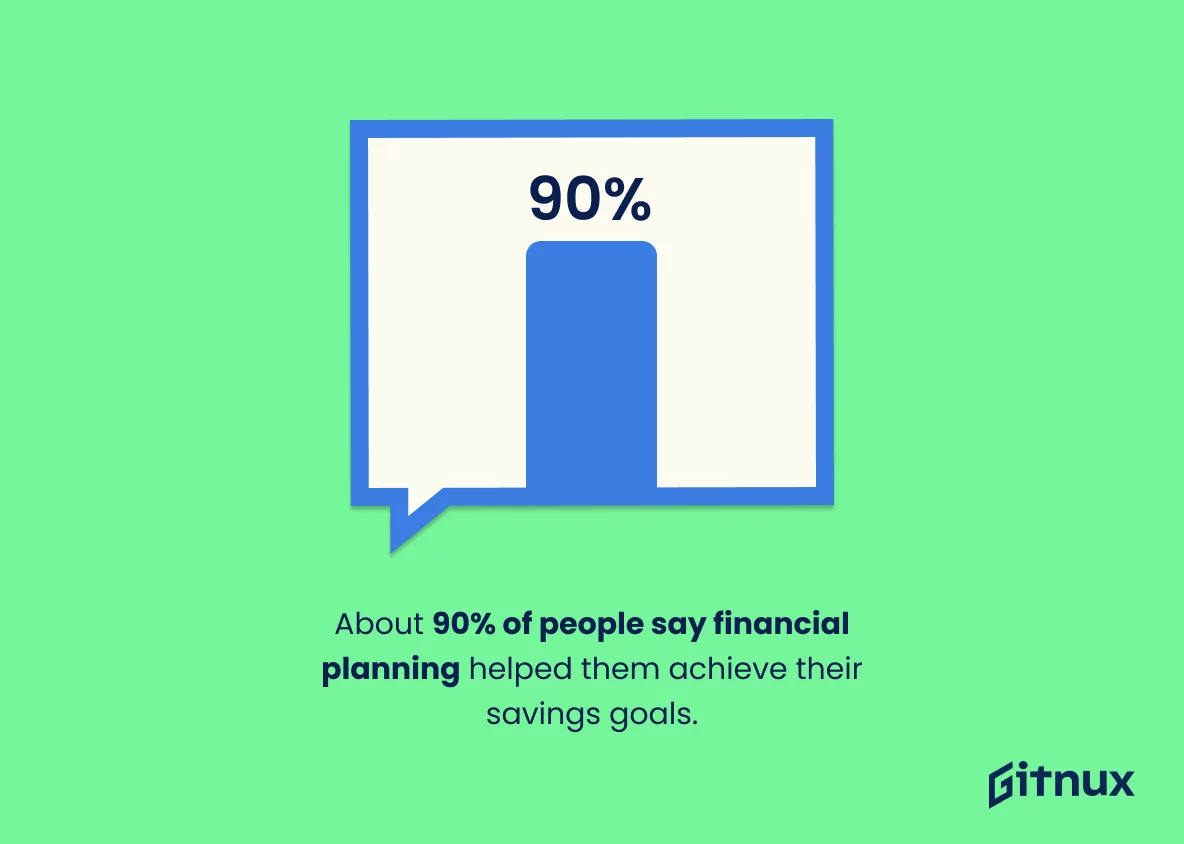
Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


Get Started on Your Financial Life Plan Today