|
|
Navigating the intricacies of life insurance can be a daunting task, but at Trilogy Financial, we believe that understanding the basics is crucial in making informed financial decisions. Life insurance, in essence, provides a straightforward solution to a complex question: How can your family be financially safeguarded if the unexpected were to happen to you? Whether it's covering immediate expenses, sustaining a business, or planning for future needs like education and retirement, life insurance offers a safety net. At Trilogy, we're committed to simplifying the complexities of life insurance, empowering you to make choices that secure your loved one's financial well-being.
Life insurance is actually a simple answer to a difficult question: How will my loved ones manage financially if I were to die? If anyone depends on your income or the unpaid work you do, they would most likely struggle if you were to pass away. Life insurance pays cash—also known as a death benefit—to your loved ones when you die. It replaces your income and the many non-paid ways you support your household. Your family can use this cash to help pay for immediate and ongoing expenses like funeral costs, daily expenses, a mortgage or rent, and keep a business afloat. It can also be used for future expenses like college tuition, retirement and more.
The good news is, life insurance may be less expensive than you think. The cost depends on four main factors: your age, your health, the type of policy and how much coverage you buy. In general, you’ll pay less the younger and healthier you are. To put the price in perspective, a healthy 30-year-old may be able to buy a $250,000 20-year level term policy for about $13 a month.1 That means if you purchase that policy and pay the $13 a month without fail, your loved ones would get $250,000 if you were to die at any point during those 20 years.
Life insurance generally falls into two categories:
Term life insurance provides protection for a specific period of time (the “term” is often 10, 20 or 30 years). This makes sense when you need protection for a specific amount of time—for instance, until your kids graduate from college or your mortgage is paid off. Term life insurance typically offers the most amount of coverage for the lowest initial premium, and is a good choice for those on a tighter budget.
Permanent life insurance provides lifelong protection for as long as you pay the premiums. It also provides “living benefits” like the ability to accumulate cash value on a tax-deferred basis, which you can tap into to help buy a home, cover an emergency expense and more. Because of these additional benefits, initial premiums are higher than what you’d pay for a term life insurance policy with the same amount of coverage.
Sometimes getting a combination of term and permanent insurance is the best answer.
The amount of life insurance to buy depends on who you want to protect financially and for how long. As a very general rule of thumb, experts recommend having life insurance that equals between 10 to 15 times your gross income. But you may need more or less than that. An easy way to get a working idea of how much you need is to use an online Life Insurance Needs Calculator.
Download this comprehensive blog as a concise one-page here: What You Need To Know About Life Insurance
Or click here to watch a short video.
Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?
Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.
Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.
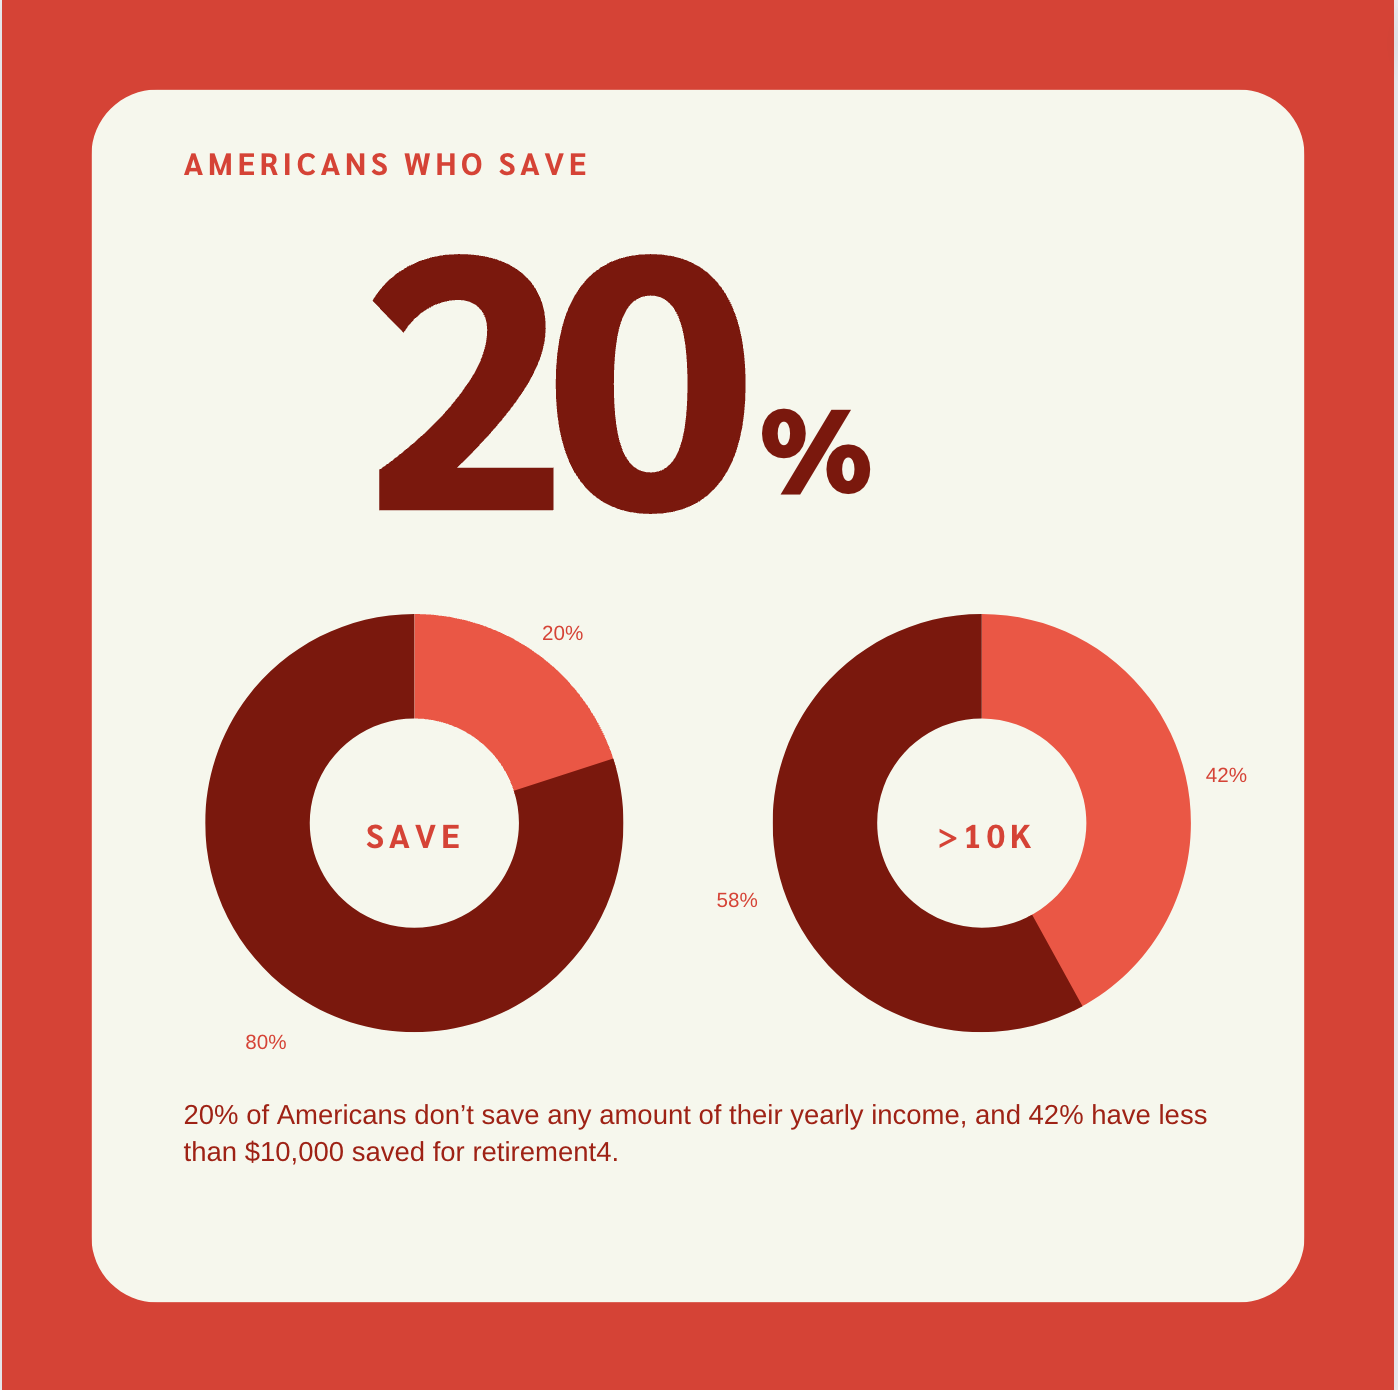
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement4.
There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.
Easily Meet with a Certified Financial Planner.
The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.
Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:
These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.
The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.