Millennials and Gen Z Lead Growing Need for Life Insurance in 2023

By Trilogy Financial
September 19, 2023
Share on:

The pandemic’s economic disruption altered people’s views on a wide range of money topics—from the feeling of financial insecurity to the extra burden of debt, to how best to protect their loved ones, physically and financially. People’s interest in life insurance—knowing they have a need for it—was heightened during the pandemic and remains so, as people take a closer look at their financial security and well-being. The 2023 Insurance Barometer Study, by Life Happens and LIMRA, shows this trend is prevalent among the younger generations, as well as with single mothers.

Single Moms Need the Industry’s Help

Fewer women own life insurance than men, 49% vs. 55% respectively. And that number is even starker for single moms: Just 2 of 5 single mothers (40%) own life insurance. That said, 6 in 10 single moms (59%) know they have a life insurance need gap—meaning they need coverage or more of it (vs. 41% of all adults) equaling about 5 million households. And 4 in 10 (38%) say they intend to buy coverage this year. With 7.9 million single-mom households, according to the U.S. Census Bureau, there is a dire need for single moms to
purchase life insurance, or more of it.

The primary reason single moms own life insurance (63%) is the same as the general population: to cover burial costs. However, only 26% say they have it to replace lost income. And more than half (51%) say they are “extremely concerned” about leaving dependents in a difficult financial situation if they died prematurely, vs. 29% of the general population.

That’s not the only area of financial concern. In fact, single moms have increased levels of concern over a wide range of financial issues—often double-digits—over the general population.
• Having money for a comfortable retirement: 58% vs. 44%
• Saving for an emergency fund: 56% vs. 38%
• Paying monthly bills: 50% vs. 32%
• Ability to afford college: 40% vs. 22%

Owning life insurance makes people feel more financially secure: 69% of life insurance owners feel secure vs. 49% who don’t own. For single moms, this is 52% of owners feel secure vs. 30% who don’t own. The good news is that while only a third of single moms (35%) work with a financial advisor currently, more than half without one are looking for an advisor (52%) to help them navigate their finances.

Desire and Need Are on the Rise

Gen Z is growing up—they’re adults now who are in the weeds of financial responsibilities and stresses. Half of Gen Z is now 18-26 years old, which means 19 million young adults are ready for life insurance, most of whom are non-owners; and Millennials, at 27 to 42, are well into their careers and starting families. The study took a look at life insurance ownership among different age groups and found that half of all adults (52%) own life insurance, with 40% of Gen Z adults and 48% of Millennials currently owning it.

As Gen Z starts hitting life milestones such as finding a partner, buying a home and having children, half (49%) say
they either need to get life insurance or increase their coverage. And Millennials are not far behind, with 47% saying so. And they are ready to take action: 44% of Gen Z adults and 50% of Millennials say they intend to buy life insurance this year.

They also want to purchase it where they have become comfortable—online—and that goes for all generations. In 2011, 64% of people said they preferred to buy life insurance in person; by 2020, just 41% felt this way. In 2023, it dropped to 29%.

Education Is Key for Gen Z

There is work to do on educating people about ownership: 42% of all adults say they’re only somewhat or not at all knowledgeable about life insurance.
A quarter of Gen Z and Millennials say that not knowing how much or what kind of life insurance to buy stops them from getting coverage. And 37% of Gen Z and 27% of Millennials say
they “haven’t gotten around to it.”

Across generations, cost is cited as the top reason for not getting life insurance. But only a quarter (24%) of people correctly estimated the true cost of a policy for a healthy 30- year-old, which is around $200 a year.* More than half of Gen Z adults (55%) and 38% of Millennials thought it would be $1,000 or more.

With the current climate adding financial uncertainties to Gen Z and Millennials, including layoffs and inflation, it is imperative that the two age groups learn how to protect their loved ones financially. Education around finances in general, inclusive of life insurance, will be extremely beneficial, particularly for Millennials, who cite the highest overall level of financial concern (39%).

Download this comprehensive blog as a concise one-pager here:Millennials and Gen Z Lead Growing Need for Life Insurance in 2023


*Survey respondents were asked how much they thought a $250,000 20-year level term policy would cost per year for a healthy, nonsmoking 30-year-old, which is around $200.

Please source all statistics: 2023 Insurance Barometer Study, Life Happens and LIMRA© Life Happens 2023. All rights reserved.
You may also like:

By
Jeff Motske, CFP®
May 22, 2018

“I have no interest in learning about finances. My [husband/wife] takes care of that.”

I have heard this statement from many clients throughout my career, and I understand the sentiment that prompts this response. Human nature has shown that when groups of people come together, they divvy up tasks to different individuals based on their strengths or roles in the group. You see this in many different groups, including families. My wife cooks dinner, and I’m great at taking out the garbage. With my siblings, I’m great at being the peacemaker while my sister knows how to shine a light on different perspectives. These established roles help our family units function smoothly and effectively…

Until one of the pieces of our unit is no longer around.

I’ve seen it far too many times. Clients come in distraught and overwhelmed because they’ve lost a loved one who typically acted as the family’s Chief Financial Officer. Sometimes they don’t know if there is a will or where legal documents are saved. Perhaps they are aware of a family safety deposit box, but they’re not sure where it is or how to access it. They aren’t sure about account balances or how to read statements. They may not even have access to critical accounts because the deceased was the one who knew the passwords. Now they are dealing with grief and heartbreak, compounded by confusion as to what the next steps are for maintaining their family’s financial solvency.

This is why I insist that both parties in a marriage are involved in financial planning meetings and decisions. I also recommend, especially for my senior clients, that other family members or loved ones are aware of the basics of their financial plans. It makes things so much simpler if all important documents, including a list of passwords, are stored together. If security is a concern, there are plenty of third party vendors that will virtually store that information for you. In most cases, though, a virtual safekeeper of your important information isn’t ideal. What is really needed is someone who will help guide your loved ones during that difficult time. That’s when a financial advisor can be an invaluable asset. I have had many Trilogy clients express how relieved they are to know that their financial advisor will be around to guide and assist the loved ones after he or she has passed. At Trilogy Financial, we don’t consider it a job. We consider it an honor and a calling.

There is a saying that it takes a village to raise a child. The truth is, it takes a village to care for anyone. Please make sure that your village is prepared and has the proper tools to take care of you. If you’re not sure where to begin, you may want to meet with a financial advisor. Our Trilogy Advisors are not only trained to assist your family on how to prepare for the future, but will also be there to provide support and service during a difficult and overwhelming time.

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


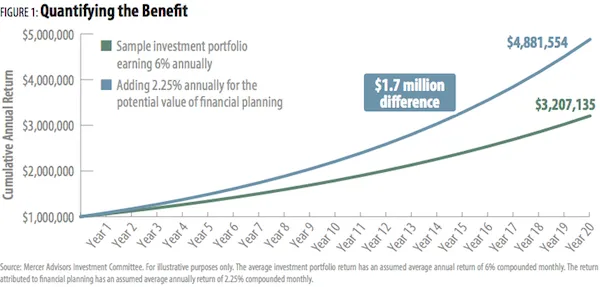
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


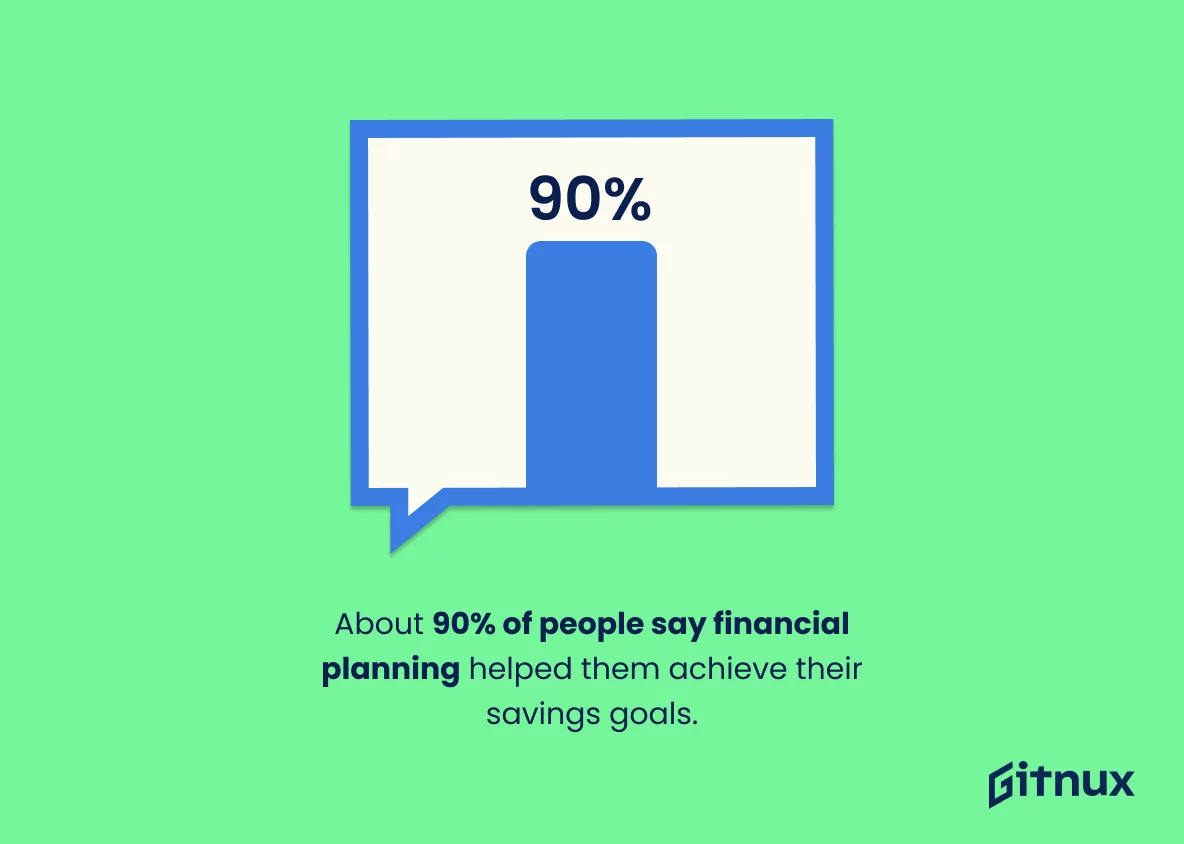
Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


Get Started on Your Financial Life Plan Today