

Long-Term Care (LTC) Options as You Age

By Trilogy Financial
September 23, 2019
Share on:

People are living longer – that’s a fact. Unfortunately, all those additional years aren’t always spent in optimum health. With longevity comes the complicated question of how to pay for the necessary health care for those additional years. Costs for unexpected and long-term chronic care are rarely covered by Medicare. People are having to face these costs on their own. Thankfully, the right type of planning can make this task less daunting.

Long-term care can be an overwhelming topic. The statistics are sobering. 52% of people turning age 65 will need some type of long-term care services in their lifetimes, and 14% will need long-term care for longer than five years. With the median annual cost of adult day care averaging $18,200 and assisted living facilities at $45,000, the financial implications can be staggering. It can sound like a complicated topic, but the way to protect you really boils down to three options.

  • Self-insure: This is the option that many select by default because they don’t want to think about the possibility of illness creeping into their future. It’s a scary option, which they hope won’t happen to them. However, this option typically leaves them unprepared for the medical costs that eventually do occur.
  • Long-term Care Policy: This is a good form of financial protection as it covers your risk but won’t wreck your financial plan. However, the down side with such a policy is that if you don’t use it, you lose it.
  • Accelerated Benefit Riders (ABR’s): Lastly, you can invest in life insurance you don’t have to die to use. These riders in your insurance plan will allow you to receive your benefits prior to death due to terminal, chronic or critical illness. The ABR’s will cover your risk, and you’ll still receive the benefit if you don’t need to use it for long-term care purposes.

Now, there is no one-size-fits-all solution. It’s always best to meet with your trusted financial advisor to find the right option for you. Just know that when you do take the time to plan ahead and find the right option for your particular situation, you’re not only providing for your future but also your peace of mind as well.

[i] https://www.morningstar.com/articles/879494/75-must-know-statistics-about-long-term-care-2018-edition

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.
You may also like:

By
Jeff Motske, CFP®
August 26, 2018

The one constant in life is change.

It sounds cliché, but it’s very true. Almost everyone will have a moment where change will rock the typical steadiness of your life. A health scare. An unexpected job change. Divorce. A significant drop in the market (i.e., a bear market) as you’re on the verge of retirement. These shocking twists can make us want to scramble and take immediate action to right our suddenly turned around world.

However, sometimes the simplest solutions are the best. When coping with physical imbalance, the key is to focus on a stationary point.1 This allows your brain to make adjustments to maintain your equilibrium. The same applies to other life changes. Fear and frustration may urge you to take some unexpected course of action to address sudden changes, and sometimes these knee-jerk reactions cause more harm than good. In those highly-charged moments, soliciting some professional council, like from a trusted financial advisor, can help us locate that stationary goal and work with us to identify any adjustments that need to be made.

Every time I meet with my clients, I remind them what we’re working towards. Yes, I want to be made aware of any changes they may have experienced, but I also want to remind them what all the decisions we’re making and actions we’re taking are working towards. We planned for the unexpected expenses by saving an emergency fund. For my younger clients, momentary dips in the market don’t necessarily derail us from our long-term goals. In fact, it actually provides purchasing opportunities. Additionally, markets go down, but they are always achieving new high’s long-term. For my clients on the cusp of retirement, these dips were prepared for by diversifying their savings and expanding their emergency fund. With the long-term goals in mind, it’s easier to see the horizon from within the storm.

The trick of it all is to stay focused on the long-term vision of the life you’re trying to create. I’ve learned that this applies not simply to your finances, but other aspects of your life like your career or your family as well. Changes will occur, and your world may get a little rocked, but as long as you take a breath and continue to focus on your long-term goals, you’ll find yourself on sturdy ground once again.

  1. https://www.scienceabc.com/sports/why-focussing-on-something-helps-in-maintaining-balance.html
By
June Adams
May 10, 2022

How long do you think it would take a hacker to crack your current passwords?

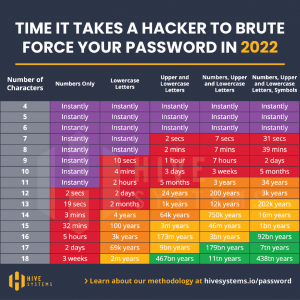
On average, it takes a hacker about 2 seconds to crack an 11-character password that only uses numbers. See the attached chart that illustrates the time it takes for a hacker to brute force attack your password. A brute force attack is when cybercriminals use trial and error to guess your details. Cybercriminals currently use sophisticated software that can run thousands of password combinations in a minute, but their technology and resources are only getting stronger.

A general rule is that your password should be at least 11 characters, utilizing both numbers as well as upper and lowercase letters. That combination will take hackers 41 years to crack. Regardless of the possible variations, the shorter your password, the easier it is to crack. Check out how long it will take a hacker to crack your password at https://www.security.org/how-secure-is-my-password/.

Lastly, simplify and secure your accounts by using a password manager that creates and stores all your passwords for you.

Strengthen your password security with the following tips:

  • Prioritize the length and complexity of your passwords.
  • Don't use personal information. This can be publicly available and easily accessible by hackers.
  • Avoid using dictionary words as passwords. Cracking tools can easily process every word in the dictionary.
  • Don't reuse passwords. If one account is breached, your other accounts would be vulnerable as well. Rather, use password managers, which are a convenient and secure way to manage complex passwords on multiple platforms.
  • Use multifactor authentication (MFA or 2FA) for especially sensitive accounts.
  • Avoid typing passwords while using public Wi-Fi. Instead, use a VPN or avoid websites that require your login information.


Get Started on Your Financial Life Plan Today
