Life Insurance Keeps a Business in the Family

By Trilogy Financial
October 9, 2023
Share on:

In the heart of a bustling town, Ernesto “Peanut” Folks stood as the owner of an auto body repair shop, where years of hard work and dedication had woven into the very fabric of his business. His vision for the future was crystal clear—passing the torch and the legacy of his shop to his son, Ernesto. This is the remarkable story of how life insurance, often overlooked, can emerge as a beacon of hope and resilience when we need it most.

Ernesto “Peanut” Folks was the proud owner of an auto body repair shop, and his plan was to one day pass along the business to his son, Ernesto. Life insurance was never on Peanut’s radar until an insurance professional spoke to him about how it could help him protect the business and its 10 employees.

Downturns in the business would sometimes make it hard for Peanut to make his premium payment. He considered dropping the policy but ultimately kept it in place.

When Peanut was diagnosed with advanced-stage lung cancer, his doctors gave him just six months to live. The treatments that followed kept him away from work, and medical bills mounted.

Given his terminal diagnosis, a provision in his life insurance policy called an accelerated death benefit allowed him to access a portion of the money from that policy while he was still alive. In the months before his death at age 49, Peanut was able to pay off his debts and turn the body shop over to Ernesto, fulfilling his dream.

Talk to an insurance professional about how life insurance can protect your business and your legacy.

Download this comprehensive blog as a concise one-page here: Life Insurance Keeps a Business in the Family

You may also like:

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
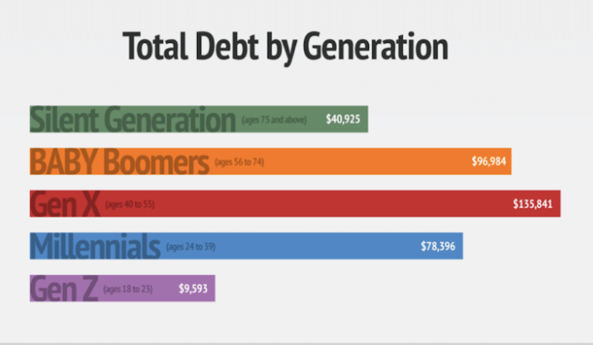
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


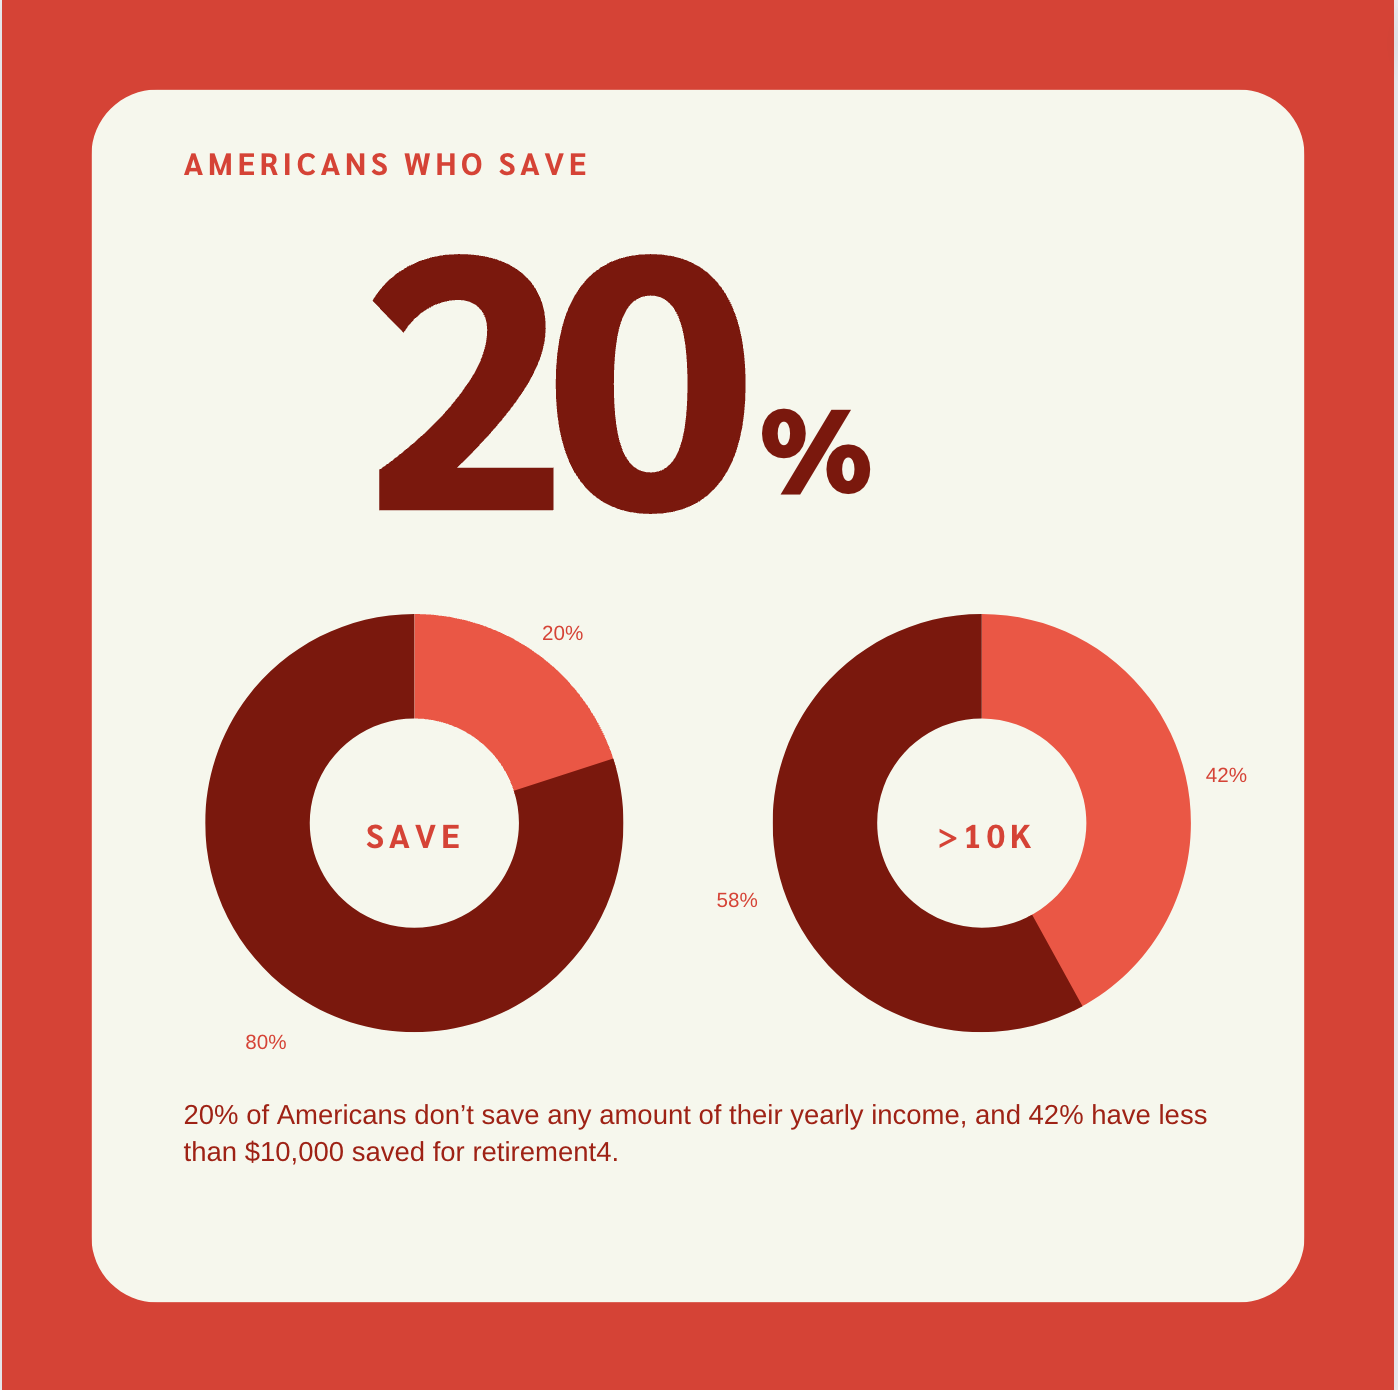
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


By
David McDonough
July 2, 2019

Retirement is a big deal, and there are a lot of moving components to plan out. Those issues multiply when there is another individual added to the mix. My definition of retirement is the financial freedom to move into the next chapter of your life, and that next chapter is different for everyone –especially spouses! This is not the time to assume the two of you are on the same page or decide that the two of you will figure it out later. Most people know that I’m a big proponent of talking to your spouse about everything financial, and retirement is no exception.  Be sure to take the guess work out of this process so you can enter the next chapter of your life in harmony.

It’s not uncommon for couples to not see eye-to-eye on retirement. About half of couples don’t agree on what age to retire[i]. Less than 10% of surveyed couples retired at the same time[ii]. And 47% disagreed on how much they would need to save for retirement[iii]. With so many areas to disagree, from where to retire to how to spend your days, how do spouses work together to achieve their cumulative goals?

I always like to recommend the couples start off by taking my financial compatibility quiz. Not only does this show the areas you may not see eye-toe-eye on, but the quiz generates a lot of conversations. Continue these conversations at monthly financial date nights to make sure that the two of you continue on the same path towards the same goals. Talk about the details – at what age do you want to retire, how do you want to spend your days in retirement, and how much of that time will be spent together. Keep in mind that most people have spent over 40 hours a week away from their spouse for decades. Retirement frees up all that time, which can be too much “togetherness” for some couples. This is why I like to take my clients through a discussion on “your time, my time, and our time,” well before it is actually time for retirement. Discussing these things in advance can allow you to compromise on issues before emotions flair and make a world of difference between living together happily in retirement or, in worst cases, filing for divorce.

Once you have an idea of what your retirement goals are, you need to formulate a plan. An experienced financial planner can be a great resource at this time, bringing up things you may not have touched on and running “what if” scenarios for you to see how your retirement dreams can be converted into actionable goals. Please start these discussions early because financial independence takes many forms, but you can’t figure out when you’re going to get there until you plan your route.

Marriage is many things, but ultimately, it is a partnership. The two of you work together to move the household forward. You may not always agree, but you find common ground by talking and sharing and compromising. If you plan ahead and plan together, you can find the right way to your coupled vision of retirement.

Take our FREE Financial Compatibility Quiz here.

[i] https://www.fidelity.com/bin-public/060_www_fidelity_com/documents/couples-retirement-fact-sheet.pdf

[ii] https://assets.aarp.org/rgcenter/general/retired_spouses.pdf

[iii] https://www.fidelity.com/bin-public/060_www_fidelity_com/documents/couples-retirement-fact-sheet.pdf

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.


Get Started on Your Financial Life Plan Today