Is it time to Re-evaluate your Financial Plan?

By
February 14, 2022
Share on:

Re-evaluating your plan and re-evaluating your opportunities is really important. According to Northwestern's 2020 Planning and progress study, 71% of Americans feel their financial plan could use some improvement. So maybe you have a plan, but you're saying, “Maybe I can use some improvement”. At Trilogy Financial we look at the work that's been done in the past. Remember that we're not judging what was done in the past, but we'll look at that and say, is there any way that we can make improvements upon what's been done in the past to help you plan for the future. Understanding that is really important. A plan is not static, it's a living, breathing document, and you want to make sure that you're updating and reevaluating your opportunities on a regular basis.

Another thing to think about is interest rates is we don't know what's going to be in the future. I think this is an interesting one as well. Many Americans for 2020 stayed at home a lot and a lot of them spent less money. Matter of fact, Northwestern Mutual did a study for 2020 on average, people say it's about 10% more money in their personal savings than they did in 2019. Well, why didn't they spend? Some of it was lifestyle – they didn't go out to dinner as much; they didn't go on their vacations- there’s a lot of things that were held back due to all the craziness that had gone on. But there were people that spent on home improvements in other areas as well. People were spending more on their houses because they were living in their houses more. There's a lot of people that saved more or in that period. You might want to evaluate what to do with that savings. Maybe that's the first step in building out a financial plan. Maybe that's the money that should be put towards the college plan. Maybe that's the money that should be put towards lowering your debt overall. Maybe that's money that you should use to increase your path to financial independence. Re-evaluating your opportunities, your long-term financial plan.

I would highly encourage you to re-evaluate those opportunities again. At Trilogy Financial, we do that all the time. We look at current plans and make sure they make sense. Then when you have extra money that's saved, we look at is it working hard for you and is it working hard for your financial why. Maybe you're in a place where you can refinance. Saving money, and refinancing is another really good tool to help create more cash flow and help you get on that path to financial independence.

I'm big on this thing called Financial date nights. Earlier, I talked about the fact that people argue about money, financial date nights once a month, get out of the house, go do something different. I've had people do financial date drives that live in big cities – go have a cup of coffee, have dinner, whatever it is. Get out of the house and talk about your financial whys, talk about your planning, and talk about your goals. Don't argue about them. This is an opportunity for big picture, global type discussions within the couple and then work through those things. And when you need help and more clarity, that's where a financial advisor can really jump in and help you jump-start whatever is going on in your financial plan.

Another thing is to be flexible and willing to adapt. I said this earlier but good financial plans are living breathing documents. In regard to this, all of our clients at Trilogy Financial have their own portal. Inside that financial portal is their financial plan that updates on a regular basis. We can put paperwork in there or documents in there and it's something that's living and breathing. You may need to be flexible with what's going on in your world. Timeframes constantly are getting adjusted. We've had people come in and say, “You know what? I'm thinking about retiring early” or “My companies offering me an early retirement package.”, or “I have to work a little bit longer” for whatever reason. That's just something you update in the plan. College scenarios too. Some kids are deferring going to college and I don't blame them. You didn't pay for online college, and you may want the experience. If that’s the case, you’d go in a different direction. Whatever those things are, be willing, flexible, and adjustable and in communication with your spouse, your partner, or business partner.

Meet and talk with your financial advisor regularly. They should be asking you those questions and they will be updating you on the markets and current events. what I would say are the unknowns or the instability side. The other thing about having that advisor is that joyful accountability. Have an advisor, have a coach, have a financial team – they'll help you stay accountable to do what you say. They're not going to be bugging you, they're going to be reminding you of the good things that you've said during those planning discussions. They're going to be reminding you where you are and they're also going to be praising you when you're doing what you said you were going to do. And when you do that, you make great progress, and when you make great progress, then the plan progresses year after year after year.

How much closer are we to financial independence, that's the conversations that happen over time. So, take action on what you can do, be in control of your knowns, and plan for the unknowns. Again, insurance is a great thing for that. Work with your advisor on the unknown, so you have less anxiety. Be flexible and will be willing to adapt and remember the financial planning documents and plans are living, breathing documents. Life happens, life events happen, and you've got to plan for those things. If you're not working with a trust or a financial advisor investment fiduciary, look to find one that can help you build your own personal plan.
 

You may also like:

By
Mike Loo, MBA
January 9, 2019

A recent survey found that among Millennial parents, nearly half have received financial support from their Baby Boomer parents in the past year, and 69% received financial support specifically for their own young children.(1) Another poll found that 3 in 4 parents with adult children have helped them pay both debts and living expenses.(2)

Clearly, it is common practice nowadays for parents to provide financially for both their adult children and their grandchildren. Many Baby Boomers are at a place where they are financially secure and have the desire to give their kids a leg up from where they were at the same age. For 2019, up to $15,000 can be gifted from one individual to another without having any tax effects. Many parents are reaching that limit with their gifts to their adult children for their own expenses and gifts to their grandchildren to fund their education and contribute towards their future well-being.

When Your Parents Give You Money

One-Time Gifts

The first thing you have to do is decide what to do with the money. Whether or not it is a one-time gift or will be ongoing will greatly influence your decision. If it is a one-time gift, it likely cannot be used to enhance your current lifestyle. Rather, you could use it to strengthen your current position by paying down debt. You could also use it for a one-time luxury, such as a vacation. Another good use would be to invest it to prepare for the future.

Of course, what you choose to do with the money will depend greatly upon your current financial situation and goals. If you decide to save it for the future, that brings up another set of questions. Where should you put the money? What kind of investment opportunities are available? How soon do you plan on needing it? The answer to each of those questions will determine what you do with the money, whether you put it in a money market account, invest in a brokerage account, or use it to fund your retirement accounts.

Ongoing Gifts

Though they are usually more beneficial, ongoing gifts are actually harder to plan for. You have to ask the same questions as above, but you also have many more options. If it will be a regular gift, you could use it to enhance your lifestyle instead of merely paying down debt or taking a vacation. Or you could use it to take advantage of a business opportunity that wouldn’t be feasible otherwise.

The hard part about ongoing gifts is knowing how safe it is to depend on them. If you make decisions based on the gift, what happens if it doesn’t come or is given sporadically? Many people fear sounding greedy or ungrateful if they ask their parents about money that they expected to receive but didn’t. The dependability of the gift money and the kind of relationship you have with your parents should be taken into account when planning for ongoing gifts.

One thing to be careful of, especially with ongoing gifts, is to not let it affect the stewardship of your own money. It is easy to change good habits and loosen the reins on your spending when you have extra money coming in. But is that wise?

Your parents are giving you money because they want to help you. Are they really helping you if you are simply becoming more careless? You should apply the same careful money habits as you would without the gift, even if it creates enough margin where you wouldn’t have to. Remember, what your parents give you is a gift. It is not required nor guaranteed, and you should manage it with that in mind.

When Your Parents Give Your Children Money

A lot of the same issues apply when your parents gift your children money or give it directly to you but for their benefit, especially when you aren’t sure if the gift will be regular and are not comfortable asking.

First, you need to decide if you should use it to meet current needs or future ones. If you save the money for your children’s college education, it could help them pay for a better school, get a better job, and avoid student debt. But if the money is spent today, it could pay for their childcare and thereby enable you to save more for retirement or get a house in a better school district, which could lead to a better education, admission to better colleges, and scholarships to avoid debt. There is no one right answer and it requires careful consideration of your family’s own unique circumstances and priorities.

College Funding

If you do decide to save the money for your children’s future, that brings up another host of questions. Where is the best place to put the money until you need it? A savings account? A 529 Plan? An UTMA? The answer will depend on a number of factors, including how liquid you want the money to be without penalties and how much control you want to maintain over the money. There are a number of options available to you, each with its advantages and disadvantages.

When saving for college, you need to have a target goal in mind. It is important to estimate the cost of college for your child in order to measure how much you need to be investing, the types of investments you should use, and to monitor your progress. Another reason to have a set goal is to avoid overfunding a college account. There should be a stopping point where you no longer invest in a 529 but rather divert the funds elsewhere. While leftover 529 accounts can be transferred to family members or have the funds removed with penalties, it may be better to simply avoid overfunding them in the first place.

Multiple Children

Having multiple children makes things even more complex because it can be hard to keep things fair and equitable. What happens when your parents, who gave a lot towards your firstborn, begin to taper off the gifts with subsequent children? Or perhaps the same amount was given, but it was divided by more and more children? What can you do so that the later children are not at a disadvantage?

Also, what happens when the gifts begin after you already have more than one child? If your parents start funding a college account when your first child is 5 and your second is 1, then the second may end up with a much higher balance upon entrance to college. What can you do and what should you do to help balance things out?

How I Can Help

These are some of the questions that arise when parents gift money to their adult children and grandchildren. Depending on the scenario, things can quickly become complex. Not only do you have to decide what to do with the money, weighing the benefits and opportunity costs, but you have to decide the best way to accomplish your goals with that money.

This is a common situation that my clients find themselves in when they turn to me for help. Together, we first determine the circumstances in which the money was given and the intent behind it. If your parents had a specific purpose in giving you the money, it is often best to honor that purpose.

Next, we discuss how you can use the money in a way that doesn’t distract you from your goals or cause you to become financially irresponsible. We talk through different scenarios in advance and address the “what-ifs” that could occur in each in order to develop a solid plan. My clients really enjoy having me there as a sounding board to bounce ideas off of, as well as to hear my insights based on the experience that I have had myself and with other clients.

If you’ve found yourself the recipient of financial gifts from your parents, or just need someone to help you sort through your own finances, call me at (949) 221-8105 x 2128 or email me at michael.loo@lpl.com. I would love to partner with you so that you can make wise financial decisions to build a secure future for you and your family.

(1) https://s1.q4cdn.com/959385532/files/doc_downloads/research/2017/Millennial-Parents-Survey-Key-Findings.pdf

(2) https://www.creditcards.com/credit-card-news/pay-adult-childrens-debt-poll.php

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


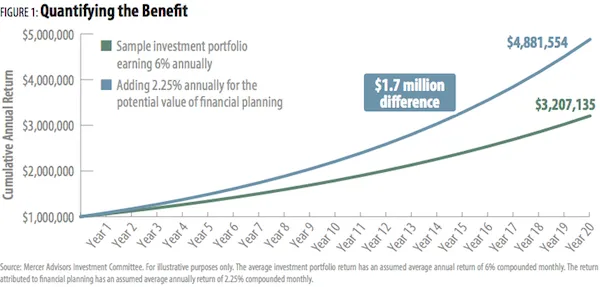
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


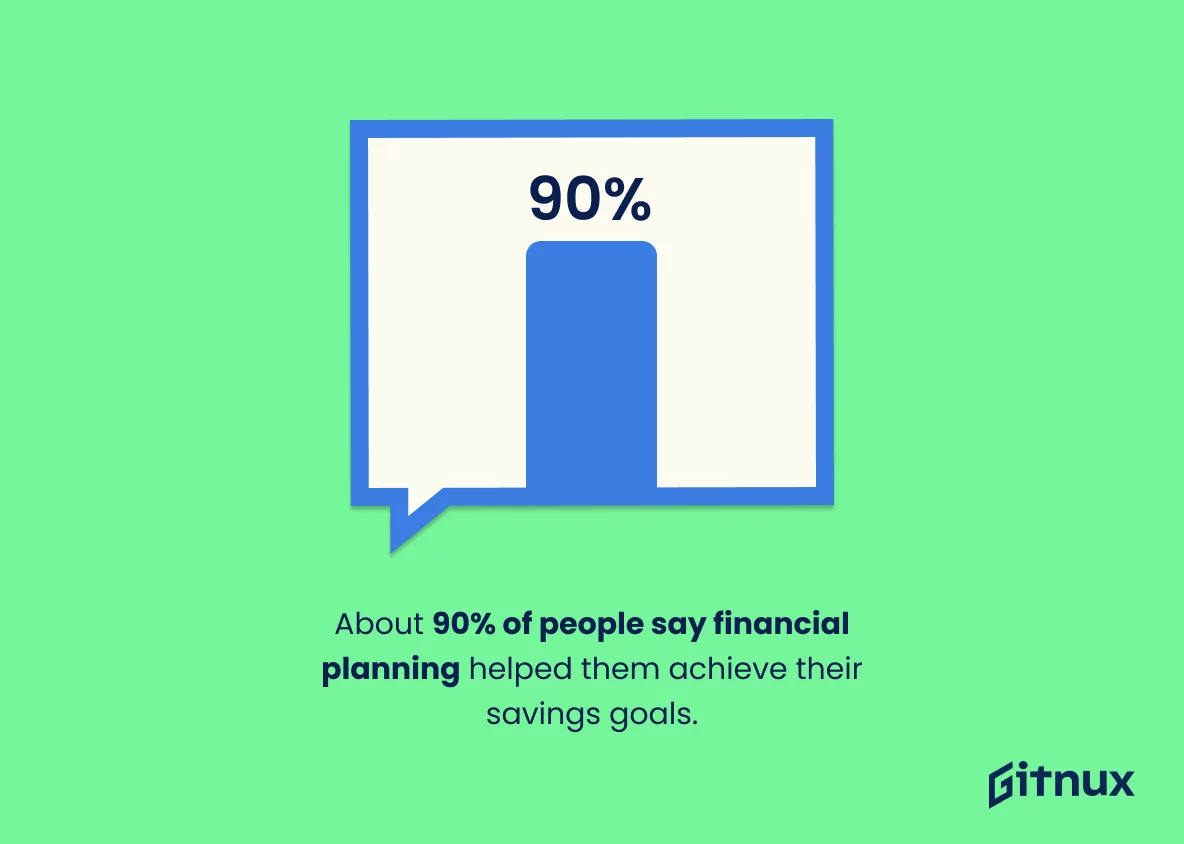
Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


Get Started on Your Financial Life Plan Today