

How Strong Are Your Passwords?

By
May 10, 2022
Share on:

How long do you think it would take a hacker to crack your current passwords?

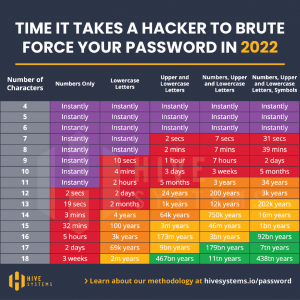
On average, it takes a hacker about 2 seconds to crack an 11-character password that only uses numbers. See the attached chart that illustrates the time it takes for a hacker to brute force attack your password. A brute force attack is when cybercriminals use trial and error to guess your details. Cybercriminals currently use sophisticated software that can run thousands of password combinations in a minute, but their technology and resources are only getting stronger.

A general rule is that your password should be at least 11 characters, utilizing both numbers as well as upper and lowercase letters. That combination will take hackers 41 years to crack. Regardless of the possible variations, the shorter your password, the easier it is to crack. Check out how long it will take a hacker to crack your password at https://www.security.org/how-secure-is-my-password/.

Lastly, simplify and secure your accounts by using a password manager that creates and stores all your passwords for you.
Strengthen your password security with the following tips:

  • Prioritize the length and complexity of your passwords.
  • Don't use personal information. This can be publicly available and easily accessible by hackers.
  • Avoid using dictionary words as passwords. Cracking tools can easily process every word in the dictionary.
  • Don't reuse passwords. If one account is breached, your other accounts would be vulnerable as well. Rather, use password managers, which are a convenient and secure way to manage complex passwords on multiple platforms.
  • Use multifactor authentication (MFA or 2FA) for especially sensitive accounts.
  • Avoid typing passwords while using public Wi-Fi. Instead, use a VPN or avoid websites that require your login information.




You may also like:

By
Jeff Motske, CFP®
December 7, 2018

Giving to charitable causes can be a very emotional thing. You’re supporting something near to your heart, possibly with a deep personal connection. However, if you’re not mindful, it is possible to give at the expense of yourself. Be sure you don’t let your heartstrings control your purse strings.

Forethought and planning should extend over all your financial decisions, including charitable giving. For a variety of reasons, many don’t follow a plan. Some give whatever’s left in their budget, perhaps not as much as they’d like or tempting them to give more than they can afford. Others give at the end of the year for the tax break. Alternatively, perhaps charitable giving isn’t planned for at all, which allows one to be swayed by emotion when the right cause comes along. Suddenly, they can be committing based on what they feel rather than what’s best for their finances.

Once you decide to factor your charitable giving into your annual financial plan, you can start doing your research. Not only do you determine which causes you want to support, but you can also investigate various organizations that service that cause. There are many websites that evaluate charitable organizations to ensure that your financial contributions or going where you want. Additionally, having your charitable giving worked into your financial plan allows you to turn down other charitable requests graciously. Should you be approached, you can mention your annual giving plan and that you will consider them for the following year.

Being mindful about your charitable giving also gives you the opportunity to influence your children or loved ones on how to do the same. Your actions become the example to your values. While you needn’t share all the details, you can openly share how you formulated your plan and why. The more people who become aware of how to consciously create an annual giving plan, the more people are actively working towards their financial independence.

I don’t think it’s possible to take all emotion out of your connection to a charitable cause, and I don’t think you should. However, I will always be an advocate of folks proactively working towards their financial independence. The key to that is approaching your finances with reason and logic, relegating our emotions to the backseat and holding firm to your purse strings.

By
Zach Swaffer, CFP®
February 19, 2019

We all know we should save more. We all want to save more. Yet, month after month we face the same Groundhog Day scenario: paying all of the bills only to realize that – yet again – there is simply nothing left to save. Sound familiar?

Think about it for a minute. In our Groundhog Day scenario, you are dutifully paying every creditor in your life except for the most important: yourself! It’s time to change the narrative: moving forward, think of saving money as paying yourself. You spend all month working hard. You deserve to keep some of the compensation for that hard work. You on board? Great! To keep you honest, we’re going to set up automatic contributions.

Automatic contributions to savings or investments are a crucial step in building a stable financial foundation. Establishing automatic transfers tied to your paycheck schedule ensures that you will pay yourself for all of your efforts at work and invest in your future. It codifies the “pay yourself first” mentality and aligns your monthly spending with your available discretionary income. For example: if I see extra money sitting in my account, I’m likely to splurge on a fancy meal, or buy a plane ticket to visit my sister. Then the end of the month rolls around, and there is no money left over for saving and investment. On the other hand: if I never see the money in my account, I don’t miss it!

By paying yourself first (saving as money comes in), you will see less money sitting in your account and, accordingly, you will spend less. Over time, you won’t even notice the money being set aside. Your spending habits will have auto-adjusted to your new, post-savings cash flow. (I promise!)

One of the best parts of a “pay yourself first” system is that you don’t have to feel guilty about spending the money in your checking account. Having automatically set aside your monthly savings, you’re free to spend the rest of your money as you wish! Regardless of your balance at the end of the month, you can rest easy knowing your financial foundation is secure.

As a financial advisor, I find a “pay yourself first” savings model to be far more successful than any strict budgeting system. Budgets require line item expense tracking and don’t adapt easily to unexpected expenses. Establishing automatic transfers to “pay yourself first” allows you to maintain a more flexible budgeting system – while still sleeping well at night knowing that your saving objectives have been met.

If you would like to talk about establishing an automatic savings plan or your personal situation please contact me at zach.swaffer@trilogyfs.com.

Get Started on Your Financial Life Plan Today