How An MBA Prepared Me For My Career As A Financial Advisor

By
July 20, 2018
Share on:

Over the course of hundreds of conversations with clients, I’ve found that quite a few them have wrestled with the idea of whether they should go back to school for an advanced degree. As their advisor, I am commonly asked if returning to school would be financially beneficial. The risk/return analysis is not always cut-and-dried in this situation. Investing X amount of dollars in a degree program does not always result in an equal or higher return in the future.

The True Value Of Education

Education is about more than just the money. After a recent conversation with a client, I had the realization that while I don’t need an MBA for my job as a financial advisor, the MBA experience itself shaped and molded me to become the advisor I am today. While I did take numerous finance classes to enhance my knowledge and quantitative skills, the greatest value I gained from earning an MBA came from improving qualitative skills, such as working with people, networking, effective communication, and time management. These are skills that I use daily in my current role.

Every experience we go through, especially those that push us out of our comfort zone and require plenty of work and time, leads to personal growth. Had I not gone through the MBA program at USC’s Marshall School of Business, I might not have developed the work ethic required to succeed as a financial advisor, and I could have ended up on a completely different career path altogether.

My Pre-MBA Self

Before entering the MBA program, I had a passion for the financial services industry, but like most college grads, I wasn’t sure how that would translate into a career. I didn’t have a clear direction for my future. I was interested in becoming an advisor but knew that it would be fairly tough to advise people on what to do with their finances when I hadn’t gone through many life experiences myself.

I had always loved the idea of making money and becoming more efficient with what I had, but I was young and dumb (and willing to admit that)! I fell into the cultural mindset of wanting to work typical business hours, earn a large salary, and enjoy life. In essence, I wanted the rewards but didn’t want to do the work involved to achieve those rewards. In my naive way of thinking, an MBA seemed to be the simplest path to achieve this end result. I can tell you that I was so wrong in this assumption!

What I Gained from My MBA

Networking Skills: USC is known for networking. Everything I heard about business school prior to attending was that the most important takeaway from the experience is to network, network, network. Unfortunately, my pre-MBA self was uncomfortable talking with people I didn’t know. I didn’t like to take the initiative to introduce myself and sometimes avoided conversing with people unless I was introduced first. As time went on and I experienced the pressure of competing against my peers and other highly qualified candidates for the same jobs, I was forced to rise to the challenge and become comfortable with being uncomfortable.

This skill alone has helped me immensely in my career when it comes to collaborating with a client’s other professionals, such as an estate attorney or CPA. In order to do a thorough job for a client, it’s often necessary to work with their other professionals to make sure we’re on the same page. In many cases, I’ve reached out to a client’s CPA to make sure they had my contact information so that if questions arise about the client’s investments, they call me rather than my client.

This skill has also helped me in reaching out to client referrals or prospective clients because I’ve found that people often want help with their financial planning, but they might not tell others or take the first step.

Effective Time And Task Management: During my time at USC, multitasking became the norm. If I wanted to effectively balance school, attend recruiting events, revise my resume, participate in mock job interviews, network for potential jobs, and somehow find time for a personal life, I had to become better with time management.

My job today is multi-faceted and includes juggling many tasks, such as answering client questions, servicing and monitoring their accounts, staying on top of changes in the industry, and dealing with changes life throws my clients’ way. Knowing that I was able to handle my heavy load in the past gives me confidence that I can prioritize my work today. Most importantly, I’ve come to realize that with all of these moving parts, it’s impossible to be rigid in only working business hours (again, something I aspired to when I was young and dumb), because not everyone is available from 8 am to 5 pm. Instead, I’ve become flexible with my schedule and instituted taking a day off during the week so that I can occasionally meet with clients on the weekend or do a phone call later in the evenings.

Is An Advanced Degree Right For You?

In my case, obtaining an advanced degree was one of my best decisions. It’s difficult to imagine doing anything else with my life and I am fortunate that I went down this path. If you or someone you know is trying to make this decision, I would love to give you some insight and help you look at the situation from an objective perspective. Or, if you would like to network and see if we could work together, call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com. I’d love to see you thriving in your life!
You may also like:

By
Mike Loo, MBA
August 30, 2018

Whether we attribute it to a decline in marriage rates, poor job prospects, student loan debt, technological improvements, or generational shifts, times have certainly changed for young adults. One major topic which my clients bring up centers around their adult children moving back home. While this was not a common conversation ten years ago, I come across this topic more often nowadays. I’ve heard statistics such as “a third of young people, or 24 million of those aged 18 to 34, lived under their parents’ roof in 2015”, and look at it as my job as an advisor to provide advice on how to best navigate through this new landscape.(1)

Within this topic, a common question that I try to help my clients answer is this: Should I charge my adult children rent if they move back home? What I’ve found is that every situation is different, so what may work for one family, may not work for another. However, in this article, I hope to provide a framework to consider when trying to answer the question.

Setting Expectations

Depending on your own experiences and values as parents, as well as the specific circumstance of your adult child, you may insist that they live at home rent-free. For example, if your adult child is being responsible by saving a good share of his/her paycheck for a house down payment and you want to reward that responsible behavior by letting him/her live at home rent-free, there’s absolutely nothing wrong with that. For other parents, such an assistance for an adult child does not make sense, and no matter what the circumstances, would believe it only right to charge for rent if living at home.

No matter where you fall on this spectrum, it is important to set expectations with your adult child. For instance, if you decide that it is out of your comfort zone to charge your child rent for living at home, then what other mechanisms can you put into place to make sure he/she does not get too comfortable? In my experience, I’ve seen parents create timelines and goals, as well as make it crystal clear that the adult child must still pitch in, in other ways such as chores or errands. While it may be a tough conversation initially, imagine the alternative. What if your child gets too comfortable living at home and would rather stay at your “hotel” rather than spread their wings in the real world!

Whether rent is being paid or not, the adult child will have a particular reason as to why they want to or need to live back at home. If they are simply being lazy and are not making an effort towards adulthood, it is crucially important to provide clear expectations. As parents, you want to always help and support, but you never want to enable. Therefore, in this example of being lazy, a parent could set expectations of applying for X number of jobs per week, or something similar.

How Much To Charge For Rent

If you do decide that it makes sense to charge your adult child rent, how much should you charge? In my experience, parents usually charge well below market rates. As parents, you want to help your child out, but you also want to build up their personal finance awareness. How much you charge will also be highly correlated to what your daughter or son can afford, and could change over their time living with you. By having an open conversation and being clear about why you will be charging them, it should not be hard to fall on a number that makes sense for your family.

Alternatives

There are also other ways in which your adult child could pitch in that could be alternatives to paying rent. Such alternatives could be household chores or errands, cooking meals, or even helping parents with their own work. In addition, it could make more sense to have your adult child pay for other household expenses (instead of rent), such as internet, tv, or groceries.

Another alternative could be to make their stay at your home contingent on them depositing money into their own retirement account. This way, you are teaching them how to save and plan for the future.

Finally, if you want to help them grow personally, you can make their stay at your home contingent on community service or volunteering. This is a win-win as well!

Budgeting

This experience can also be thought of as a great teaching moment for your child. Specifically, parents in this situation are in a unique position to extol the virtues of budgeting and personal finance when their child needs it most. If the adult child in your household has to pay you rent and decide how to allocate their small-to-no income, they will quickly learn how to budget. As a parent, you may decide to get creative and instead of using the rent money for expenses, stash it (and maybe even match it) into a savings account for your child. They will be happily surprised with a small nest egg to leave home with!

Other Considerations

Other considerations that I make sure clients consider is their own budget and retirement goals. If your adult child is going to come back home and live there, you’ll want to make sure that adding another adult to the household does not negatively affect your own goals. Because you’d anticipate that household expenses will go up, you must make sure you budget for them, based on your expectations and timeline with your adult child. Again, by having an open conversation with your adult child, I am confident that a reasonable game plan can be implemented with success.

Having this conversation is not always an easy one, but I hope that the considerations above help provide better ways to think about it. If you’d like to discuss your situation further, call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com.

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
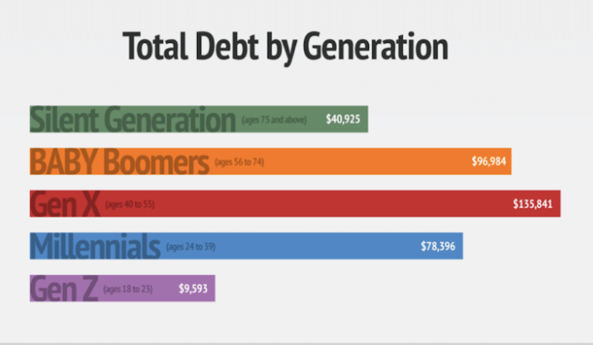
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


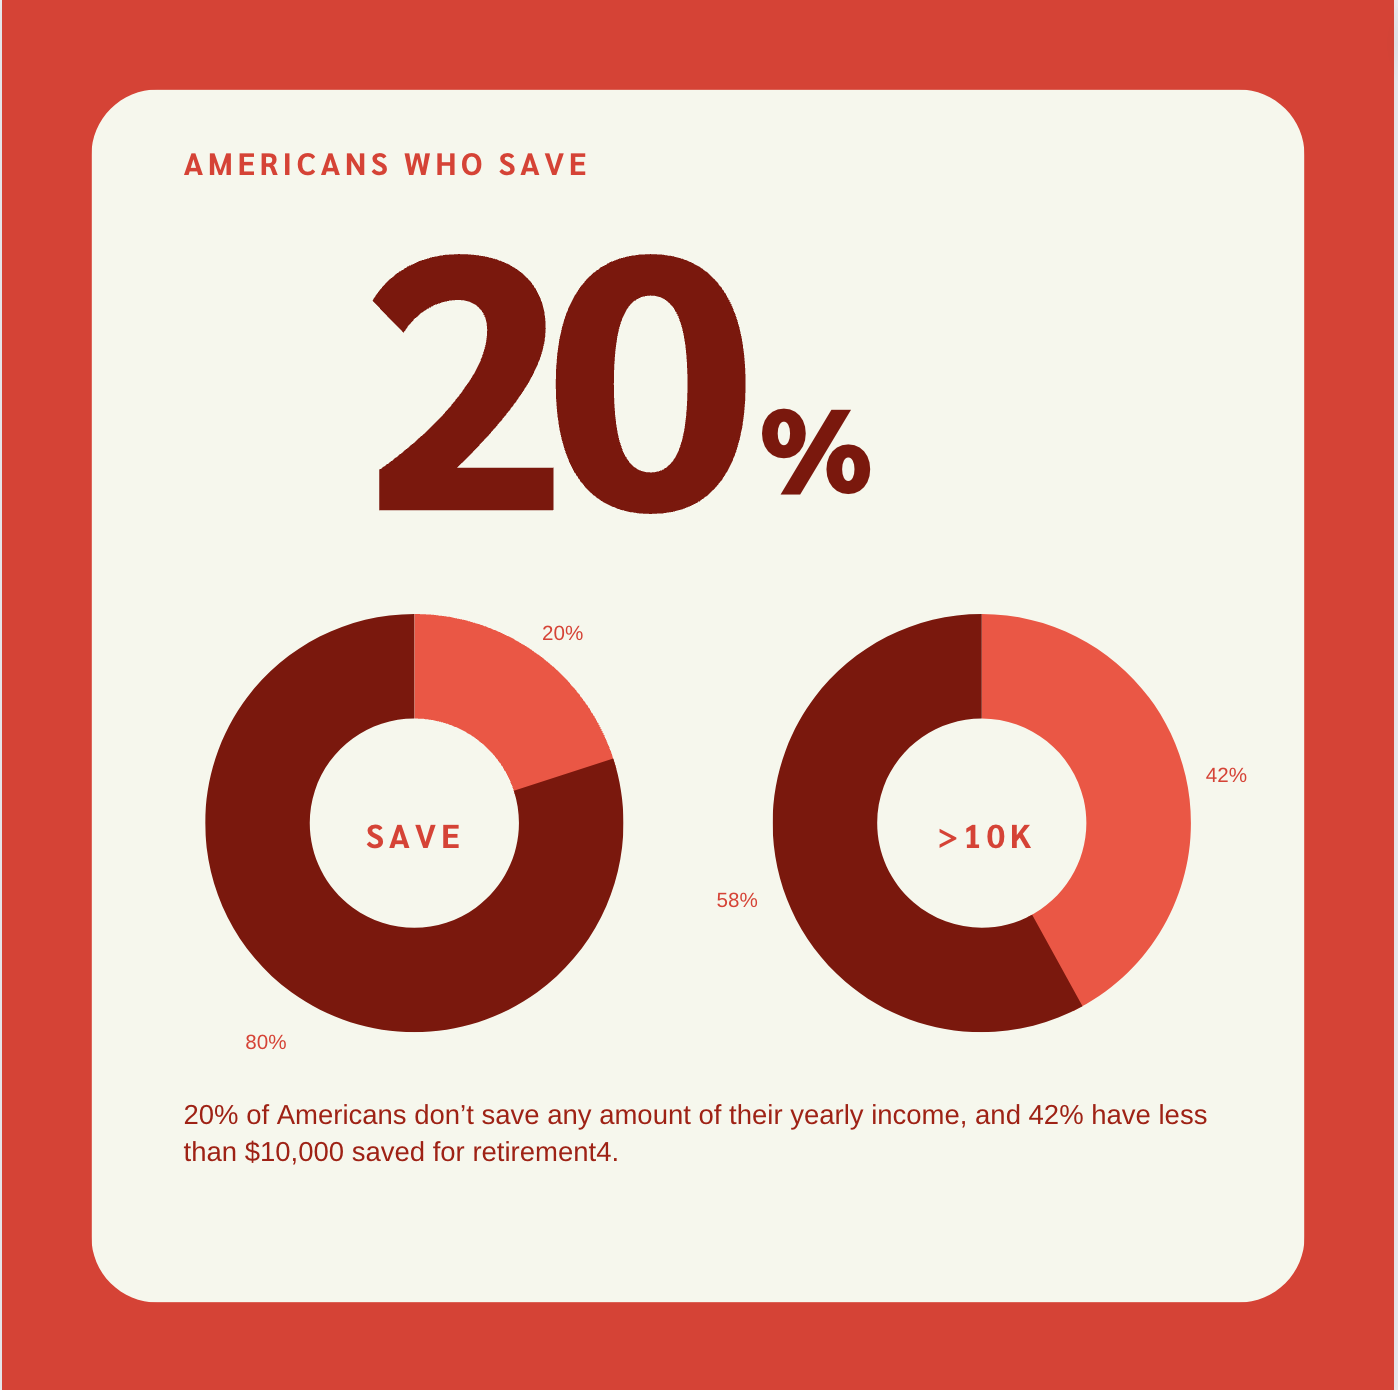
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


Get Started on Your Financial Life Plan Today