How A Fiduciary Can Help You Through Financial Planning

By Trilogy Financial
November 11, 2023
Share on:

Many Americans spend more hours than they’d like managing necessary financial components of life while balancing caring for a family, performing at work and enjoying time with loved ones. Despite working hard to try to strike a perfect balance, financial planning, saving and investing can be tedious and time consuming, and maybe even daunting.

This is where a fiduciary comes in.

________

What Is a Fiduciary?

The term fiduciary is thrown around in the financial services world, but few people truly understand it.

A fiduciary is a person or organization that acts on behalf of another person or persons, and puts their clients' interests ahead of their own. A fiduciary has a duty to act in good faith and serve clients by earning trust and confidence. Being a fiduciary thus requires being bound both legally and ethically to act in the client’s best interests.

To the Financial Advisors at Trilogy Financial, it’s more than that. Yes, we believe “fiduciary” means putting clients best interest before our own. However, we take it steps further to demonstrate with evidence that our proposals are in the client’s best interest. The evidence, be it in a financial planning concept or investment strategy, is the key to being a fiduciary.

Why Is It Essential To Work With a Fiduciary?

When a fiduciary presents evidence that their proposals are in the clients best interest, it leads to confidence. That confidence leads to good financial decisions over time. As Life Planners, that is what Trilogy’s Financial Advisors are working towards.

A fiduciary's main goal is to help set clients on an upright financial track through financial behavioral coaching, accountability and to help clients develop a Life Plan. A financial advisor and fiduciary will also help you prepare for retirement by maximizing the profitability of resources directed towards saving plans, develop estate plan strategies and more.

As Advisors, we anticipate individual’s or family’s needs over time, which allows us to be a better fiduciary. We believe a true fiduciary guides clients through life’s roughest patches and toughest situations.

Let a Fiduciary Be By Your Side When Life Planning

Let’s face it…a fiduciary can help ensure your financial goals are aligned in the same direction as your ambitions. Right? Proper financial planning requires objectification of your goals through the hands of an excellent financial partner who can help you with the following.

Help you save for retirement

For many, having $1 million worth of liquid cash and a list of profitable assets by the time they retire is a dream come true. However it’s a difficult dream to work towards for many Americans. That’s where a fiduciary comes in.

The secret to getting the retirement and lifestyle you dream is preparedness and time. The earlier you begin to save, the better. Beginning early allows you to make small contributions that will accumulate to a lump sum amount over a long period. For instance, if you start saving $5,000 every year from your mid-20s, by the time you are 40 years old, you will mostly likely have crossed a quarter a million mark. Remember, you will still be young, energetic, and even determined to save more. Because compounding is so powerful, if you continue saving the same amount by the time you are 65, you could be almost at $1.5 million, more than what you had intended to save.

In contrast, if you start saving at 35, even if you double that amount to $10,000, you may stagnate at $840,000 by the time you hit retirement age. So, the earlier you begin to save, the more you will receive at retirement. But do not be deterred if you are starting later in life. With the right planning, it’s never too late to achieve your goals. A Trilogy Financial Advisor can develop strategies to compound savings through investments and other growth opportunities.

Save for education stress-free

According to Market Watch, an average American will spend over $58,464 on their child's education from primary school to the undergraduate level, doubling the UK's average spend and tripling France's. Now imagine you are the head of a typical American family with more than 3 dependents; you will need almost $200,000 for education alone.  This is a huge dent in a family's finances. Fortunately, a fiduciary can help you save for education and college. Saving about a third of your earnings for a decade with the purpose of spending it on education will take the pressure of school fees off your shoulders.

Grow your wealth

The potential of growing your total net worth is an exciting process. Our Financial Advisors help you to navigate investment opportunities and mitigate risk, serving as guides as you work to grow your investments. At Trilogy Financial, we believe investing is about more than positive returns. Growing your wealth is a tool that can help you achieve financial freedom and live the life you’ve dreamed of. A fiduciary can coach you through building out the investment portfolio that aligns with your unique goals, and empower you to make the meaningful decisions to pursue your life dreams.

Plan your estate strategy

Due to the complex nature of estate planning, estate strategies should be tailored to your unique needs. And each strategy should aim to protect and preserve your assets for future generations.

Regardless of the value of the estate, a fiduciary will help you plan for the estate by:

  • Ensuring your beneficiaries receive what you’ve planned for them after you pass
  • Planning for lifetime gifts through trust and minimization of diminishing estate taxes
  • Helping you to pass assets or a business to your younger generations
  • Identifying powers of attorney to ensure your wishes come true


Trilogy Takes a Bold Financial Approach

For us, care is at the center of everything we do as fiduciaries.. We care about each client like they’re an extension of the family. Every day, with every piece of advice, we empower our clients to live wealthy. Ready to explore the benefits of working with a fiduciary? Review Trilogy's Financial Life Planning Tool to see some of the areas of focus we’d suggest on the path to financial freedom.

Bottom Line

A fiduciary helps you make critical financial decisions that are in your best interest, for your Life Plan. Our Financial Advisors work with clients nationwide. Regardless of your location, we have an office nearby or a virtual way to connect from the comfort of your home.

Start Life Planning today.

Fiduciary investment advisory services are only offered through Trilogy Capital (TC), a Registered Investment Advisor. TC markets advisory services under the name of Trilogy Financial (TF), an affiliated but separate legal entity. TC and TF are separate entities from LPL.
You may also like:

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
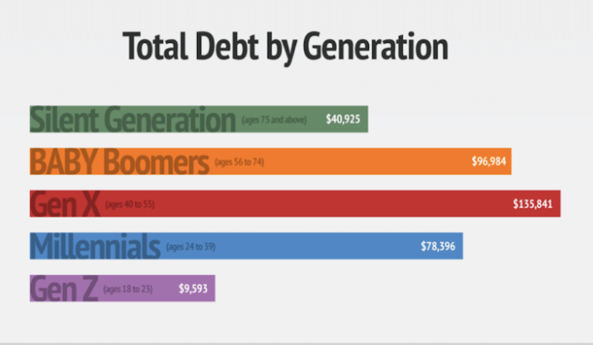
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


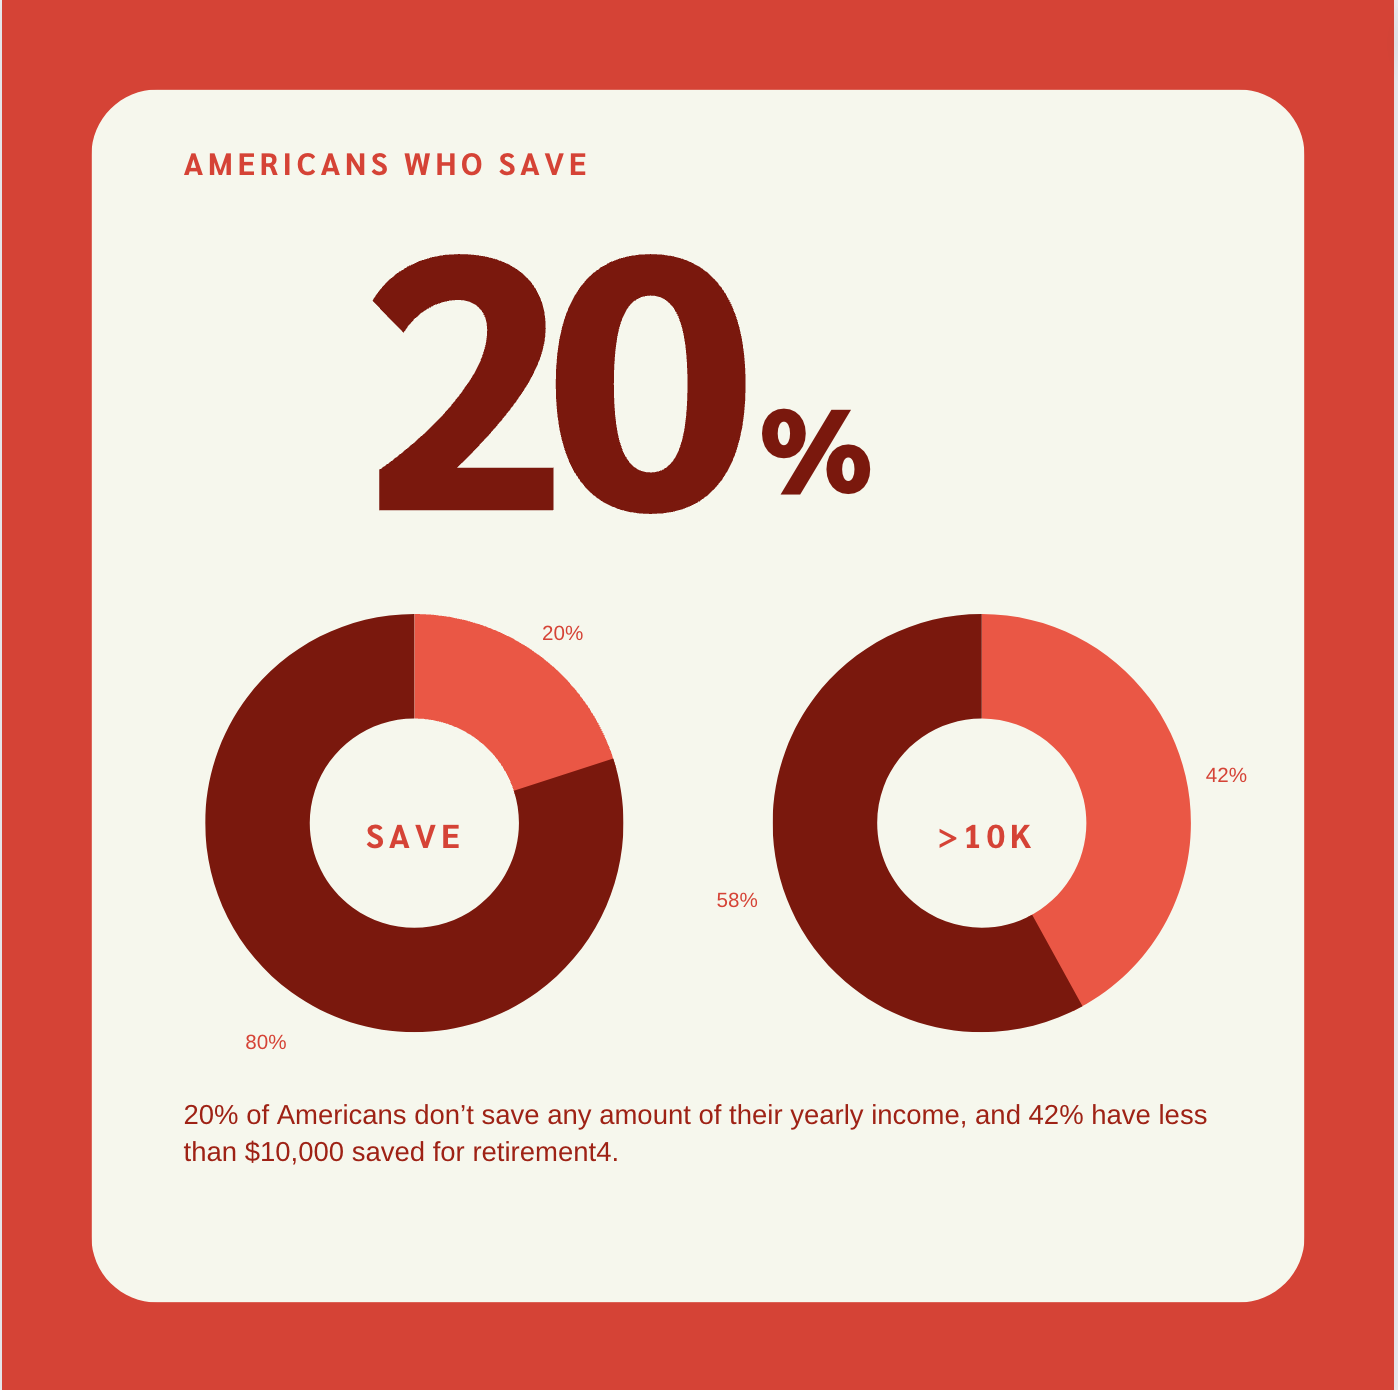
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


By Trilogy Financial
July 23, 2019

Like many in my generation, I prefer to subconsciously minimize the odds that I’ll become ill and ignore the reality that I’ll eventually pass. Unfortunately, the harsh reality is that illness and death are inevitable. Enter another subject we tend to ignore: Life Insurance. For many Americans – particularly young and/or single adults, life insurance is nothing more than a plot point in a Hollywood movie or true crime drama: the money collected by remaining relatives after someone has passed. However, life insurance, like health insurance, is just something you need to have. It can provide financial security for your loved ones, cover end of life expenses, and can even provide tax free income.

There are two different types of life insurance: temporary and permanent. The most common form of temporary insurance is Term insurance. Term typically lasts for a specified “term” of years, hence its name. Permanent – on the other hand – stays with you for your entire life, provided you continue to pay the premium, or have developed an account value large enough you no longer have to pay in. There are a wide variety of insurance policies available under the permanent life insurance umbrella, such as: whole life, universal life, variable universal life, and indexed universal life.

To put in another way, Term insurance can be thought of as renting insurance. You pay a monthly premium for the coverage but once the specified term of time is up that coverage goes away. The term can vary from 5 years up to 30 years. With some companies you can continue the policy, but you will have to pay premiums that are a multiple of what you had been paying during the “term” of the contract. It is used to provide protection for liabilities that will disappear after a certain time period ex: raising children, your mortgage, or income replacement. In your 20s-50s you have more people depending on you; therefore, if something were to happen to you (e.g. illness, death) you need an insurance policy that will take care of the people you support. If you pass away, you need enough coverage to pay off any existing debt, provide income replacement, and cover any other miscellaneous expenses associated with supporting your family. This coverage makes a difficult time a little bit easier by reducing the financial burden and allowing loved ones time to grieve without worrying about impending bills. Term insurance is perfect for this type of coverage as it has the lowest premiums and can be structured to disappear once certain liabilities disappear (e.g. mortgage is paid off, kids are out of the house, and your income is no longer critical to the security of your family).

Permanent Insurance, on the other hand, can be framed as owning the insurance coverage. As with term insurance, you pay a monthly premium; however, the coverage stays with you for the rest of your life, not just a specified term of time. Once your family is out of the house and your liabilities are decreased you still want to maintain some level of insurance coverage to cover end of life expenses and provide for loved ones. Permanent insurance is a great choice to cover these remaining liabilities. The premiums for permanent insurance are higher than those for term insurance because, unlike term – where the insurance company may not ever have to pay out the policy- permanent insurance means a guaranteed payout – assuming you’ve paid the premium. At some point the insurance company will have to pay. Additionally, part of these monthly premiums are placed into a cash value account which, depending on the type of policy, earns a fixed or variable rate of return and can provide tax free income. This income can be used to fund an early retirement as it can be accessed prior to age 59 ½ – the age required to legally withdraw from retirement plans without incurring penalties.

But what if you want to access the death benefit in an insurance policy without having to die – sound too good to be true? In fact, some insurance policies allow you to access death benefits before actual death! These policies feature Accelerated Benefit Riders (ABRs) which allow you to accelerate (or, in other words, use) the death benefit while still alive to cover certain terminal, chronic, or critical illnesses. Unlike health insurance, which only reimburses medical expenses, ABRs provide tax free money for you to use as you wish, assuming you have an ABR event. You can use this money for experimental treatments that health insurance will not cover or use it to travel the world. There are no restrictions on how the money is spent.

Now you know about life insurance and the many different options and benefits available to you – consider working with a financial planner to discuss the right life insurance policy for your needs.

If you have questions about insurance or any other aspect of your financial life please do not hesitate to reach out to me at zach.swaffer@trilogyfs.com

This article contains only general descriptions and is not a solicitation to sell any insurance product or security, nor is it intended as any financial or tax advice. For information about specific insurance needs or situations, contact your insurance agent. This article is intended to assist in educating you about insurance generally and not to provide personal service. Guarantees are based on the claims paying ability of the issuing company.

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Get Started on Your Financial Life Plan Today