Diligence by Who? You or Your Financial Advisor?

By
August 22, 2018
Share on:

Recently, I followed up with a client after the client had been away on a family vacation for two weeks. Prior to that trip, the chaos of summer, work travel, and meetings had prevented the client from following up with me on a minor but impactful recommendation I had encouraged the client to consider in our last conversation. Before I had the opportunity to even say, “Hello,” the client apologized and communicated that I was owed a phone call. Yes, I had encouraged a decision knowing the impact would further strengthen the client’s financial situation, but in my diligence, I didn’t expect a phone call. The definition of diligence: careful and persistent work or effort. I love the simplicity of this definition and the use of the words persistent and effort. From knowing the client, I know the client is incredibly diligent in her own work and personal life. You see, when my client picked up this phone call, and the diligence of my follow up had just replaced the client’s call, eased the burden of the client having to call me back (amidst her intense work schedule), and ultimately resulted in the client making a best decision to improve the efficiency and effectiveness of her plan after re-clarifying the client’s priorities and current time frames.

An ongoing and sound financial plan requires an immense amount of diligence. If you are not ready to double down on this level of diligence on your own, why not hire a Decision Coach and Certified Financial PlannerTM professional to sprinkle the entirety of your plan with some diligence? Have you rebalanced your 401(k) lately? Have you increased your contribution percentage after your last raise? Did you update your life insurance planning after you moved into a new home after your second child was born? Are you planning on saving for that dream trip to Europe, or is that just going to magically happen in the next five years? What are the trading fees on your brokerage account? You have given thought to each of these questions. You have even discussed the answers with your spouse or close friends. Yet, you are busy and these action items are on the top of your priority list on a Tuesday. All of these questions require thoughtful planning with ongoing diligence, communication, and action. As soon as you settle into a plan with the right cash flow, life happens and you will need to adjust the game plan. My client didn’t forget to call me back. My client wanted me to call me back. Yet, my client didn’t call me back and didn’t make up her mind, until I called. Was I upset that I had to follow up several times? Was I frustrated my client seemed non-responsive? Of course not! It’s my career and joy as a Decision Coach. It’s part of my role as your financial planner to be diligent, to hold you accountable, to help you make qualitatively better decisions over time. Do I expect this to take a few follow up calls and three incredibly productive and ongoing quarterly progress checks between annual reviews? Of course! I love crafting a game plan for you. I love when you approach a financial decision and prior to making a decision, you reach out to me. I want your plan to be dialed in, so ultimately, you are living the life you want now, saving for the life you want in the future, as I provide the guard rails of diligence all along the way. A lot happens in a year and all of those little decisions have a significant impact over a long arch of time. Why I am so diligent with your financial plan? So, you don’t always have to be…don’t apologize, let’s just make the next best decision together and I’ll handle the follow up so we can one day celebrate together, not just because you are retiring, but because of the life you lived to get there.
You may also like:

By
Mike Loo, MBA
September 28, 2017

The world of financial planning is so incredibly diverse. And so it is with financial professionals, as well. The challenge that most people have is that by not being familiar with the various types of advisors; styles, approaches, licenses, abilities, qualifications, etc., it makes it hard to know what questions to ask in order to formulate an opinion as to whom to work with. People tend to go with their “gut feelings” about someone. And while that certainly can be an indicator as to what kind of working relationship one might have with a particular financial professional, it is equally, if not more, important to have objective information at hand for that decision-making time, as well.

There are a few questions that advisors rarely get asked, but should be asked. Sometimes these questions get avoided because the person asking might not even realize these questions are important. Past experiences drive many of the questions people ask. But if the goal is to be as informed as possible, it’s important not to forget to ask these three questions:

Question #1: Are you a fiduciary? And how do you get paid?

Not all financial professionals are fiduciaries. There are various types of securities registrations a financial professional can acquire; some are simply registrations to sell certain products, some are registrations to give advice (as opposed to just suitable recommendations for product sales). In other words, some financial professionals are “Registered Representatives (RR)” who are affiliated with a broker/dealer, with some securities registrations that allow them to sell products. While some financial professionals are “Investment Advisor Representatives (IAR)” who are affiliated with a Registered Investment Advisory firm, who have a few more/different registrations that allow them to be fiduciaries within the advisory services they offer their clients. Some professionals are both a Registered Representative and an Investment Advisor Representative. Others are not. Many consumers don’t know the differences. Below is a very basic breakdown.

Responsibilities to Client:

IARs – Fiduciaries. Are legally bound to do what is in the best interest of their clients…above all else.

RRs – Are responsible for making sure the products they sell to their clients are suitable.

Primary Responsibility/Function:

IARs – Primary responsibility is as an advisor to their clients

RRs – Sell securities and handle sales transactions for their clients

Compensation:

IARs – Generally charge a flat % fee for advice surrounding assets under management (AUM)

RRs – Tend to be commission based. They get paid commissions for products they sell.

Compliance and Regulations:

IARs – Are associated with Registered Investment Advisory (RIA) firms that are regulated by the SEC and/or state regulatory agencies.

RRs – Are regulated by FINRA (Financial Industry Regulatory Authority), along with the SEC and other state regulatory agencies.

Question #2: What is your particular expertise?

Not all financial professionals have niche markets….or only specific types of clients that they work with. But it’s important to know if they do. Understanding what kind of experience and typical clients the advisor has is important to understanding what to expect from them in regards to knowledge and experience that is relatable. Knowing what kind of team they have, and what kind of experience the team as a whole has is important. What do they specialize in? What resources do they have access to?

Here are some examples:

Tax efficiency with investments

Protection Planning – Estate planning collaboration

Small business owners

Multi-generational planning

Etc.

Question #3: What is your ongoing service model?

Taking the initial steps to get things organized and onboard with a financial advisor can be activity-filled and very important. But equally important is the clear communication about expectations for moving forward. Understanding what to expect between the advisor and client is critical to insuring that communication and expectations are being managed positively for the relationship, from both sides.

How often does the advisor reach out to clients?

Is there a team to support clients? Or just one individual?

What can be expected in regards to calls? Meetings? Paperwork? Statements?

What method of communication is used? Phone calls, meetings, email, video conferencing, etc.?

How accessible is the advisor if the client has a question?

These are just a few questions that might prove important to ask when interviewing financial professionals. There is no generic right or wrong answer. At the end of the day, it’s all about understanding what the relationship would be, the expectations for the relationship for both the client and the advisor, and communication. Being logical with interviewing an advisor is critical…look for proof and conviction between what they say they do vs. what they can prove they do.

Our financial well-being is critical for empowering our lives….we work hard for the life we want. And there are almost always some form of financial element to all we do. So please, don’t be afraid to ask the intrusive questions of the advisors you are considering working with. It could mean a great deal to how life gets funded….now and through all ages.

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
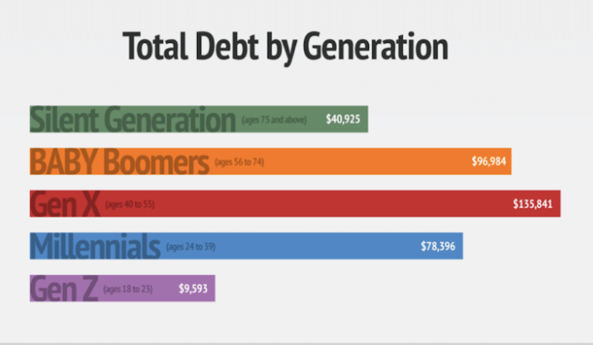
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


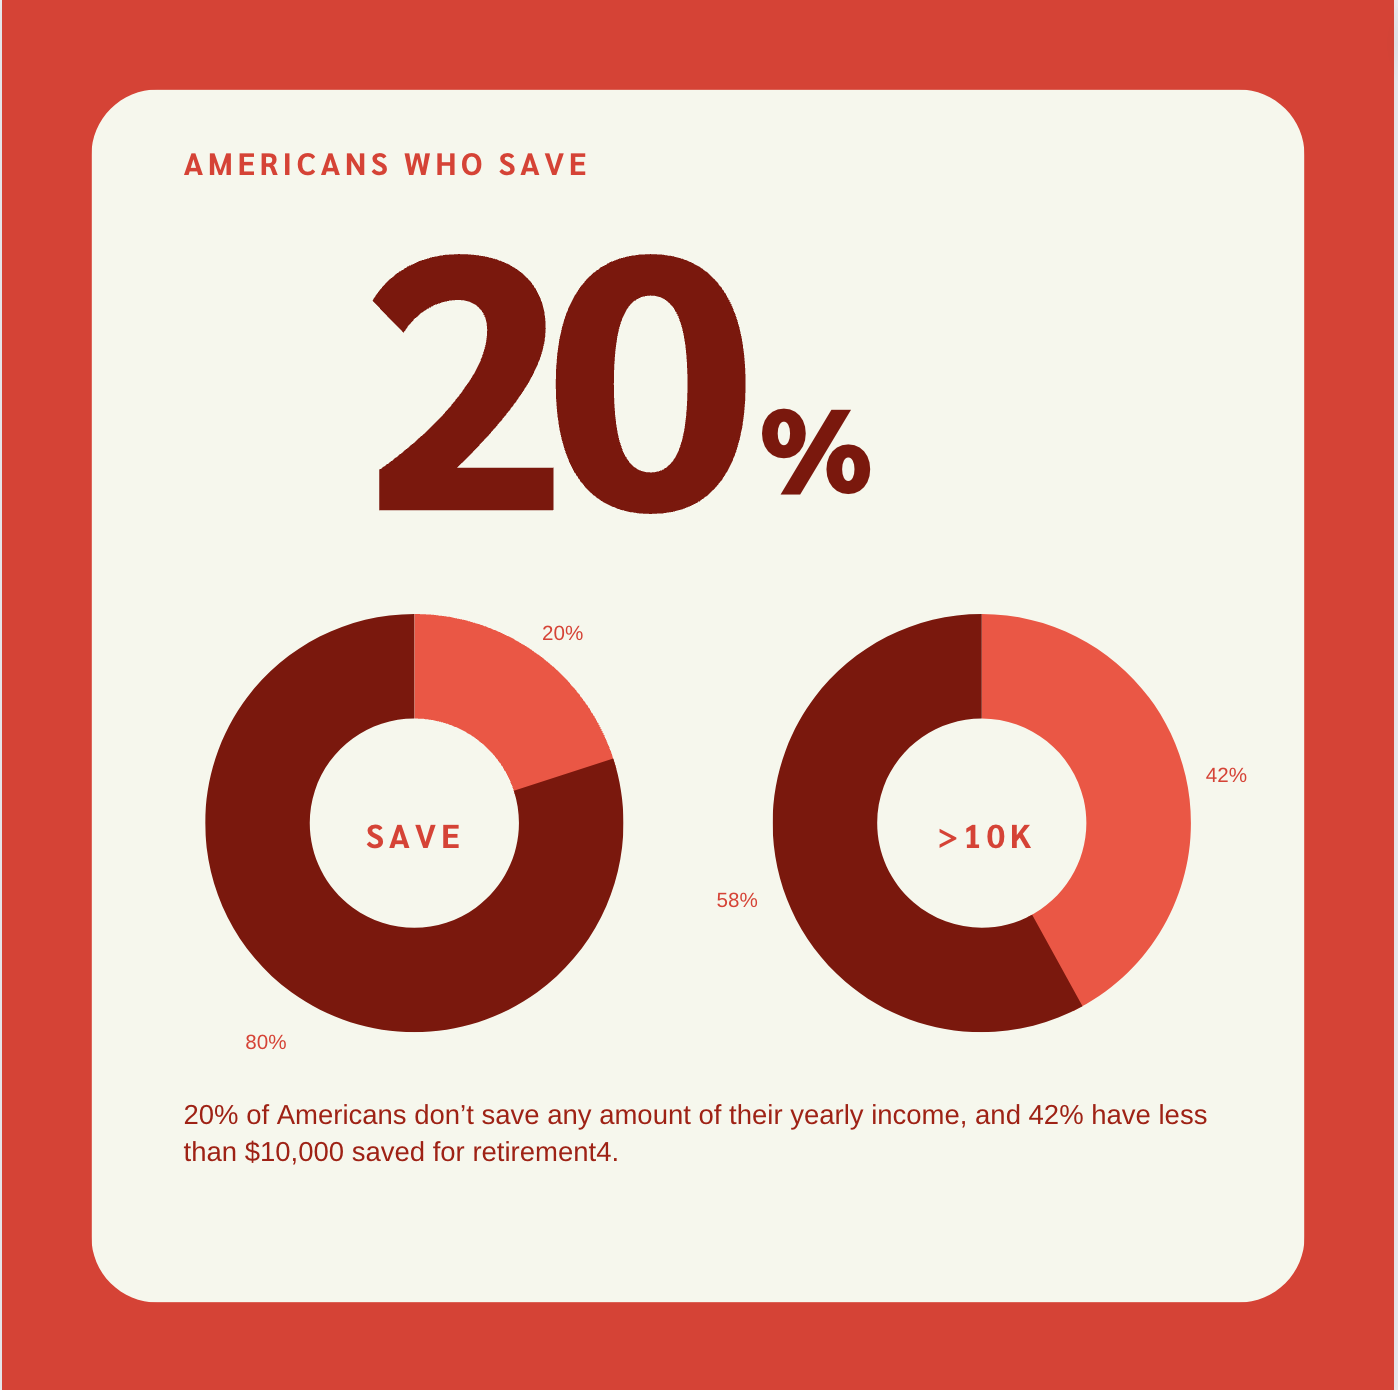
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


Get Started on Your Financial Life Plan Today