College – The Next Chapter: The Selection Process

By Trilogy Financial
May 31, 2019
Share on:

It’s graduation season, and there’s an excitement in the air about starting a new chapter. Mixed in with this excitement is an element of stress to make the right decisions: decisions on how things should be done, when they should be done and where they should be done. All these decisions are common, but they often distract from the purpose of what comes after high school.

We need to remember that higher education has a purpose. It’s more than an experience. The purpose of a college degree is employment. It is an investment, and as with any other investment, you should be calculating the return on that investment.  Spending $100,000 for a degree that secures a job with an annual salary of $40,000 is not the best rate of return.

There are plenty of creative ways to get a great college education without breaking the bank. Parents can start a 529 plan, the earlier the better, to help cover costs. Students can begin their higher education at a community college or secure college credit via Advance Placement (AP) exams. Additionally, students need to be sure that the field they are spending their time and energy on is going to reciprocate by providing solid career opportunities.

Making the wrong decision is not simply an unwise financial move. It can have lasting implications. Recent figures show that outstanding student loan debt has reached $1.5 trillion[i]. Our younger generation is not only struggling under this debt, they are also pushing off other personal and financial milestones, such as purchasing a house[ii], getting married or starting a family[iii]. These decisions can have long-lasting and far-reaching consequences.

Lastly, let’s not forget the countless parents who put their path to financial independence on hold to financially assist their struggling children. While wanting to financially help your loved ones is admirable, it helps no one to offer assistance at the expense of your own security. Just like when traveling by airplane, you need to put your own oxygen mask on and secure your safety first before aiding others. There are no scholarships for retirement, and you won’t have a financial safety net for the future if you don’t work towards creating it now.

College is truly an exciting time. Our young adults are learning who they are, where they want to go and how they intend to get there. At the same time, we cannot forget that college is a fleeting moment, one that is meant to arm the student with the tools needed to create a brighter and more successful future. Be sure to chat with your students to ensure that this experience does just that, rather than straddle these students with debt and stress.

[i] https://www.marketwatch.com/story/student-debt-just-hit-15-trillion-2018-05-08

[ii] https://www.businessinsider.com/student-debt-preventing-the-us-from-having-normal-housing-market-2019-5

[iii] https://www.bankrate.com/loans/student-loans/student-loans-survey-february-2019/

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Prior to investing in a 529 Plan investors should consider whether the investor's or designated beneficiary's home state offers any state tax or other state benefits such as financial aid, scholarship funds, and protection from creditors that are only available for investments in such state's qualified tuition program. Withdrawals used for qualified expenses are federally tax free. Tax treatment at the state level may vary. Please consult with your tax advisor before investing.

Disclaimer:

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Stock investing involves risk including loss of principal.

Bonds are subject to market and interest rate risk if sold prior to maturity. Bond values will decline as interest rates rise and bonds are subject to availability and change in price.

There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.

Investing in mutual funds involves risk, including possible loss of principal.

The principal value of a target fund is not guaranteed at any time, including at the target date. The target date is the approximate date when investors plan to start withdrawing their money.

No strategy assures success or protects against loss.
You may also like:

By
Jeff Motske, CFP®
May 22, 2018

“I have no interest in learning about finances. My [husband/wife] takes care of that.”

I have heard this statement from many clients throughout my career, and I understand the sentiment that prompts this response. Human nature has shown that when groups of people come together, they divvy up tasks to different individuals based on their strengths or roles in the group. You see this in many different groups, including families. My wife cooks dinner, and I’m great at taking out the garbage. With my siblings, I’m great at being the peacemaker while my sister knows how to shine a light on different perspectives. These established roles help our family units function smoothly and effectively…

Until one of the pieces of our unit is no longer around.

I’ve seen it far too many times. Clients come in distraught and overwhelmed because they’ve lost a loved one who typically acted as the family’s Chief Financial Officer. Sometimes they don’t know if there is a will or where legal documents are saved. Perhaps they are aware of a family safety deposit box, but they’re not sure where it is or how to access it. They aren’t sure about account balances or how to read statements. They may not even have access to critical accounts because the deceased was the one who knew the passwords. Now they are dealing with grief and heartbreak, compounded by confusion as to what the next steps are for maintaining their family’s financial solvency.

This is why I insist that both parties in a marriage are involved in financial planning meetings and decisions. I also recommend, especially for my senior clients, that other family members or loved ones are aware of the basics of their financial plans. It makes things so much simpler if all important documents, including a list of passwords, are stored together. If security is a concern, there are plenty of third party vendors that will virtually store that information for you. In most cases, though, a virtual safekeeper of your important information isn’t ideal. What is really needed is someone who will help guide your loved ones during that difficult time. That’s when a financial advisor can be an invaluable asset. I have had many Trilogy clients express how relieved they are to know that their financial advisor will be around to guide and assist the loved ones after he or she has passed. At Trilogy Financial, we don’t consider it a job. We consider it an honor and a calling.

There is a saying that it takes a village to raise a child. The truth is, it takes a village to care for anyone. Please make sure that your village is prepared and has the proper tools to take care of you. If you’re not sure where to begin, you may want to meet with a financial advisor. Our Trilogy Advisors are not only trained to assist your family on how to prepare for the future, but will also be there to provide support and service during a difficult and overwhelming time.

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


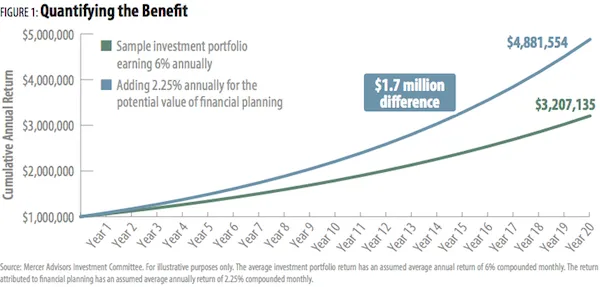
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


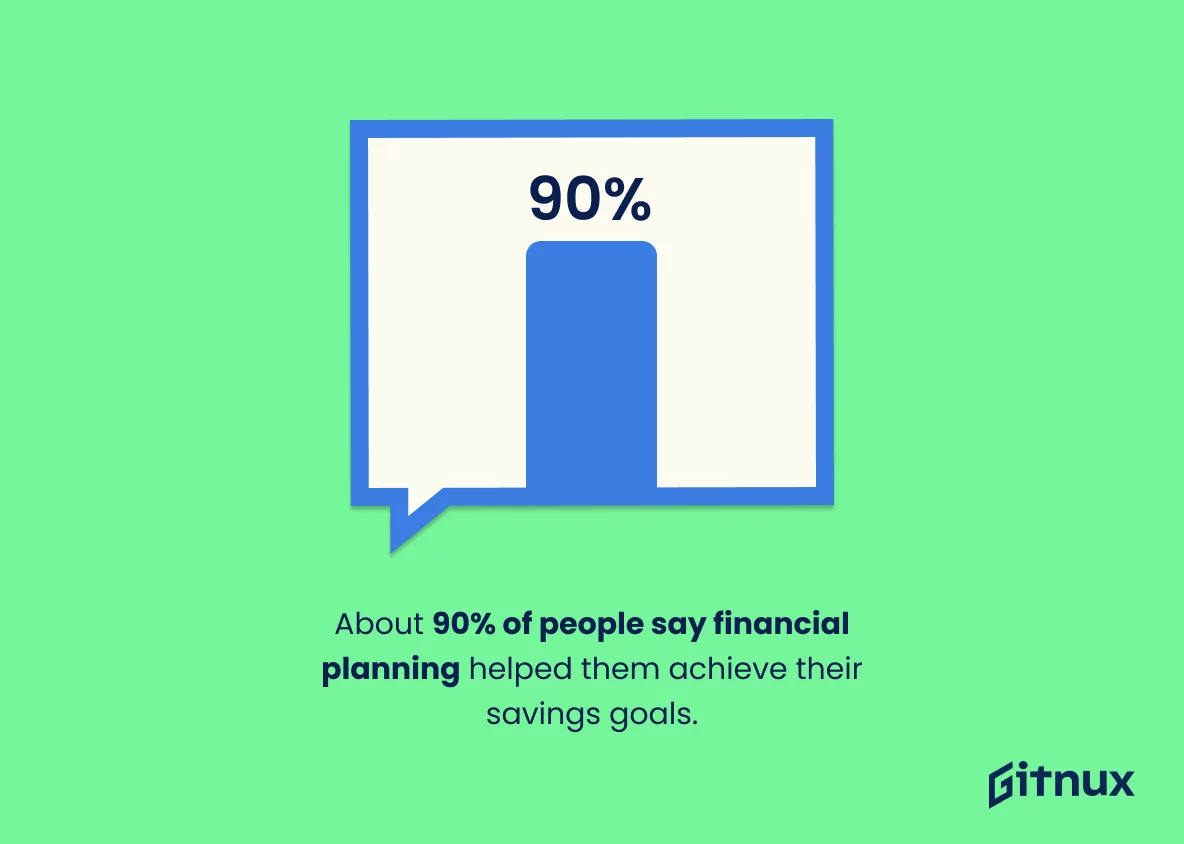
Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


Get Started on Your Financial Life Plan Today