Aren’t All Target Date Retirement Funds the Same? Spoiler Alert: No

By
March 21, 2018
Share on:

When it comes to choosing your 401(k) lineup, it’s easy to become overwhelmed by your options. It’s likely why more than 70% of 401(k) plans include at least one target-date fund. Also known as lifecycle or age-based funds, target date funds were created to simplify the investment choices for 401(k) plan contributors. Depending on your company’s 401(k) plan, they may be named something like Target Date Fund 2050, meaning you anticipate retiring around 2050. Target-date funds give employees the option of choosing one fund that diversifies their investments among stocks, bonds, and cash (the allocation) throughout their working life.

Considered a “set-it-and-forget-it” investment option, some investors choose target date funds as a default so they can avoid having to rebalance and update their portfolio allocations over time. The theory is that younger participants, having more years until retirement, can take higher risks in order to achieve higher expected returns. Since the funds focus on a selected time frame or target date (usually retirement), its asset allocation mix becomes more conservative as that date approaches. The percentage of stocks is reduced, and the percentage of bonds and cash is increased.

While target date funds may help encourage employees to participate in their company’s 401(k), there are a few misconceptions about how they work, and it’s important to understand these considerations before choosing your 401(k)’s investment lineup.

Target Date Funds Can Significantly Vary

Many investors get caught up in the year attached to a target date fund. If they change jobs and contribute to a different 401(k) plan, they may assume the target date fund is the same as their previous plan. Or, they believe that a 2050 target date fund is nearly identical to a 2055 target date fund.

However, target date funds with the same target date can significantly vary in their portfolio lineup. Fund families typically have their own unique approach with their target date funds, meaning a John Hancock target date fund likely won’t offer the same ratio of stocks and bonds as a Fidelity plan.

Take a look at this example from InvestorJunkie:

The percent of equities at age 65 significantly differs between target date families. When each of the target date funds has its own fee structure, mix of assets, and risk tolerance, it’s nearly impossible to measure performance between these funds.

Target date funds don’t just vary by their lineup. They can also have different fees.

As we can see in the chart above, the expense ratios considerably vary based on the target date and the target date family. Fidelity Freedom is more than 0.5% higher than Vanguard, which can take a toll on your portfolio when you’re investing for several decades.

Should I Invest in a Target Date Fund?

Like Though not a panacea, target date funds offer a reasonable alternative to the often confusing world of too many investment choices. Ultimately, there isn’t a single recommendation one can make for everyone. Each person has unique needs and circumstances, and they need to be taken into consideration when selecting their 401(k) lineup.

Before choosing a target date fund, there are a few factors to consider.

What do you want the fund to do for you?

Do you want a fund that is at its most conservative allocation when you retire or a fund that will take you through retirement? A target date fund’s allocation changes based on a set timeframe. If your fund is designed to help you get TO retirement, the amount invested in stocks will substantially decrease as you near your retirement date.

A fund that’s designed to get you THROUGH retirement changes allocations based on your life expectancy. These funds will have a greater amount in stocks at retirement than the to funds and thus be higher risk. Knowing which type of fund you own is critical to your ability to assessing its riskiness, along with its long-term expected returns if you are able to stay the course with it through troubled times.

What are the funds’ target allocations?

Whether it’s a to or a through plan, what are its target allocations? How are decisions about allocation made and do those choices complement your needs?

What's your risk tolerance?

Target-date funds can be more aggressive or more conservative than expected. During the 2008 financial crisis, many investors with 2010 target-date funds suffered severe losses because they didn’t realize their portfolio was invested in more stocks than they thought. Would you have stayed invested if the fund had struggled in 2008? If not, perhaps you should look at a more conservative option.

What are the fees?

Target-date funds can often cost more than other funds because they’re known for their long horizons, and their fees will vary by target date family and target date. If you are more cost conscious, you may prefer to invest in index funds.

Choosing Your 401(K) Lineup.

When there are a plethora of investment options from which to choose, take the time to understand what you want from them and find a fund that meets your needs. If you would like to discuss target date funds or other 401(k) options. I encourage you to reach out to me. Call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com.

The target date is the approximate date when investors plan to start withdrawing their money.

The principal value of a target fund is not guaranteed at any time, including at the target date.

No strategy assures success or protects against loss
You may also like:

By
Keegan Tanghe, AIF®
November 7, 2017

Don’t we all just love the holidays? Having a nice, large Thanksgiving meal with close family and friends? Unwrapping presents during Christmas or Hanukkah, seeing the big smiles on the young kids and grandkids as they rip open that favorite toy they begged for? It may be pure bliss during the months of November and December, but come January and February, when those credit card statements come in, the stress starts to set in.

According to the article here,   the average person takes more than five months to pay off that holiday debt. Many more carry that into the next holiday season, hence carrying it indefinitely and having it snowball out of control. Many people just make the minimum payment on credit cards throughout the year, and then when the holidays come about, go crazy with buying up everything, their balance goes up, and so does that minimum payment, which they soon cannot afford to pay. Defaults on credit cards and people trying to do balance transfers or debt consolidation soon become the norm and the house of cards (literally) soon falls.

44% of people surveyed stated that they were stressed out because of that extra holiday debt. Among all age groups, Millennials were most likely to go into debt around the holidays. People ages 24-35 were most likely to say they went into debt this holiday season with a rate of 14.3%. With the exception of 45-54-year-olds, the likelihood of going into debt decreased with age. Seniors were least likely to say they went into debt, with a rate of 7.6%.

So how can we mitigate or eliminate this holiday debt altogether?

Start a holiday-saving account: Set aside a holiday or Christmas budget at the beginning of each year! The problem that many people run into is that they do not set a holiday season budget and just spend, spend, spend. We have many clients who save anywhere from $50-200/month starting in January, so that they have their full budget come the 4th quarter. Or, if you are out shopping throughout the year and see a great sale on something that a family member or close friend would like, feel free to buy it, to pace yourself. If it’s within the budget, you should be ok.

Change your tax withholdings: It’s also a proven fact that many people over-pay their taxes throughout the year, over-withholding on their paychecks. The average person pays their amount of taxes by the spring or summertime, and the rest of the year is just spent paying more to Uncle Sam, lining his pockets. We have had many clients who come through our office in the 3rd or 4th quarter, and after we look at their tax returns for the previous year, as long as everything is a constant, we ascertain that they have already paid all of their taxes for the year. They can then increase their withholdings on their paycheck, thus bringing in more income monthly, to allow them to pay for the holiday’s cash. Solution: no post-holiday blues. Then, come January, we would review the client’s situation again, many times working alongside their CPA, to help them get to more of a point of breaking even or getting just a small tax refund back at tax time. This would allow them to better plan out their budget for the year.

Can you change your schedule: Other things to consider to have a credit card-free holiday is to work overtime, if your job allows it, or if you get a bonus throughout the year, to set that aside for the holiday season. But don’t count on it, as you can’t always rely on bonuses, commissions, or pay raises to occur when you want them to.

If you are a people-person and don’t mind strangers in your car, consider driving for Lyft or Uber. I believe they offer tiered bonuses if you complete a certain amount of rides during your first 30 days of working and always have promotions going on. That’s an instant quick bonus for one or two months of work. Many retailers, as well as Amazon, hire hundreds or thousands of seasonal part-timers, to help with the holiday rush. Maybe you can even use that employee discount at that retail store you’d be working at to get a good deal on some presents. UPS and FedEx also hire extra drivers and warehouse employees to sort through all of those packages that are being delivered the last two months of the year.

Conclusion: Get creative and don’t get complacent. You can do this!

Action items:

Understand where your money actually went.

There are many great apps out there which can track your spending throughout the year, and help you stay up on things, so things don’t spiral out of control

Set a realistic budget of what you will spend on family, friends, co-workers, and even clients, if it merits it in your situation, so you don’t break the bank

Work with a trusted financial advisor/coach that can hold you accountable on your spending, so you can keep pace to reach your financial goals

Good luck and let us know your progress!  Enjoy the holidays and create some lifetime memories!

[1] http://www.magnifymoney.com/blog/featured/americans-holiday-debt-added-1003-average-year/

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


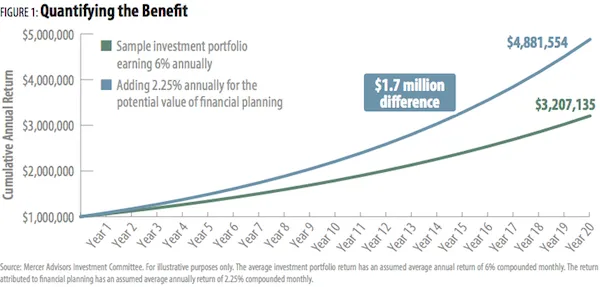
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


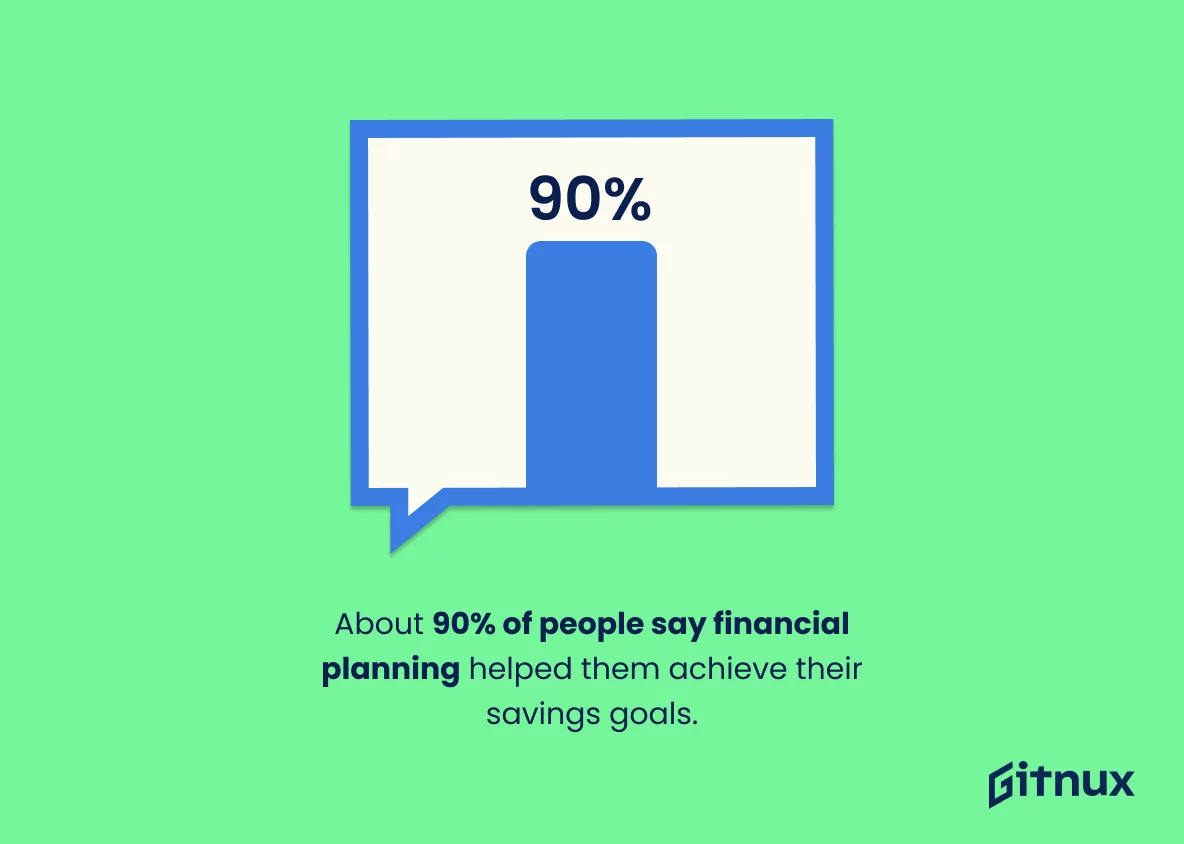
Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


Get Started on Your Financial Life Plan Today