Advanced Care Planning

By
August 26, 2018
Share on:

There is one area of planning that gets glossed over, even by the many responsible people: long-term care planning. For so many, it is difficult to plan for something that seems so far removed from their current existence. Many also assume that their current health insurance or Medicare will cover most expenses associated with long-term care. Unfortunately, these mistakes leave them ill-prepared for the expensive reality.

As the US government estimates 70% of individuals who are currently 65 “will require some form of long-term care”.1 Therefore, this is more of an eventuality for most folks than it is a possibility. When an individual’s health starts to decline, hopefully, multiple levels have been put into place. Not only should you be concerned with who will care for you physically, you must all consider who will care for your finances.

Physical Care –The costs for long-term care can be surprising for many, with the average 65-year-old paying approximately $138,000 over his/her lifetime.2 As mentioned earlier, Medicare or private health insurance rarely covers all types and expenses of long-term care. Medicaid assistance varies by state and requires that an individual “must spend down his or her assets and meet other criteria.”3 Additionally, It is important to talk with your loved ones about long-term care options, not only about what one can afford but equally as important, what one prefers.

Ultimately, many end up paying for long-term care from their own finances – 50% according to the Bipartisan Policy Center report.4 To protect your finances and the finances of your loved ones, it is vital to prepare for these possible scenarios. There are many long-term care insurance policies that can provide you the assistance your particular situation needs. The premiums for these policies are much more affordable the younger you are. While some of these policies can get a bit confusing, a financial planner can easily go over these policies and help you determine which one would be best for your particular situation.

Financial Care – The key to financially protecting a client in declining physical or mental health lies in teamwork. The team, which consists of their financial team members (financial planner, tax professional or estate planning attorney), delegates and medical professionals. While we all continue to focus on our own particular role and duties, maintaining a professional relationship does give us the opportunity to share any concerning or unusual behavior concerning our client, as well as execute things quickly and as close to the client’s wishes as possible. Equally important is a Durable Power of Attorney (DPA), which legally allows an individual to designate someone to make financial and medical decisions on their behalf should they become mentally incapable to do so. Having these safeguards in place can save on time and hassle should health matters deteriorate and allow your delegate to focus on more pressing issues.

When so many of us pride our independence and self-reliance, declining health issues can be downright scary. I understand this well as I do my best to set my clients up for financial independence, so they can create the life they want to live. When circumstances step in and disrupt your life, it’s vital to know that you have people to rely on and safeguards to protect you.

1. https://www.usatoday.com/story/money/personalfinance/retirement/2017/11/17/retirement-planning-should-include-long-term-care-costs/866344001/

2. https://www.usatoday.com/story/money/personalfinance/retirement/2017/11/17/retirement-planning-should-include-long-term-care-costs/866344001/

3. https://www.consumerreports.org/elder-care/elder-care-and-assisted-living-who-will-care-for-you/
4. https://www.usatoday.com/story/money/personalfinance/retirement/2017/11/17/retirement-planning-should-include-long-term-care-costs/866344001/

You may also like:

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
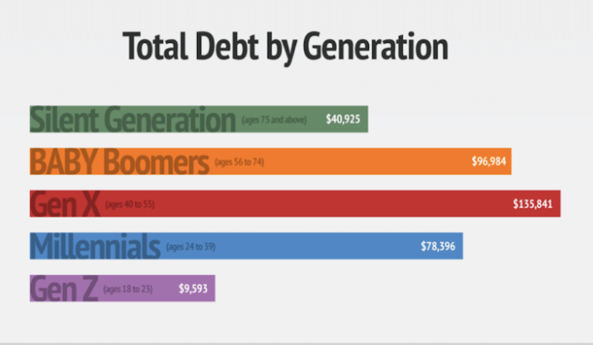
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


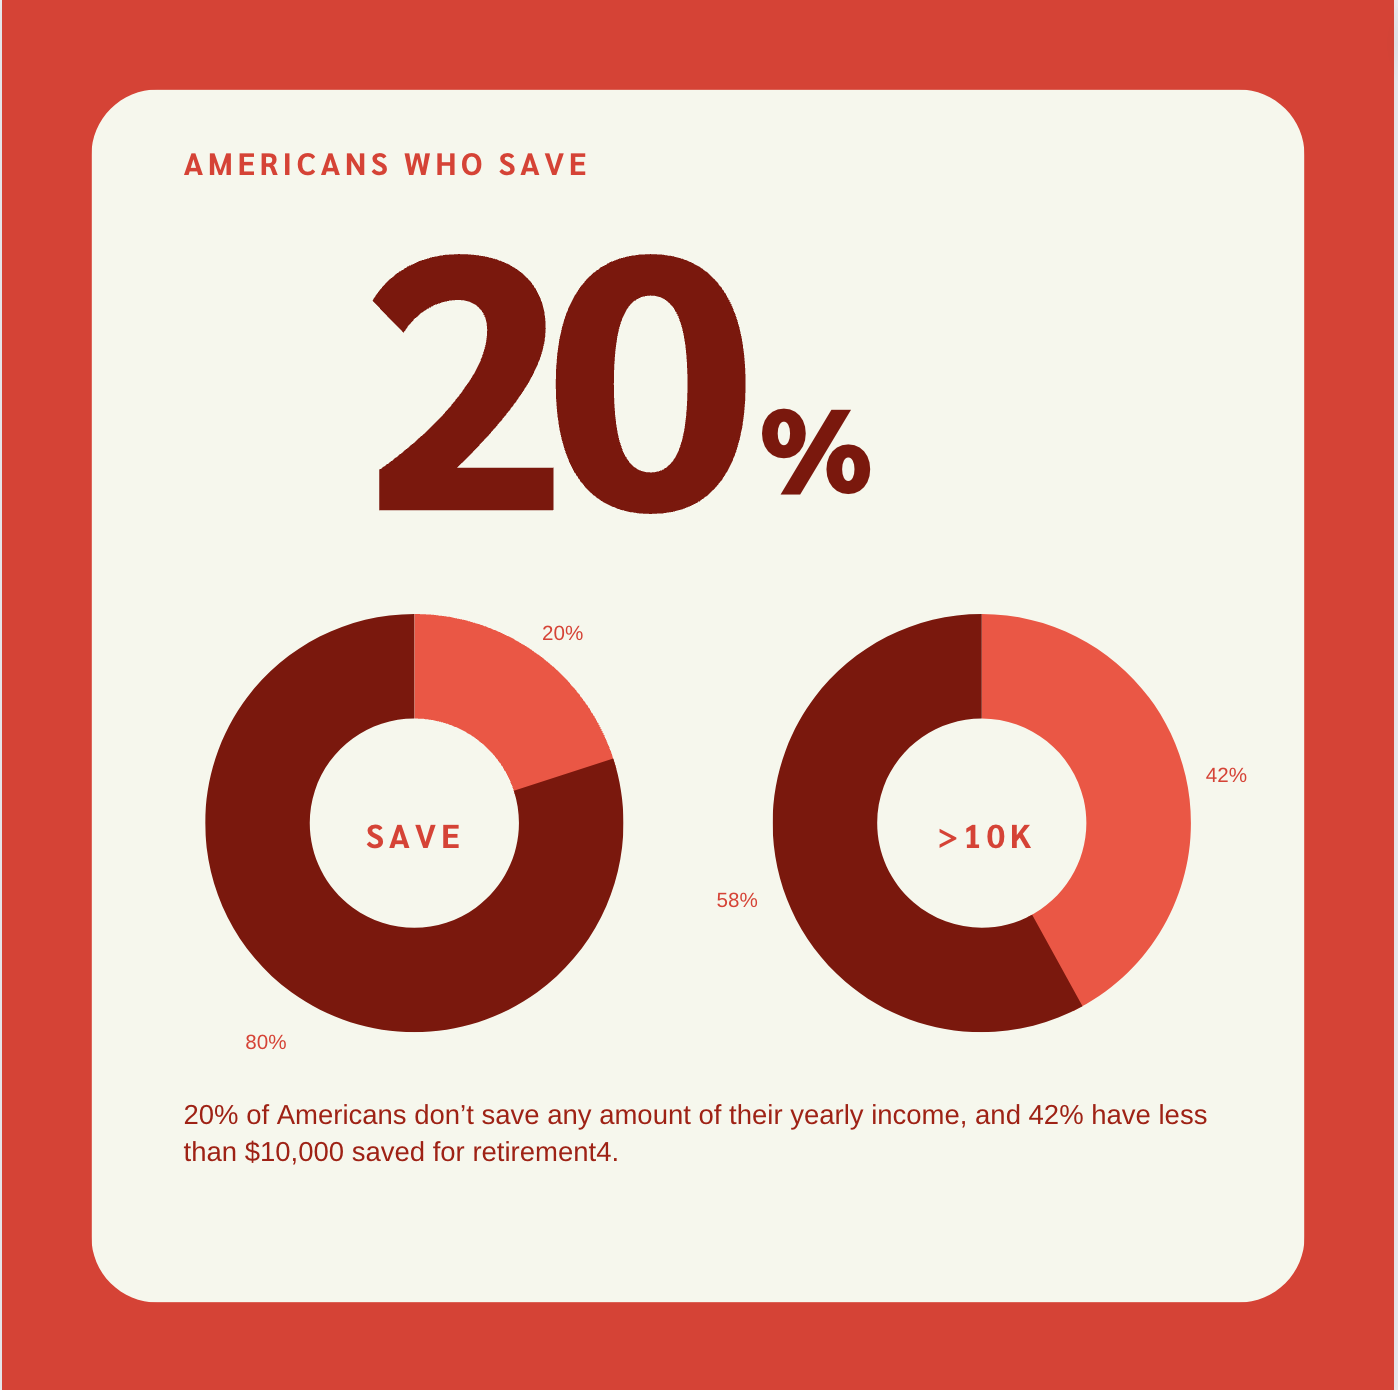
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


By
David McDonough
July 2, 2019

Words are power, and each word has its own weight and energy. Words have inspired people to stand up for what they believe in or hang their head down in defeat. Therefore, choosing the right words to describe that which you want to manifest is very important.

For example, when speaking of aspirations for the future, there are those who use the words dreams and goals interchangeably. However, they ae distinctively different in definition and performance. A dream is boundless, fueled by your passion and imagination. However, it is akin to fantasy, with no immediate call to bring it to life. When someone tells me they dream of owning a sports car or starting their own business, I know most of the work to make that dream a reality hasn’t taken place and probably won’t for the foreseeable future.

A goal, on the other hand, is the mapwork to that dream, concrete and behavior-driven. When you have a goal, you have markers, measurements and steps to get to the destination. Setting the right goals, especially when it pertains to financial goals, can have a significant effect on how and when you achieve them. In fact, a guide to good goal-setting has long been to make it S.M.A.R.T.1:

Specific: if we are truly making a map towards our goals, telling ourselves to go in a general direction or for an undefined distance is most likely only going to get us lost. Steps towards our dreams have to be detailed and specific.

Measurable: When a goal is measurable, there is a way to track your progress to stay motivated or identify issues that may need problem-solving.

Attainable: It is admirable to be striving for something grand and lofty. However, it’s imperative that we have feasible goals that we can accomplish to keep us motivated and actually accomplish said goal.

Relevant: Having impressive goals are fine and dandy, but if they don’t move you closer to your overall goals or work against other goals you may have, it may be time to rethink them.

Time Bound: Once something has been stated as a goal, the stop watch has started. There is an expectation of completion, which is necessary to keep us moving forward towards that goal. It may not get completed in the expected timeframe, but just by having a deadline, we can stay accountable.

Based on this description of a S.M.A.R.T., you can see that there is a difference between, “I’m going to start saving money for a house,” and “I’m going to put 15% of my paycheck into a savings account specifically designated for my eventual down payment, and I should have enough saved after 3 years.” One expresses a desire while the other one lays out a concrete plan to achieve the goal.

If one seems to be fueling the other, how can a dream inhibit a goal? Well, one way is when your lifestyle fits with your dream rather than your goals. To achieve many financial goals like saving for retirement or buying a home, one needs to save and stick to a budget. However, if you fail to save and incrementally work towards the goals, it will take longer and longer to see results. Worse is if you choose to skip the incremental steps and live your dreamer’s lifestyle by using credit cards. The debt you accumulate will take you farther and farther from your goals and possible put you in an unfortunate and stressful predicament.

Sometimes when we haven’t developed a goal for a dream, it’s vagueness can work against an already established goal. Perhaps a good friend asks you to go into business with them. If you choose to pour funds into this new endeavor without any parameters, you may find yourself taking funds away from saving for retirement or depleting savings you already had. Of course, if you had outlined your goal on how to contribute to your friend’s business, with specific and timely parameters, the situation could be completely different.

Please understand that I’m not asking you to stop dreaming. In fact, quite the opposite. I happen wake up every day saying, “Dream Big! Work Hard! Laugh often!” I sign letters and thank you notes and end employee meetings with those very words. Dreaming is important.

So please know I want you to dream big and bold. At the same time, I want you to buckle down and create some S.M.A.R.T. goals to propel you closer to your dreams.

https://www.mindtools.com/pages/article/smart-goals.htm

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

Get Started on Your Financial Life Plan Today