3 Lies We Believe When It Comes To Financial Planning

By
July 12, 2018
Share on:

There may be plenty of factors outside of your control that impact your financial situation, such as the markets, the economy as a whole, or an unexpected illness. But those circumstances may not play as critical of a role in your financial life as you might think. The real dangers to your financial future are the lies you tell yourself when it comes to financial planning. Here are some ways you could be undermining your financial success and some ideas on how to change course.

Lie #1: I Don't Need Help. I Know What I'm Doing

Let’s say you read a plethora of financial planning books, stay up-to-date on the markets, and know all about budgeting software. That may put you ahead of a lot of other people, but there are certain aspects of financial planning that often go ignored even by the most knowledgeable people. Let’s look at a couple of hypothetical examples.

How Often Do You Review?

How often do you refresh your goals, adjust your plan, and determine how and when to make changes? A financial planner does more than just monitor your portfolio. They act as your coach, motivating and guiding you when things get tough. They bring an objective perspective to the table and develop a customized strategy based on your financial priorities. The end result is increased confidence in your financial strategies and decision-making. You don’t want to suffer a financial setback just because you were too busy or too forgetful to keep up with your financial plan.

In Case of Emergency

What if the unthinkable were to happen and you couldn’t make financial decisions? Will your family be able to handle the details and figure out your financial plan? An advisor can offer a holistic overview of your net worth and determine what elements need to be in place to protect your family and your wealth. These are often things you may not be aware of, such as life insurance or a living trust.

Market Research

Investing is tricky business on a good day. Can you manage the emotions, anxiety, and possible second-guessing of your investment choices if you were living on a fixed income and the market were to face a correction? An advisor has tools to evaluate cash flow to help you determine the probability of your money lasting through your retirement years. They can also keep you accountable and committed to your long-term strategy in the midst of market ups and downs.

Lie #2: I Can Always Get Help When I Need It

If you were going on vacation, would you rather have everything packed ahead of time and enjoy your restful break? Or would you prefer to be disorganized and arrive without essential items, forced to then spend your time off running around shopping for things you forgot? When it comes to money, it’s the same idea. When you really need the help, you may have lost your most valuable resource – time. Instead of thoughtfully researching your options and making decisions with a clear head, waiting until you need help will result in a frantic scramble to just get things done.

Whatever it is you experience in life, having a financial planner on your team will help you stay on top of your money and prepare in advance for future milestones and events.

Lie #3: I Don't Need An Advisor, I Have Financial Technology

Financial planning has evolved. Years ago, it was about who had the most up to date information on a company to buy a stock, and the planning industry was mostly concerned with buying and selling stocks and bonds rather than portfolio management. Today, financial planning is more about what’s missing in your overall strategy, what have you not thought of, and what could you be doing that you’re not. On top of that, the financial planning process helps you emotionally connect with your goals so you can get on the right track. Technology, at the present time, can’t do that.

Technology has many good points, but several drawbacks as well. For example, you can find more information than you’ll ever need, but you’ll also come across plenty of misinformation which could lead you astray. It’s not uncommon for someone to research something on the Internet and find just as many pros as there are cons. If you want to save for your child’s college education, you’ll find articles touting the value of using a 529, a Roth IRA, or a Roth 401(k). How do you figure out which one is truly right for you? The abundance of information has created so much noise that in many cases, people don’t do anything at all.

While technology should be used in financial planning, it should not replace the role of an advisor. The importance of what advisors do from a human aspect is help clients sift through the noise and misinformation and encourage them to move forward in taking action.

A Change In Perspective?

Have you ever believed one of these lies? It’s easy to do, but the consequences are real. Don’t take a gamble with your money. Join forces with a financial advisor who can help you make the most of what you have, where you are, and get you positioned for a bright financial future. Call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com for a no-strings-attached meeting to discuss your situation.
You may also like:

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
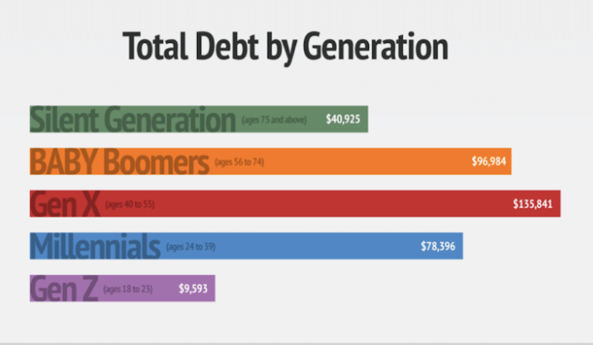
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


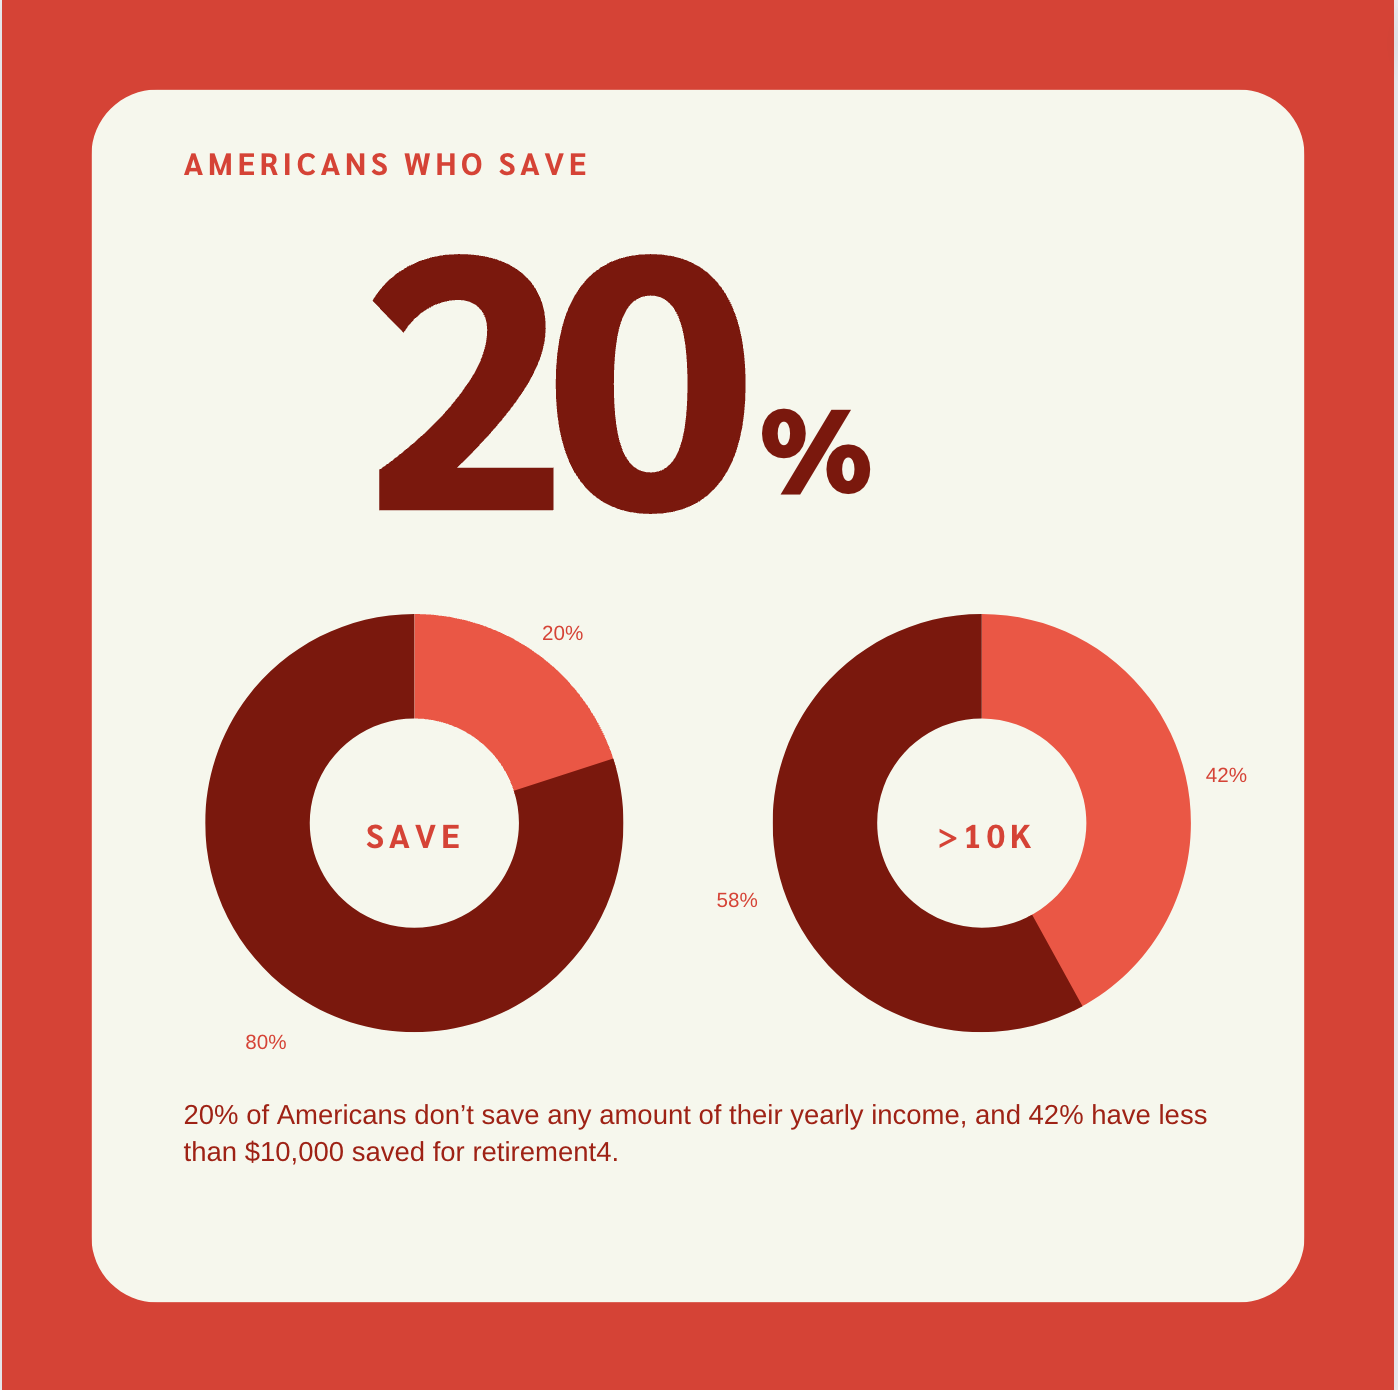
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


By
Mike Loo, MBA
June 21, 2018

Regardless of where it comes from, getting an unexpected chunk of change usually makes for a pretty good day, week, or even year. But if you aren’t intentional about what you do with your extra cash, you could follow in the footsteps of many lottery winners who squander their winnings and end up unhappy and broke.1  Even if the gift you receive isn’t a significant amount, you’d be amazed at how some smart planning can make a big difference down the road. Let’s look at some ways you can you use your raise, refund, or windfall to get ahead financially.

  1. Pay Off Debt

Big debt, small debt, it doesn’t matter. Debt is debt. Start with high-interest debt and work your way down. Did you know that the average American household carries over $16,000 in credit card debt and pays an average of $1,292 in interest annually?2  Sure, using your extra influx of money to reduce debt isn’t as fun as going on a trip, but think of the satisfaction you’ll feel when you see your balance decrease, knowing that you are saving yourself thousands of dollars in interest in the long run.

  1. Beefing Up Your Retirement Savings

Even if you diligently contribute to a 401(k) or IRA, chances are you aren’t maxing out those accounts. Let’s say you receive a $3,120 tax refund, the average amount according to the IRS.3  You then deposit that $3,120 in an IRA and see a 7% rate of return annually. In 20 years, you will have earned approximately $8,000 on that investment due to compound interest. Let’s go a bit further. If you invest your tax refund every year for 20 years, your retirement savings could see a boost of almost $150,000! If you’ve received a raise, use some of it to increase your contribution percentage right away. That way, you won’t get used to living with that extra money and it puts you ahead for the future.

  1. Invest In Education

Most of us dream of our kids going to a great school and getting a solid foundation for their future career, but have you considered how much of an investment it will take to get them to that point? The numbers can be daunting. These days, a high school graduate can expect to pay upwards of $200,000 for an undergraduate degree at a top school4 and over $10,000 each year for in-state tuition alone at a public institution.5  The costs will vary depending on room and board and other educational costs, but either way, it’s a lot of money.

One option is to open a 529 account with your tax refund and, once again, let compound interest help you get ahead. Not only will your investment pave the way for your child’s future, but it could also give you a tax break.

  1. Build Your Emergency Fund

An emergency fund provides you with a cushion for those times when life gives you lemons. If you don’t have readily available savings, something as simple as an unexpected car repair or medical bill could derail your finances. Or, if you know you have a large purchase or a life milestone approaching, such as welcoming a baby into your family, having an emergency fund will help you avoid digging into long-term savings or going into debt to cover costs. You can’t put a price on the peace of mind that an emergency fund will give you, so think about investing some of your tax refund to boost your short-term savings.

  1. Be Generous

Giving your tax refund away may not help you get ahead, but it could make a lasting impact on someone else’s life. Find a charity or cause that is close to your heart and pay it forward. Your gift could also help you when the next tax season rolls around. Just make sure to get a receipt for your contribution and itemize your deductions.

Have You Received Some Extra Cash?

It’s okay to treat yourself when you find yourself with excess income, but don’t splurge just because the money is there. Make a list of your financial priorities and then map out how your additional money could give your financial future a boost. If you would like guidance on how to use your raise, refund, or windfall, call my office at (949) 221-8105 x 2128 or email me at michael.loo@lpl.com.

Get Started on Your Financial Life Plan Today