Avoid These Common Mistakes When Choosing a Financial Planner

By Trilogy Financial
February 20, 2024
Share on:

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications
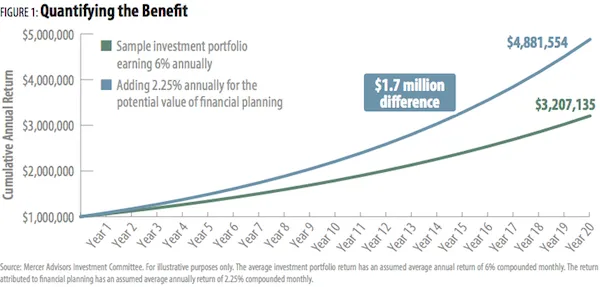


Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering
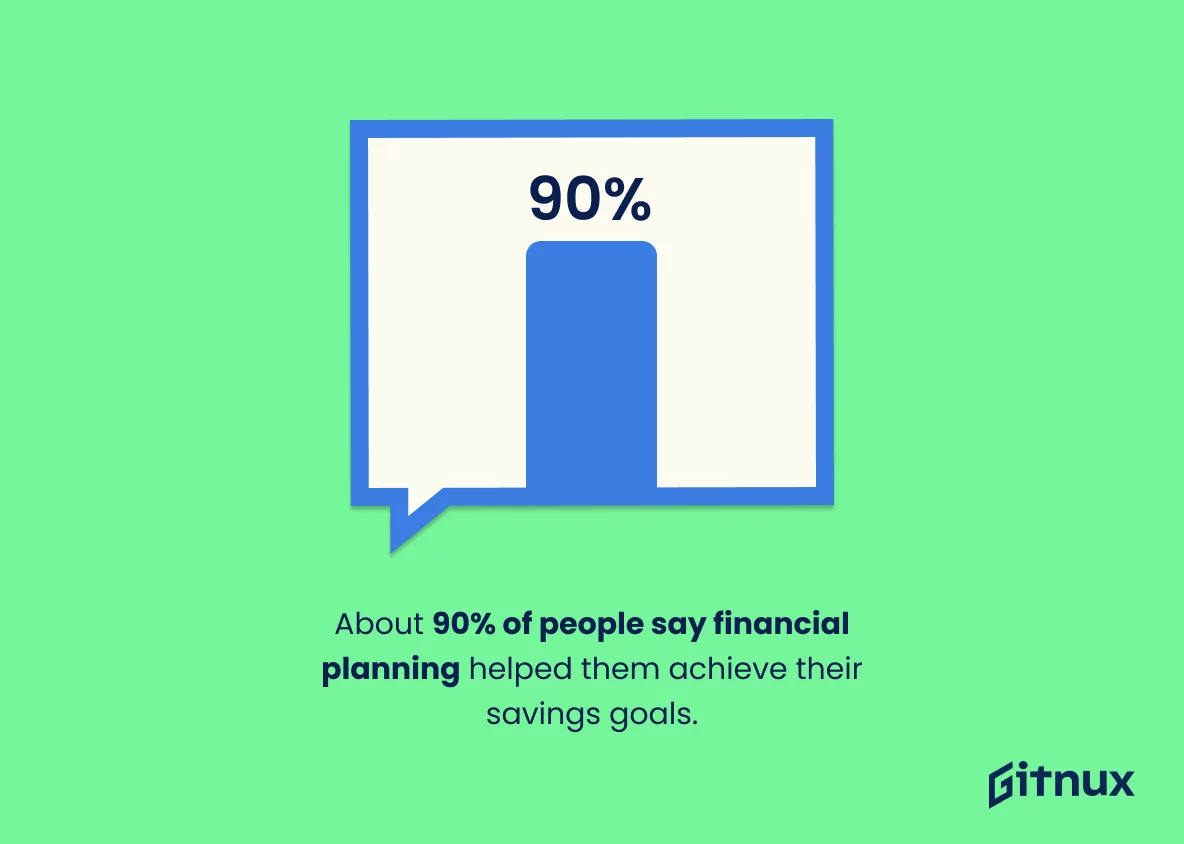


Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


You may also like:

By
Jeff Motske, CFP®
May 29, 2018

We live in a dynamic and inspiring time. Advancements in healthcare are doing wonders for retirees. Many are living longer, in greater physical health, maintaining their mobility and independence. However, there has also been a growing impediment to that independence – dementia. This syndrome that characterizes the decline of cognitive functions and encompasses degenerative diseases like Alzheimer’s, Parkinson’s and Huntington’s is impacting more and more every year. While it can be very uncomfortable to consider yourself or a loved one suffering from such an illness, living in this age of dementia makes planning for its onset a necessary endeavor.

The statistics are sobering. Those who are diagnosed with Alzheimer’s disease can typically live four to eight years after the initial diagnosis. However, there are also those who can live up to twenty years after their first diagnosis. As this is a disease that wrecks the mind, not the body, some can live up to 5 years in long-term care, rather than the typical two years of other illnesses. Needless to say, the costs of care can be staggering. With expenses ranging from various prescriptions, personal care supplies, limited or long-term care services, there is clearly a lot to plan for. Many rely on Medicare to cover the expenses. Yet, Medicare does not cover everything, oftentimes paying up to 80% of costs, only covering fees that are considered “medically necessary” and taking time to determine what falls under that qualification.1 When you or your loved one is struggling daily with the complications of dementia, hope can seem far off or entirely out of reach.

Due to the subtle ways symptoms can first appear, many can go years without a diagnosis. Unfortunately, that does not mean that the illness is not affecting their lives. While there are specific stages of decline with various forms of dementia, financial matters are generally impacted immediately. Memory suffers, with individuals forgetting to stay current with their bills or having issues understanding their bank and account statements. With subsequent stages, financial skills, along with others, decline further. It can be a rapid and steep decline. An individual’s independence, financial and otherwise, can be compromised very quickly.

This is why it is very important to discuss financial and legal matters once a loved one has been diagnosed, regardless of whether it may feel awkward or uncomfortable. The sooner these conversations take place, the better. There is a lot of information to cover and a lot of decisions on the possible future to make. Most importantly, the earlier the conversations are started, the more of a role the diagnosed person will have. At the end of the day, that is what we all want, for our loved one's wishes and desires to be upheld, even when they may no longer be able to vocalize them.

In addition to helping our loved ones afflicted with these diseases, we cannot forget the loved ones providing the assistance. The strain that can get placed on a familial caregiver can often get overlooked. If not adequately planned for, some will dip into their savings and sell their investments to cover the mounting costs to care for their loved ones. Additionally, the stress of the situation can detrimentally impact the physical and emotional health of the caregiver, which can put both individuals at risk.

Clearly, there is a lot to consider, and for many, it is easy to get overwhelmed, flounder in all the unfamiliar information and overlook that which we are not well-versed on. This is where your financial professional can assist you, both in the midst of this difficult time and also well before the actual diagnosis. They can help you make decisions and preparations, as well as educate you on the myriad of things you may not be aware of but need to know. Additionally, Trilogy Financial advisors are trained to not only identify when clients may be exhibiting symptoms of dementia but to continually monitor these behaviors as well. We truly do take our clients’ well-being seriously. Many individuals I have encountered have two distinct fears about growing older. The first is running out of money. The second is becoming a burden to their family. With dementia, those two fears can become a reality. However, with the proper preparation and planning, they don’t have to be.

Sources: 1. https://www.medicareresources.org/faqs/what-benefits-does-medicare-provide-for-alzheimers-patients/

By Trilogy Financial
February 26, 2024

In the era of self-directed retirement planning, the need for individualized strategies and informed decisions has never been more pronounced. As you tread into the realm of retirement, engaging with experienced retirement planners becomes crucial to ensure a secure and joyful post-career life. However, the realm of investing can be complex, and making informed decisions is vital for financial success.

If you are looking to make well-informed investment decisions, consider speaking with a financial advisor at Trilogy Financial Services. With the help of qualified professionals, you can navigate the financial complexities that may be hindering your wealth amplifying journey.

Through this expedition, we recommend reaching out to the Financial Planners at Trilogy Financial Services to help guide you through the fog of financial decision. They can help you navigate resources such as the “dont worry retire happy pdf” documents or the more simplified “Retirement for Dummies” documents you might find on the internet when looking for solutions.


Understanding Taxes and Retirement

Let's take a moment to talk about retirement.. It's not merely a phase of life; it's a significant transition that requires meticulous planning and foresight. One of the critical aspects to consider is how might taxes have an impact on your financial plan. A comprehensive understanding of tax implications is essential for effective wealth management, especially when it comes to safeguarding your nest egg from potential tax liabilities.


Wealth Management Strategies

Engaging in astute tax and wealth management strategies is paramount in preserving and growing your retirement corpus. By exploring various tax-advantaged retirement accounts and consulting with professional tax advisors, you can better prepare for the tax implications that come with retirement. This proactive approach not only keeps your financial plan on track but also paves the way for a more secure retirement.


Smart Retirement Options

As you delve deeper into the retirement planning process, exploring smart retirement options becomes a priority. These options could range from choosing the right retirement accounts, investing in tax-efficient funds, to exploring annuity products that provide a steady income stream. The aim is to build a robust financial portfolio that aligns with your retirement goals while minimizing tax liabilities, thereby ensuring your savings not only last but grow throughout your retirement.


Real-world Case Studies

  • Transitioning into Retirement: Curt from De Pere, WI, started strategizing for his retirement alongside his wife after lengthy careers in public service, with the assistance of a Financial Planner.
  • Early Retirement Evaluation: Stephen and Nicole evaluated an early retirement package to manage taxes efficiently during their transition into retirement.
  • Career Change and Retirement Planning: Susan and Chris transitioned from high-profile music industry jobs to retirement, achieving their goals with the aid of First Wealth.
  • Long-term Savings Strategy: Jim and Cathy’s story illustrates the importance of long-term savings and debt management, having saved $750,000 in a 401(k) and $300,000 in savings over their working years.


The Bright Side of Retirement

Planning for retirement isn't solely about numbers and finances; it's also about envisioning a happy, fulfilling life post-retirement. Infusing humor and a positive outlook towards this life-altering phase can make the journey enjoyable. A funny, happy retirement is indeed a product of sound financial planning paired with an optimistic outlook.


Key Retirement Statistics

  • Gender Disparity: Only 17% of women feel on track to meet their financial goals compared to 26% of men.
  • Retirement Account Investments: Americans had invested $6.8 trillion in 401(k)s and $12.5 trillion in IRAs as of the first quarter of 2023.


Professional Insights

Professional insights add another layer of credibility to the smart retirement planning narrative. Jim Barnash, a Certified Financial Planner with over four decades of experience, emphasizes the importance of meticulous retirement planning. Understanding complex financial concepts such as the ‘Sequence of Returns Risk' is also crucial as per experts' advice. Moreover, strategic moves endorsed by financial experts can significantly enhance the possibility of retiring as a millionaire, as discussed in a recent piece on Nasdaq.


Planning for the Unexpected

To further aid in your retirement planning, establishing an emergency fund is advisable. An emergency fund serves as a financial buffer, ensuring you have the resources to cover unexpected costs. Having three to six months' worth of living expenses in your emergency fund, which can be adjusted based on your unique financial situation and risk tolerance, is a common goal provided by financial planners.


Leveraging Modern Technology

Lastly, as the digital age continues to evolve, leveraging modern technologies can also play a significant role in your retirement planning process. With the aid of new tools, you can access personalized financial advice, explore various retirement scenarios, and receive insights that empower you to make informed decisions towards a secure and happy retirement. These tools can aid in personalizing your retirement planning process, offering insights and scenarios for better financial decision-making. We recommend speaking to a Financial Planner for a full rundown.


Conclusion

Smart retirement planning is a multi-faceted endeavor that demands a blend of financial acumen, forward-thinking, and a zest for life. By embracing a holistic approach towards retirement planning, you not only pursue your financial future but also set the stage for a joyful and fulfilling retirement. The journey towards a secure retirement begins with the right financial planning, educating oneself on the financial landscape, and making informed decisions that align with your values and retirement goals.

Instead of spending years mastering finances on your own, partnering with those who have already traversed the financial landscape can fast-track your financial success. A dedicated financial advisor from Trilogy Financial Services can work with you to make your money work smarter and harder, simplifying the financial intricacies that have been keeping you up at night.

You can schedule a no-strings-attached portfolio review today and embark on a path to financial success guided by professional advisors. For more information and to schedule your consultation, visit www.trilogyfs.com/yourmoneyamplified. With the right knowledge and professional guidance, the journey of investing becomes an exciting venture towards achieving financial security and growth. This way, you're not just dreaming of an ideal retirement but actively working towards making it a reality.


*There is no guarantee that a diversified portfolio will enhance overall returns or outperform a non-diversified portfolio. Diversification does not protect against market risk.

Get Started on Your Financial Life Plan Today