3 Qualities of a Meaningful Goal

By
April 11, 2018
Share on:

Not all goals are equal in their achievability. In fact, 92% of people don’t reach the goals they set.1 While goals can be difficult to achieve, they’re not impossible. However, the best way to set yourself up for success is to set meaningful goals.

A meaningful goal sets itself apart from a standard goal in three main ways.

  1. It’s Specific and Measurable

The more specific your goal, the more likely you are to reach it. According to one study, setting specific goals led to a higher performance 90% of the time.2 The reason for this is fairly simple: the clearer the path, the easier it is to follow it to the final destination.

I hear so many people tell me their goal is to save more, spend less, or build a retirement fund. The problem with these goals is that they lack specificity. Saving more could mean saving $10 per month or $1,000 per month. You can’t track your progress or know if you’re on track toward your goal if you haven’t specified it and you can’t measure your progress.

One of the first things I tell clients is to make their goals as specific as possible. For example, instead of “build a retirement fund,” you can specify it to “build a retirement fund of $100,000.” Finally, make it measurable—”build a retirement fund of $100,000 by age 45.”

  1. It’s Relevant to Your Life

A goal is only meaningful if you’re passionate about it. Those who meet their goals do so not just because they’re hard workers, but because they are passionate about what they want to achieve. Their goals reflect their values and interests, rather than being random or something they think they’re supposed to achieve in life.

For example, some clients tell me they want to build their savings account because they’ve been told that’s what they should do. While true, you likely won’t feel very inspired to save more if you don’t have a reason for it that makes sense for your life.

I tell these clients to think of what having a savings account would mean for them. Would they feel they could sleep better at night? Would a savings account mean they could go on an annual family vacation? If they build a savings account up to a certain amount, could they finally upgrade their unreliable and problematic car?

Whatever your goal, you should be passionate about it and it should be relevant to your life, not what you think you’re supposed to achieve.

  1. Frame it Positively

We’ve all heard about the power of positive thinking, and it translates to your goals, too. We are much more likely to work toward something we want to achieve or do rather than what we want to stop doing or don’t want.

For example, rather than a goal of “stop overspending” or “spend $200 less each month,” frame it in a positive light: “spend more mindfully” or “save $200 each month.” This can help you view saving as a good thing you’re supposed to do, rather than spending as a treat that you no longer should do. It’s easy to reverse any goal, so there’s no excuse not to!

Don’t Go it Alone

The process of setting a goal is just as important as the process of working towards it. Think of your goal as the frame of a house. You can’t build a stable home without the proper foundation and a clear blueprint.

If you’re struggling to achieve your goals or aren’t sure how to set ones that are meaningful, an advisor can help. As an independent financial advisor, my mission is to make a meaningful impact on the lives of my clients and the people they love. I help families make informed decisions with their money and pursue a strong financial future, from setting meaningful goals to guiding them along the path toward the finish line.

Contact me for a no-strings-attached meeting to discuss your goals, how to make them meaningful, and what strategies can help you pursue them. Call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com.
1 http://www.inc.com/marcel-schwantes/science-says-92-percent-of-people-dont-achieve-goals-heres-how-the-other-8-perce.html

2 http://psycnet.apa.org/record/1981-27276-001

You may also like:

By
David McDonough
July 2, 2019

Retirement is a big deal, and there are a lot of moving components to plan out. Those issues multiply when there is another individual added to the mix. My definition of retirement is the financial freedom to move into the next chapter of your life, and that next chapter is different for everyone –especially spouses! This is not the time to assume the two of you are on the same page or decide that the two of you will figure it out later. Most people know that I’m a big proponent of talking to your spouse about everything financial, and retirement is no exception.  Be sure to take the guess work out of this process so you can enter the next chapter of your life in harmony.

It’s not uncommon for couples to not see eye-to-eye on retirement. About half of couples don’t agree on what age to retire[i]. Less than 10% of surveyed couples retired at the same time[ii]. And 47% disagreed on how much they would need to save for retirement[iii]. With so many areas to disagree, from where to retire to how to spend your days, how do spouses work together to achieve their cumulative goals?

I always like to recommend the couples start off by taking my financial compatibility quiz. Not only does this show the areas you may not see eye-toe-eye on, but the quiz generates a lot of conversations. Continue these conversations at monthly financial date nights to make sure that the two of you continue on the same path towards the same goals. Talk about the details – at what age do you want to retire, how do you want to spend your days in retirement, and how much of that time will be spent together. Keep in mind that most people have spent over 40 hours a week away from their spouse for decades. Retirement frees up all that time, which can be too much “togetherness” for some couples. This is why I like to take my clients through a discussion on “your time, my time, and our time,” well before it is actually time for retirement. Discussing these things in advance can allow you to compromise on issues before emotions flair and make a world of difference between living together happily in retirement or, in worst cases, filing for divorce.

Once you have an idea of what your retirement goals are, you need to formulate a plan. An experienced financial planner can be a great resource at this time, bringing up things you may not have touched on and running “what if” scenarios for you to see how your retirement dreams can be converted into actionable goals. Please start these discussions early because financial independence takes many forms, but you can’t figure out when you’re going to get there until you plan your route.

Marriage is many things, but ultimately, it is a partnership. The two of you work together to move the household forward. You may not always agree, but you find common ground by talking and sharing and compromising. If you plan ahead and plan together, you can find the right way to your coupled vision of retirement.

Take our FREE Financial Compatibility Quiz here.

[i] https://www.fidelity.com/bin-public/060_www_fidelity_com/documents/couples-retirement-fact-sheet.pdf

[ii] https://assets.aarp.org/rgcenter/general/retired_spouses.pdf

[iii] https://www.fidelity.com/bin-public/060_www_fidelity_com/documents/couples-retirement-fact-sheet.pdf

The opinions voiced in this material are for general information only and are not intended to provide specific advice or recommendations for any individual.

By Trilogy Financial
February 20, 2024

Introduction:


Selecting a qualified financial planner is crucial for securing a robust financial future. A proficient planner, like those at Trilogy Financial, can create a financial plan tailored to your unique needs to help you reach your goals.  Yet, a staggering 74% of Americans engage in financial planning without professional guidance, revealing a potential gap in making informed choices​2​.


Advisor meeting clients.


Mistake 1: Overlooking Qualifications


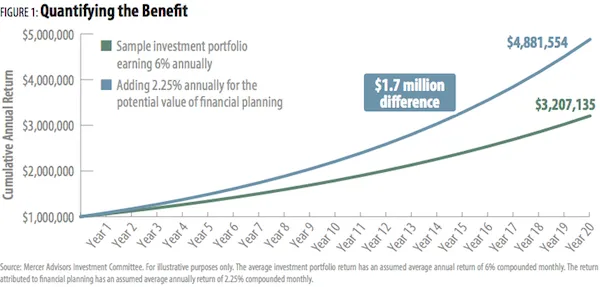
Chart quantifying the benefit of a financial planner.


  • Stat: Smart financial planning can yield 1.5% more in annual average returns, underlining the importance of qualified guidance​3​.
  • Tip: When choosing an advisor ensure  your planner holds pertinent certifications and showcases a robust track record of expertise.
  1. What are pertinent certifications for a financial planner?Pertinent certifications include the Certified Financial Planner (CFP), Chartered Financial Analyst (CFA), and Certified Public Accountant (CPA) designations. These certifications indicate a high level of expertise and adherence to industry standards.
  2. How can I verify a financial planner's certifications?You can verify a planner's certifications by checking the databases of certifying bodies like the CFP Board or the CFA Institute. Additionally, you can ask the planner for proof of certification.
  3. What constitutes a robust track record of expertise?A strong track record includes many years of experience, successful financial planning, happy clients, and industry recognition or awards.
  4. How can I assess a financial planner’s track record?You can assess a planner’s track record by reviewing client testimonials, checking for any industry awards or recognitions, and asking for references. Additionally, verifying their work history and experience in the field can provide insights into their expertise.


Mistake 2: Neglecting Fee Structures


  • Stat: According to a 2019 Financial Trust Survey, “Nearly half of Americans (48%) incorrectly believe all financial advisers have a legal obligation to act in clients’ best interests.”4.
  • Tip: Understand the fee structures and ensure transparency in your financial engagements if you chose to work with a financial advisor.
  1. What are common fee structures in financial planning?Common fee structures include fee-only (fixed, hourly, or percentage of assets managed), commission-based, and fee-based (a combination of fees and commissions).
  2. How can I ensure transparency in fee structures?Ask your financial planner for a clear, written explanation of all fees and charges, including any potential third-party fees, before engaging their services.
  3. What is the difference between fee-only and fee-based financial planners?Fee-only planners charge a flat fee, hourly rate, or percentage of assets managed, and do not receive commissions from selling financial products. Fee-based planners, on the other hand, may charge fees and also receive commissions, which could potentially lead to conflicts of interest.
  4. How do commissions affect the advice I receive?Commissions could potentially create a conflict of interest if a financial planner is incentivized to recommend certain products that earn them commissions, rather than what's in your best interest.


Mistake 3: Disregarding a Personalized Approach


Advisor providing a personalized approach to financial planning


  • Stat:  A Bankrate 2019 survey shows that 44% of individuals with a personal finance plan save more for retirement and 43% save 50% more per month.​5​
  • Tip: When hiring a financial advisor opt for financial planners like those at Trilogy Financial, who prioritize a personalized approach to meet your unique financial objectives​​.
  1. What does a personalized approach in financial planning entail?A personalized approach means that the financial planner takes the time to understand your individual financial circumstances, goals, risk tolerance, and future aspirations to craft a strategy tailored to meet your unique needs.
  2. Why is a personalized approach important in financial planning?A personalized approach ensures that your financial plan is aligned with your goals and circumstances, which can lead to better financial outcomes and satisfaction over time.
  3. What are some examples of unique financial objectives that would benefit from a personalized approach?Unique financial objectives could include planning for early retirement, saving for a child's education, managing a large inheritance, or preparing for a significant life change like marriage or starting a business.
  4. How does a personalized approach compare to a one-size-fits-all approach in financial planning?A personalized approach provides tailored advice and strategies based on your individual circumstances, which can lead to more effective financial planning and better outcomes compared to a one-size-fits-all approach that may not align with your personal goals and risk tolerance.


Mistake 4: Ignoring a Comprehensive Service Offering


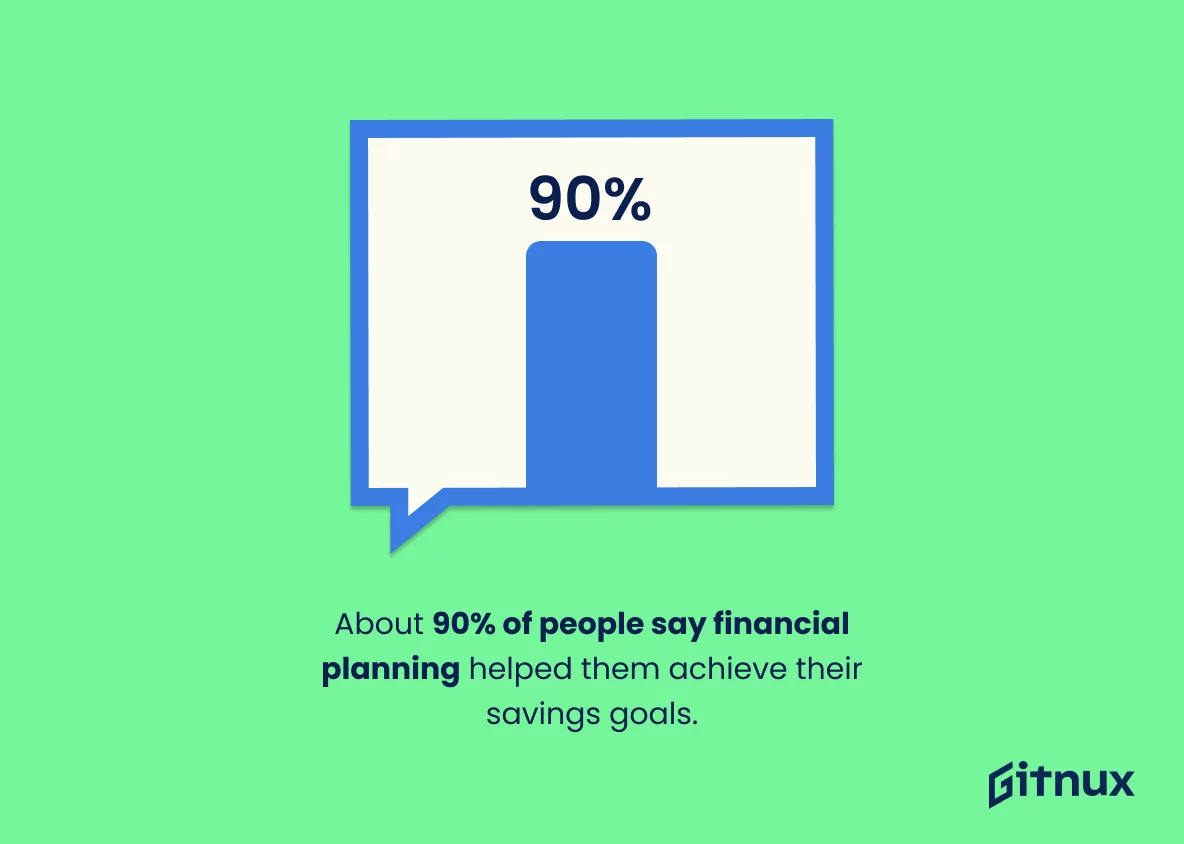
Chart showing 90% of people say financial planning helped them achieve their saving goals.


  • Stat: A whopping 90% of individuals achieved their savings goals owing to comprehensive personal finance plans, emphasizing the necessity of a holistic service offering​ 6​.
  • Tip: Choose a planner offering a spectrum of services including retirement planning, estate planning, and risk management.
  1. Why is it important for a financial planner to offer a variety of services?A variety of services allows for a holistic approach to financial management, ensuring that all aspects of your financial life are considered and managed in a coordinated manner. This might include mutual funds, tax planning, and more.
  2. What is retirement planning, and why is it crucial?Retirement planning involves preparing for life after you stop working, which includes saving, investing, and making other financial arrangements to ensure a comfortable living post-retirement.
  3. What does estate planning entail?Estate planning involves the management and disposal of an individual's estate during their life and at and after death, while minimizing gift, estate, generation skipping transfer, and income tax.
  4. What is risk management in the context of financial planning?Risk management in financial planning refers to the identification, assessment, and strategizing to mitigate or manage financial risks that could negatively impact your financial situation.


Mistake 5: Underestimating Continuous Communication


  • Stat: Clients report higher satisfaction levels with higher frequencies of investment-related educational communications and scheduled meetings, underscoring the importance of continuous communication​ 7​.
  • Tip: Ensure your financial planner maintains open channels of communication, keeping you informed and engaged throughout your financial journey.
  1. How can I ensure that my financial planner maintains open channels of communication?
    You can set expectations for communication upfront, such as preferred methods of communication and frequency of updates. It's also helpful to choose a planner who is responsive and willing to engage in regular discussions about your financial plan.
  2. Why is communication important in financial planning?
    Communication is crucial to ensure that you and your financial planner are on the same page regarding your financial goals, risk tolerance, and any changes in your financial circumstances. It also helps in building trust and understanding throughout the financial planning process.
  3. What are some red flags regarding communication with a financial planner?
    Red flags could include lack of responsiveness, unwillingness to answer your questions, failure to provide clear explanations, or not initiating regular reviews and updates as agreed upon.
  4. How can effective communication with a financial planner impact my financial journey?
    Effective communication can lead to better understanding, trust, and alignment between you and your planner, which in turn can result in a more effective financial plan and a more satisfying financial journey.


Conclusion:


Avoiding these common pitfalls when choosing a financial planner can significantly steer your financial voyage towards success. Engaging with a reputable firm like Trilogy Financial not only helps sidestep these mistakes but also ensures a tailored, client-centric approach delivered by qualified professionals, fostering transparent communication throughout your financial journey​1​.


Get Started on Your Financial Life Plan Today