3 Lies We Believe When It Comes To Financial Planning

By
July 12, 2018
Share on:

There may be plenty of factors outside of your control that impact your financial situation, such as the markets, the economy as a whole, or an unexpected illness. But those circumstances may not play as critical of a role in your financial life as you might think. The real dangers to your financial future are the lies you tell yourself when it comes to financial planning. Here are some ways you could be undermining your financial success and some ideas on how to change course.

Lie #1: I Don't Need Help. I Know What I'm Doing

Let’s say you read a plethora of financial planning books, stay up-to-date on the markets, and know all about budgeting software. That may put you ahead of a lot of other people, but there are certain aspects of financial planning that often go ignored even by the most knowledgeable people. Let’s look at a couple of hypothetical examples.

How Often Do You Review?

How often do you refresh your goals, adjust your plan, and determine how and when to make changes? A financial planner does more than just monitor your portfolio. They act as your coach, motivating and guiding you when things get tough. They bring an objective perspective to the table and develop a customized strategy based on your financial priorities. The end result is increased confidence in your financial strategies and decision-making. You don’t want to suffer a financial setback just because you were too busy or too forgetful to keep up with your financial plan.

In Case of Emergency

What if the unthinkable were to happen and you couldn’t make financial decisions? Will your family be able to handle the details and figure out your financial plan? An advisor can offer a holistic overview of your net worth and determine what elements need to be in place to protect your family and your wealth. These are often things you may not be aware of, such as life insurance or a living trust.

Market Research

Investing is tricky business on a good day. Can you manage the emotions, anxiety, and possible second-guessing of your investment choices if you were living on a fixed income and the market were to face a correction? An advisor has tools to evaluate cash flow to help you determine the probability of your money lasting through your retirement years. They can also keep you accountable and committed to your long-term strategy in the midst of market ups and downs.

Lie #2: I Can Always Get Help When I Need It

If you were going on vacation, would you rather have everything packed ahead of time and enjoy your restful break? Or would you prefer to be disorganized and arrive without essential items, forced to then spend your time off running around shopping for things you forgot? When it comes to money, it’s the same idea. When you really need the help, you may have lost your most valuable resource – time. Instead of thoughtfully researching your options and making decisions with a clear head, waiting until you need help will result in a frantic scramble to just get things done.

Whatever it is you experience in life, having a financial planner on your team will help you stay on top of your money and prepare in advance for future milestones and events.

Lie #3: I Don't Need An Advisor, I Have Financial Technology

Financial planning has evolved. Years ago, it was about who had the most up to date information on a company to buy a stock, and the planning industry was mostly concerned with buying and selling stocks and bonds rather than portfolio management. Today, financial planning is more about what’s missing in your overall strategy, what have you not thought of, and what could you be doing that you’re not. On top of that, the financial planning process helps you emotionally connect with your goals so you can get on the right track. Technology, at the present time, can’t do that.

Technology has many good points, but several drawbacks as well. For example, you can find more information than you’ll ever need, but you’ll also come across plenty of misinformation which could lead you astray. It’s not uncommon for someone to research something on the Internet and find just as many pros as there are cons. If you want to save for your child’s college education, you’ll find articles touting the value of using a 529, a Roth IRA, or a Roth 401(k). How do you figure out which one is truly right for you? The abundance of information has created so much noise that in many cases, people don’t do anything at all.

While technology should be used in financial planning, it should not replace the role of an advisor. The importance of what advisors do from a human aspect is help clients sift through the noise and misinformation and encourage them to move forward in taking action.

A Change In Perspective?

Have you ever believed one of these lies? It’s easy to do, but the consequences are real. Don’t take a gamble with your money. Join forces with a financial advisor who can help you make the most of what you have, where you are, and get you positioned for a bright financial future. Call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com for a no-strings-attached meeting to discuss your situation.
You may also like:

By
Mike Loo, MBA
April 11, 2018

Not all goals are equal in their achievability. In fact, 92% of people don’t reach the goals they set.1 While goals can be difficult to achieve, they’re not impossible. However, the best way to set yourself up for success is to set meaningful goals.

A meaningful goal sets itself apart from a standard goal in three main ways.

  1. It’s Specific and Measurable

The more specific your goal, the more likely you are to reach it. According to one study, setting specific goals led to a higher performance 90% of the time.2 The reason for this is fairly simple: the clearer the path, the easier it is to follow it to the final destination.

I hear so many people tell me their goal is to save more, spend less, or build a retirement fund. The problem with these goals is that they lack specificity. Saving more could mean saving $10 per month or $1,000 per month. You can’t track your progress or know if you’re on track toward your goal if you haven’t specified it and you can’t measure your progress.

One of the first things I tell clients is to make their goals as specific as possible. For example, instead of “build a retirement fund,” you can specify it to “build a retirement fund of $100,000.” Finally, make it measurable—”build a retirement fund of $100,000 by age 45.”

  1. It’s Relevant to Your Life

A goal is only meaningful if you’re passionate about it. Those who meet their goals do so not just because they’re hard workers, but because they are passionate about what they want to achieve. Their goals reflect their values and interests, rather than being random or something they think they’re supposed to achieve in life.

For example, some clients tell me they want to build their savings account because they’ve been told that’s what they should do. While true, you likely won’t feel very inspired to save more if you don’t have a reason for it that makes sense for your life.

I tell these clients to think of what having a savings account would mean for them. Would they feel they could sleep better at night? Would a savings account mean they could go on an annual family vacation? If they build a savings account up to a certain amount, could they finally upgrade their unreliable and problematic car?

Whatever your goal, you should be passionate about it and it should be relevant to your life, not what you think you’re supposed to achieve.

  1. Frame it Positively

We’ve all heard about the power of positive thinking, and it translates to your goals, too. We are much more likely to work toward something we want to achieve or do rather than what we want to stop doing or don’t want.

For example, rather than a goal of “stop overspending” or “spend $200 less each month,” frame it in a positive light: “spend more mindfully” or “save $200 each month.” This can help you view saving as a good thing you’re supposed to do, rather than spending as a treat that you no longer should do. It’s easy to reverse any goal, so there’s no excuse not to!

Don’t Go it Alone

The process of setting a goal is just as important as the process of working towards it. Think of your goal as the frame of a house. You can’t build a stable home without the proper foundation and a clear blueprint.

If you’re struggling to achieve your goals or aren’t sure how to set ones that are meaningful, an advisor can help. As an independent financial advisor, my mission is to make a meaningful impact on the lives of my clients and the people they love. I help families make informed decisions with their money and pursue a strong financial future, from setting meaningful goals to guiding them along the path toward the finish line.

Contact me for a no-strings-attached meeting to discuss your goals, how to make them meaningful, and what strategies can help you pursue them. Call my office at (949) 221-8105 x 2128, or email me at michael.loo@lpl.com.

1 http://www.inc.com/marcel-schwantes/science-says-92-percent-of-people-dont-achieve-goals-heres-how-the-other-8-perce.html

2 http://psycnet.apa.org/record/1981-27276-001

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


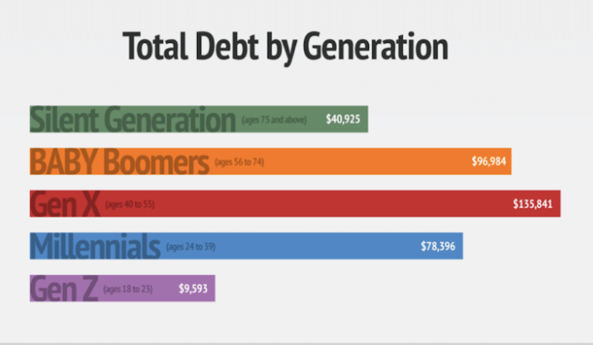
  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


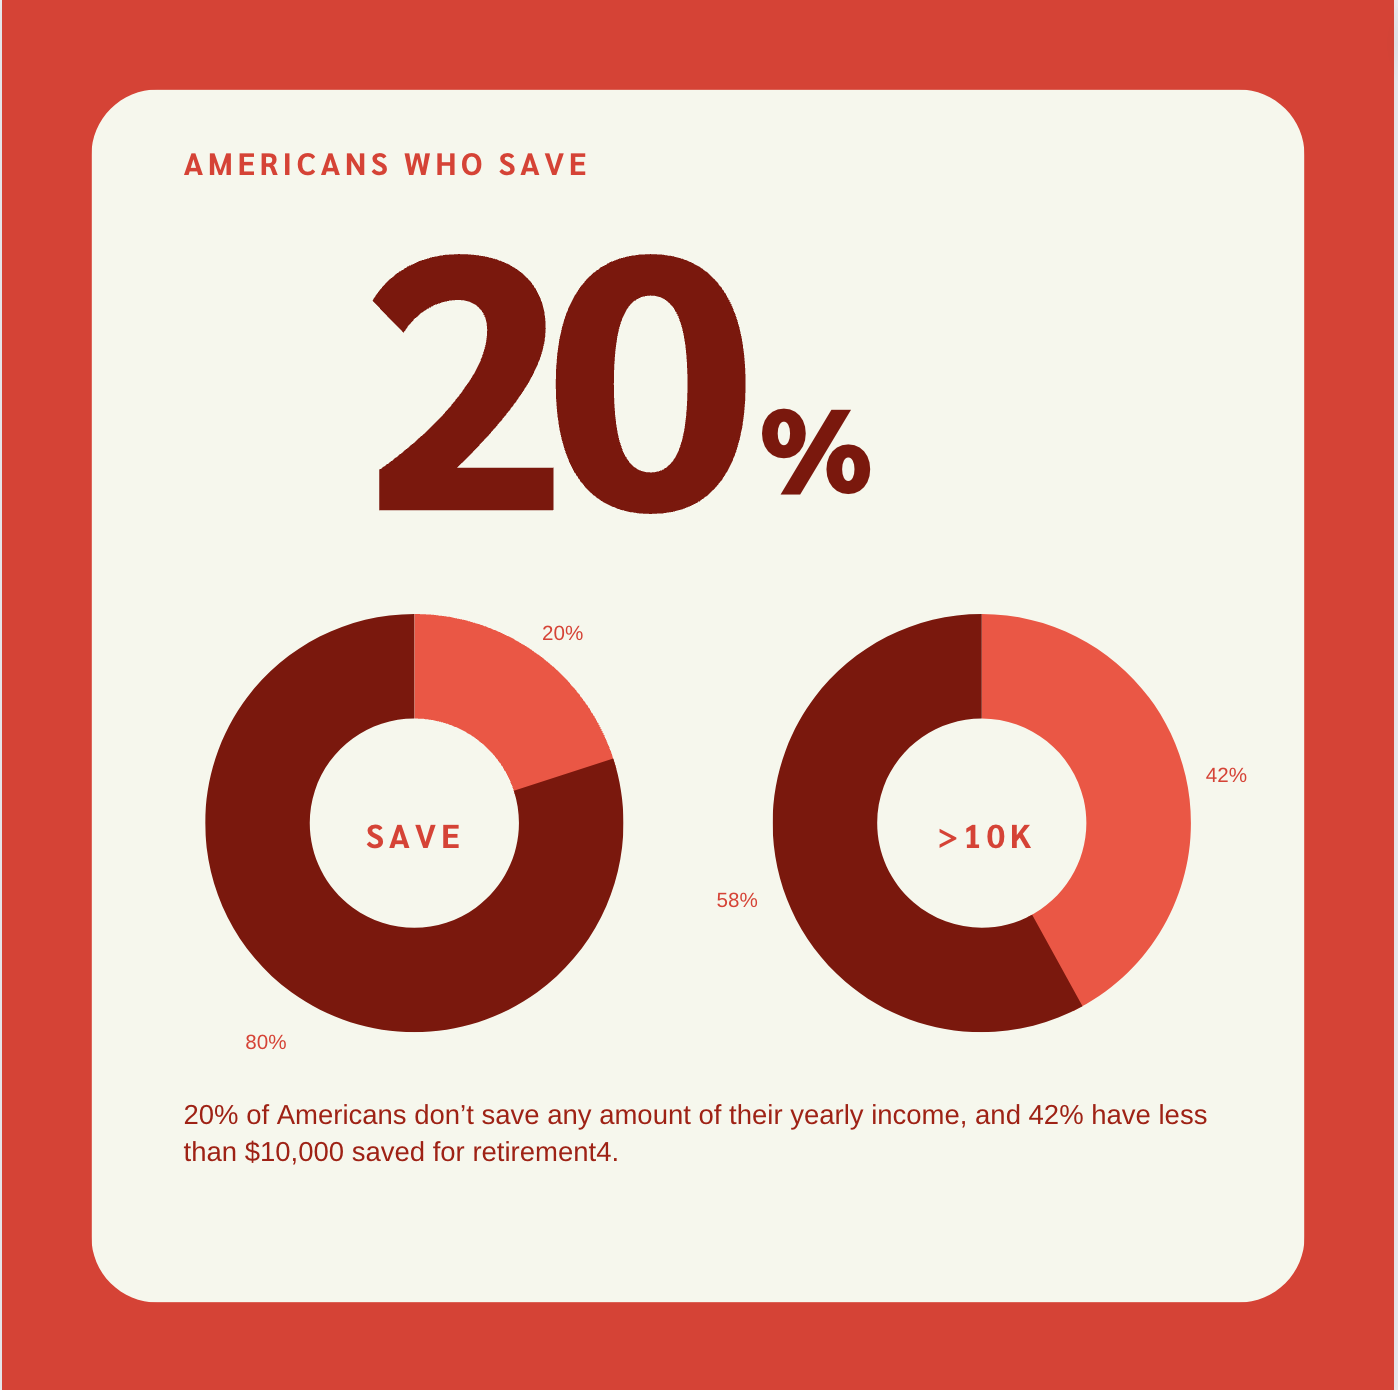
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5​.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


Get Started on Your Financial Life Plan Today