11 Things to Know: Advanced Estate Planning for High Net Worth Individuals

By Trilogy Financial
July 17, 2024
Share on:

Estate planning consultants for high net worth families know that ensuring your financial assets are managed according to your wishes is crucial. At Trilogy Financial, we understand the importance of creating a comprehensive estate plan that addresses your unique needs and goals. Here are the critical elements of an effective estate plan to help you secure your financial future.


1. Will


A will is the cornerstone of any estate plan. This legal document outlines how you want your assets distributed and names an executor to oversee the process. A will can also designate guardians for minor children, ensuring their care and well-being. Without a will, your estate may undergo a lengthy and costly probate process, and your wishes may not be honored.


2. Letter of Intent


A letter of intent is a personal document that complements your will. While it is not legally binding, it can provide clarity and guidance to your executor and loved ones about your wishes. This letter can include details about asset distribution, heirlooms, and even funeral arrangements. Updating your letter of intent regularly ensures that it reflects your current wishes.


3. Power of Attorney


A power of attorney document allows you to appoint someone you trust to handle your financial and legal affairs if you become incapacitated. This person, often a family member or close friend, can manage your assets, pay bills, and make important decisions on your behalf. Understanding your state’s specific regulations can help you make informed decisions about this designation.


4. Health Care Directives


Health care directives are essential for addressing your medical needs in emergencies. Key documents include:

  • Living Will: Specifies your medical care preferences if you become incapacitated.
  • Durable Medical Power of Attorney: Authorizes someone to make medical decisions on your behalf.
  • HIPAA Release Clause: Allows medical professionals to share your health information with your designated proxy.


5. Estate Planning for Second and Third Marriages


Subsequent marriages add complexity to estate planning. Consider the following:

  • Prenuptial Agreements: Protect assets and provide clarity on ownership.
  • Updated Legal Documents: Ensure your estate plan reflects your new family structure.
  • Beneficiary Considerations: Update beneficiaries to include your new spouse, if desired.


6. Guardianship Designations


If you have minor children, naming guardians in your estate plan is vital. This ensures that someone you trust will care for your children if you are unable to do so. Consider naming a backup guardian as an additional safeguard.


7. Trusts


Trusts offer a flexible and private way to manage and distribute your assets. Benefits of trusts include:

  • Avoiding probate
  • Maintaining privacy
  • Providing effective asset management
  • Offering control over beneficiary distributions


8. Multi-Generational Wealth Planning


Multi-generational wealth planning is essential for ensuring that your financial legacy benefits future generations. This involves creating strategies that protect and grow your assets while considering the needs of your children and grandchildren.


9. Trust Fund Manager


trust fund manager plays a critical role in managing and distributing your assets according to your wishes. This professional ensures that the trust operates smoothly and that beneficiaries receive their designated assets without delays or legal complications.


10. Advanced Estate Planning Strategies


Advanced estate planning strategies are designed to address the unique needs of high-net-worth individuals. These strategies may include setting up complex trusts, charitable giving, and tax optimization techniques to preserve and grow your wealth.


11. Philanthropic Financial Planning


Philanthropic financial planning allows you to support causes you care about while benefiting from potential tax advantages. Discovering philanthropic financial planning opportunities can help you make a positive impact while strategically managing your estate.


The Takeaway –


Creating a comprehensive estate plan involves careful consideration of various legal documents and strategies. At Trilogy Financial, we specialize in estate planning for high net worth families and individuals, providing tailored solutions to meet your unique needs.

Our team of estate planning lawyers for high net worth families and high net worth estate planning attorneys are here to guide you through every step of the process. If you have questions or need assistance, please reach out to us. We are here to help.


Ready to Amplify Your Wealth today?

If you're ready to elevate your financial planning with our professional team, we invite you to schedule a meeting with us. At Trilogy Financial Services, our advisors in Corona are dedicated to crafting personalized financial strategies that align with your unique goals. Don't wait to start your journey towards financial success:

  • Schedule a Meeting: Reach out to us to arrange a one-on-one consultation with our financial professionals.
  • Give Us a Call: Prefer a quick conversation? Feel free to give us a call to discuss your financial needs and how we can assist. Call Us To Get Started. (844) 356-4934

Schedule a No-Strings-Attached Portfolio Review today and embark on a path to financial success guided by professional advisors. For more information and to schedule your consultation, visit www.trilogyfs.com/yourmoneyamplified. With the right knowledge and professional guidance, the journey of investing becomes an exciting venture towards achieving financial security and growth. This way, you're not just dreaming of an ideal retirement but actively working towards making it a reality.
You may also like:

By Trilogy Financial
February 20, 2024

Have you ever envisioned a life of Financial Freedom and Leisure?

Have you ever envisioned a life where the chains of daily grind are broken well before the conventional retirement age, paving the way for a life of financial freedom and leisure? Embracing financial discipline and frugality can pave the way to a comfortable early retirement, answering the pressing question: Can meticulous financial planning and a frugal lifestyle significantly hasten your journey to early retirement?


What Makes Financial Planning Crucial?


Financial planning goes beyond merely saving a portion of your income; it's about understanding and rectifying financial bad habits that may impede your journey towards financial stability. Everyday financial misbehaviors such as impulsive spending, credit card debt, and the lack of a structured financial plan for emergencies often go unnoticed but have a long-term detrimental impact on financial health. Addressing these personal finance habits is the first step in financial planning.


  • Why is Debt Management Essential? A key aspect of financial planning involves managing or eliminating debt, which can otherwise consume a significant portion of your income in the form of interest payments.
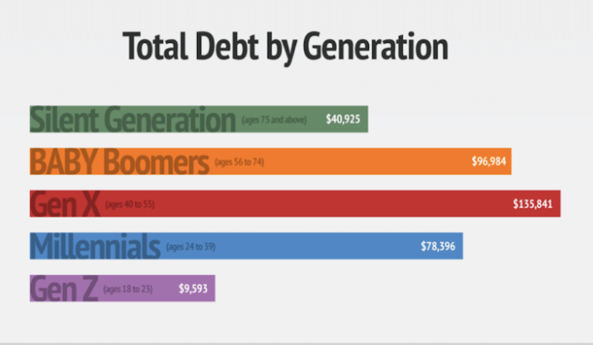
    • Did you know in the US for 50-59-year-olds the average debt is $23,719 1.
  • How Can Budgeting Secure Your Financial Future? Being unsure of where your money is going is a red flag. Budgeting is crucial to track and control spending, ensuring your expenditures align with your values.
    • Did you know the average individual aged between 65 to 74 spends about $55,000 on living expenses annually​2​.
  • How do Savings and Investments Impact Your Retirement Goals? Setting aside money for an emergency fund and future investments is essential. Automating this process by having a portion of your income transferred to savings or investment accounts can help in cultivating this good financial habit.
    • Americans believe they need an average of $1.7 million to retire comfortably, although many won't accumulate enough net worth to retire​3​.
    • As of 2019, only 11% of Baby Boomers managed to save up to $500,000 for their retirement​2​.


Screenshot 2023-11-21 at 3.06.25 PM

What Does Adopting a Frugal Lifestyle Entail?

Frugality is about making informed and restrained financial decisions to save money. A frugal lifestyle encourages avoiding unnecessary expenses and finding value in what you spend.


  • Examples of frugal practices include avoiding spending triggers like malls or online shopping platforms, utilizing cash over credit to prevent overspending, and finding cost-effective alternatives for everyday expenses.


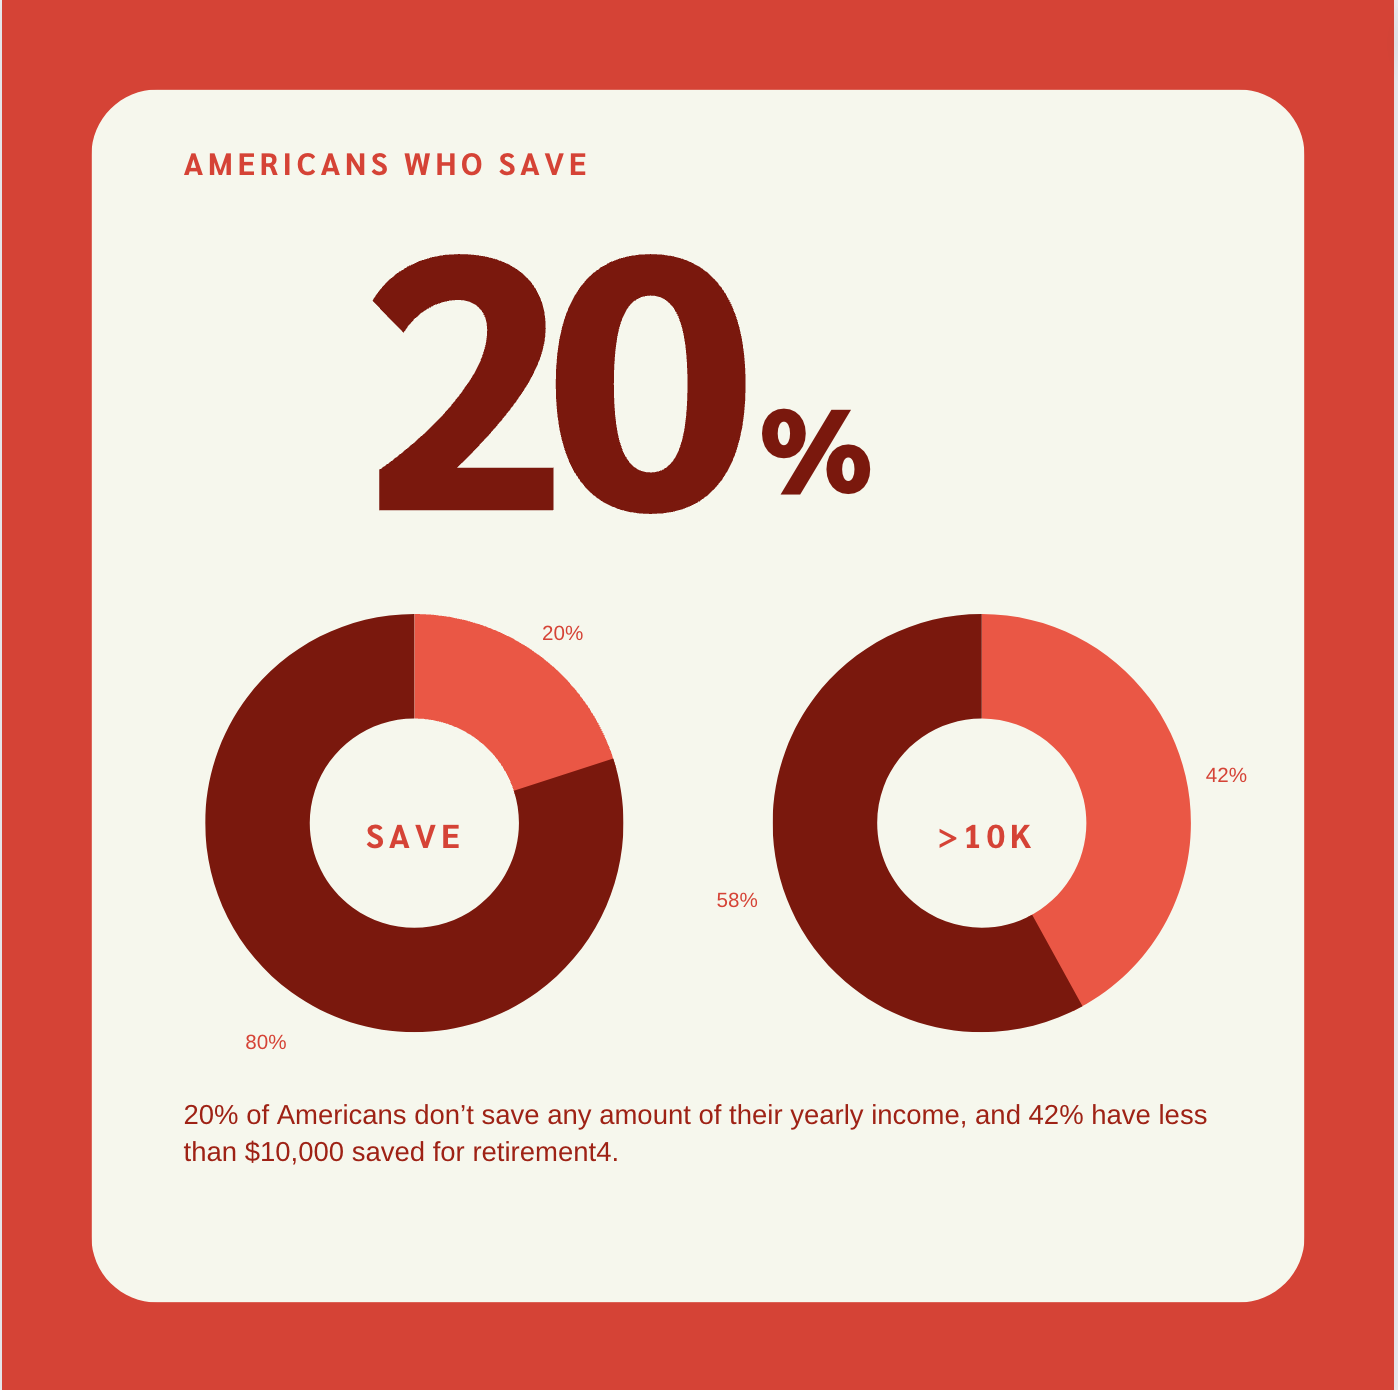
Did you know 20% of Americans don’t save any amount of their yearly income, and 42% have less than $10,000 saved for retirement​4​.


What are the Key Components of Financial Planning for Early Retirement?


  • Emergency Fund: Ensuring you have an emergency fund can help buffer against unforeseen circumstances like a job loss or medical crisis, which might otherwise derail your financial plans.
  • Investment Strategy: Diversifying your investments and aligning them with your retirement goals is imperative for financial growth.
    • 84% of Americans have a higher income than their parents did at the same age, indicating potential for savings and investment if managed wisely​4​.
  • Tax Planning: Efficient tax planning can help in preserving your wealth and ensuring more of your money is working for you rather than going towards taxes.
  • Healthcare Planning: As healthcare costs can be exorbitant, planning for these expenses is crucial to avoid financial strain in later years.
    • Healthcare can be a significant part of living expenses, as seen in the $55,000 annual spending for individuals aged 65-74​5.


Which Tools and Resources Can Aid Your Financial Planning Journey?


There are myriad tools and resources available to aid in your financial planning journey. Budgeting apps, financial advisors, and online courses are excellent resources. Trilogy Financial, for instance, offers a Decision Coach program designed to provide additional accountability and coaching to individuals seeking financial guidance.

  • 37% of workers aged 25 and older, and 19% of retirees, report not knowing where to go for financial or retirement planning advice​5​.

Easily Meet with a Certified Financial Planner.


image3-1
 

How Have Others Achieved Financial Independence and Early Retirement?


The quest for early retirement often begins with a thorough re-evaluation of one's financial plan, identifying areas of improvement, and capitalizing on unforeseen savings opportunities. The year 2020 saw many Americans saving more, with an average of 10% more money saved compared to 2019, mainly due to lifestyle changes induced by the pandemic. Some redirected these savings towards home improvements, while others saw it as a stepping stone towards drafting a solid financial plan aimed at debt reduction, college planning, or accelerating the journey to financial independence.


Various individuals and communities dedicated to frugal living and meticulous financial planning have emerged over the years, showcasing diverse pathways to early retirement. Here are a few noteworthy examples:


  • Juan's Early Retirement Ambition: Juan, an aspiring early retiree, aimed to bid farewell to his federal job by 2031 at the age of 43. His strategy revolved around living off savings, investments, and dividends post-retirement to enjoy more time with family and delve into philanthropic ventures. Though new to the Financial Independence, Retire Early (FIRE) movement, Juan's no debt and $85,000 asset accumulation puts him in a favorable position towards achieving his goal​1​.
    • The FIRE Movement: The Financial Independence, Retire Early (FIRE) community exemplifies the synergy between frugal living and early retirement. Members of this movement, like Juan, embody a lifestyle of extreme savings and frugality, aiming to retire much earlier than the conventional age​2​.
  • Young Adults Eyeing Early Retirement: The allure of early retirement isn't confined to older age groups. One in four individuals between 18 to 34 years old has set early retirement as their significant financial milestone, driven by the principles of frugal living and meticulous financial planning​3​.
  • A 5-Year Transition Plan: A couple outlines their 5-year plan towards financial independence, with one partner continuing full-time work for an additional 3-4 years, demonstrating a balanced approach to achieving early retirement while maintaining a comfortable lifestyle​4​.
  • Frugal Living as a Fast Track to Early Retirement: The narrative of saving 75% of income, a hallmark of frugal living, expedites the journey towards early retirement, allowing individuals to accumulate substantial savings, invest wisely, and achieve financial independence sooner​5​.


These cases highlight the transformative impact of frugal living and prudent financial planning to achieve early retirement dreams. They speak to the importance of continuous financial plan evaluation, adapting to changing circumstances, and leveraging savings opportunities to expedite the journey to financial independence and early retirement.


Conclusion:

The road to early retirement is laden with challenges, primarily stemming from our own financial bad habits. However, if we create a financial plan, adopt a frugal lifestyle, and leverage available resources, overcoming these challenges and retiring early is an achievable goal.


By
Mike Loo, MBA
January 9, 2019

A recent survey found that among Millennial parents, nearly half have received financial support from their Baby Boomer parents in the past year, and 69% received financial support specifically for their own young children.(1) Another poll found that 3 in 4 parents with adult children have helped them pay both debts and living expenses.(2)

Clearly, it is common practice nowadays for parents to provide financially for both their adult children and their grandchildren. Many Baby Boomers are at a place where they are financially secure and have the desire to give their kids a leg up from where they were at the same age. For 2019, up to $15,000 can be gifted from one individual to another without having any tax effects. Many parents are reaching that limit with their gifts to their adult children for their own expenses and gifts to their grandchildren to fund their education and contribute towards their future well-being.

When Your Parents Give You Money

One-Time Gifts

The first thing you have to do is decide what to do with the money. Whether or not it is a one-time gift or will be ongoing will greatly influence your decision. If it is a one-time gift, it likely cannot be used to enhance your current lifestyle. Rather, you could use it to strengthen your current position by paying down debt. You could also use it for a one-time luxury, such as a vacation. Another good use would be to invest it to prepare for the future.

Of course, what you choose to do with the money will depend greatly upon your current financial situation and goals. If you decide to save it for the future, that brings up another set of questions. Where should you put the money? What kind of investment opportunities are available? How soon do you plan on needing it? The answer to each of those questions will determine what you do with the money, whether you put it in a money market account, invest in a brokerage account, or use it to fund your retirement accounts.

Ongoing Gifts

Though they are usually more beneficial, ongoing gifts are actually harder to plan for. You have to ask the same questions as above, but you also have many more options. If it will be a regular gift, you could use it to enhance your lifestyle instead of merely paying down debt or taking a vacation. Or you could use it to take advantage of a business opportunity that wouldn’t be feasible otherwise.

The hard part about ongoing gifts is knowing how safe it is to depend on them. If you make decisions based on the gift, what happens if it doesn’t come or is given sporadically? Many people fear sounding greedy or ungrateful if they ask their parents about money that they expected to receive but didn’t. The dependability of the gift money and the kind of relationship you have with your parents should be taken into account when planning for ongoing gifts.

One thing to be careful of, especially with ongoing gifts, is to not let it affect the stewardship of your own money. It is easy to change good habits and loosen the reins on your spending when you have extra money coming in. But is that wise?

Your parents are giving you money because they want to help you. Are they really helping you if you are simply becoming more careless? You should apply the same careful money habits as you would without the gift, even if it creates enough margin where you wouldn’t have to. Remember, what your parents give you is a gift. It is not required nor guaranteed, and you should manage it with that in mind.

When Your Parents Give Your Children Money

A lot of the same issues apply when your parents gift your children money or give it directly to you but for their benefit, especially when you aren’t sure if the gift will be regular and are not comfortable asking.

First, you need to decide if you should use it to meet current needs or future ones. If you save the money for your children’s college education, it could help them pay for a better school, get a better job, and avoid student debt. But if the money is spent today, it could pay for their childcare and thereby enable you to save more for retirement or get a house in a better school district, which could lead to a better education, admission to better colleges, and scholarships to avoid debt. There is no one right answer and it requires careful consideration of your family’s own unique circumstances and priorities.

College Funding

If you do decide to save the money for your children’s future, that brings up another host of questions. Where is the best place to put the money until you need it? A savings account? A 529 Plan? An UTMA? The answer will depend on a number of factors, including how liquid you want the money to be without penalties and how much control you want to maintain over the money. There are a number of options available to you, each with its advantages and disadvantages.

When saving for college, you need to have a target goal in mind. It is important to estimate the cost of college for your child in order to measure how much you need to be investing, the types of investments you should use, and to monitor your progress. Another reason to have a set goal is to avoid overfunding a college account. There should be a stopping point where you no longer invest in a 529 but rather divert the funds elsewhere. While leftover 529 accounts can be transferred to family members or have the funds removed with penalties, it may be better to simply avoid overfunding them in the first place.

Multiple Children

Having multiple children makes things even more complex because it can be hard to keep things fair and equitable. What happens when your parents, who gave a lot towards your firstborn, begin to taper off the gifts with subsequent children? Or perhaps the same amount was given, but it was divided by more and more children? What can you do so that the later children are not at a disadvantage?

Also, what happens when the gifts begin after you already have more than one child? If your parents start funding a college account when your first child is 5 and your second is 1, then the second may end up with a much higher balance upon entrance to college. What can you do and what should you do to help balance things out?

How I Can Help

These are some of the questions that arise when parents gift money to their adult children and grandchildren. Depending on the scenario, things can quickly become complex. Not only do you have to decide what to do with the money, weighing the benefits and opportunity costs, but you have to decide the best way to accomplish your goals with that money.

This is a common situation that my clients find themselves in when they turn to me for help. Together, we first determine the circumstances in which the money was given and the intent behind it. If your parents had a specific purpose in giving you the money, it is often best to honor that purpose.

Next, we discuss how you can use the money in a way that doesn’t distract you from your goals or cause you to become financially irresponsible. We talk through different scenarios in advance and address the “what-ifs” that could occur in each in order to develop a solid plan. My clients really enjoy having me there as a sounding board to bounce ideas off of, as well as to hear my insights based on the experience that I have had myself and with other clients.

If you’ve found yourself the recipient of financial gifts from your parents, or just need someone to help you sort through your own finances, call me at (949) 221-8105 x 2128 or email me at michael.loo@lpl.com. I would love to partner with you so that you can make wise financial decisions to build a secure future for you and your family.

(1) https://s1.q4cdn.com/959385532/files/doc_downloads/research/2017/Millennial-Parents-Survey-Key-Findings.pdf

(2) https://www.creditcards.com/credit-card-news/pay-adult-childrens-debt-poll.php

Get Started on Your Financial Life Plan Today